(562) 400-4959 vsfoundation@outlook.com

The Best Options for Bad Credit Loans in Texas: A 2026 Ranking
Bad credit loans texas

The Best Options for Bad Credit Loans in Texas: A 2026 Ranking

Last updated: 2026-10-17

Trying to manage money in Texas can feel like driving through a sudden thunderstorm without wipers. When your credit score isn’t where you want it, finding a lender feels less like a stroll and more like a marathon. You need more than a quick cash injection; you need a lifeline that won’t pull you under.

Whether you are facing a sudden transmission failure in Houston or an unexpected medical bill in Dallas, the stakes are high. The temptation to grab the first offer is strong when you are under pressure. You want a solution that actually helps instead of adding to the chaos.

This list is for Texans facing unexpected hurdles, from auto repairs to medical bills. Choosing the right lender requires looking past the glossy advertisements to find actual stability. We focused on finding institutions that prioritize accessibility and transparency, ensuring you can rebuild your footing without falling into a debt trap.

In a state where the cost of living fluctuates wildly between major cities and rural counties, knowing your options is your best defense. Understanding the fine print helps you avoid predatory lending practices that target those in a pinch. Knowledge is the best way to keep your finances on track.

  1. Texas Bay Credit Union
  2. Solarity Credit Union
  3. TexasLoansToday
  4. Wisetack

How Texas Lenders Were Evaluated

Finding the right fit for bad credit loans in Texas isn’t just about finding the fastest money, though speed certainly helps. It is a balance between how easy it is to get approved and the long-term cost of that debt. A lender that says “yes” too easily might be charging interest rates that will keep you broke for years.

We analyzed the fine print of various lending models. We compared the Annual Percentage Rate (APR) against the speed of disbursement to see which lenders offer the best value for immediate needs versus long-term health. Speed is great, but it shouldn’t come at the cost of your future income.

The comparison focused on several key areas: the ease of the application, the speed of funding, and the flexibility of terms. We looked for lenders that serve a wide range of Texas cities and those that offer specialized products like credit builder options. Every entry was vetted to ensure they provide genuine service to those with less-than-perfect credit histories.

We specifically prioritized lenders that offer “soft pulls” for pre-qualification. This allows Texans to shop around without the penalty of a hard inquiry on their credit report. When your score is already fragile, avoiding unnecessary hits to your report is a crucial factor in maintaining stability.

Lender Name Loan Amounts Funding Speed Credit Impact Best For
Texas Bay Credit Union Up to $2,000 (Starter) See site See site Building Credit
Solarity Credit Union See site See site See site Business & Personal
TexasLoansToday $500 – $35,000 24 Hours No Hard Pull Fast Funding
Wisetack See site Under a minute See site Home Services

Top Ranked Texas Lenders for 2026

1. Texas Bay Credit Union
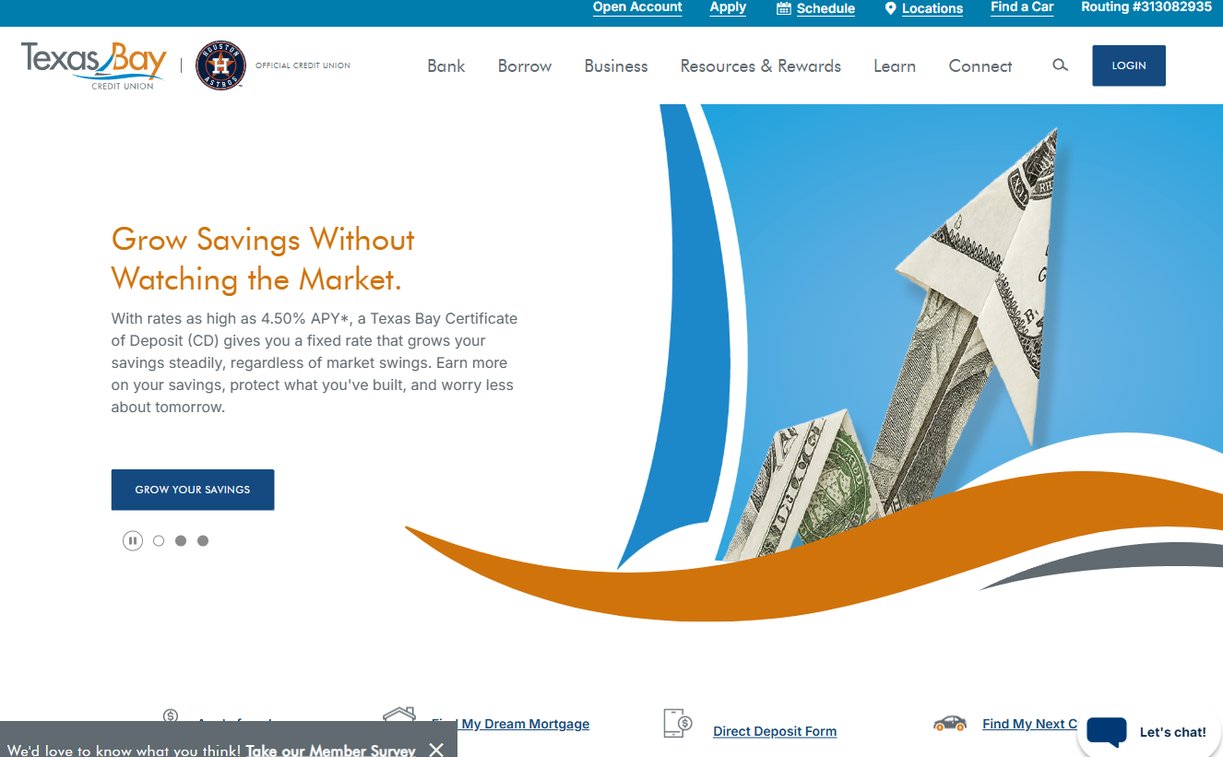
Texas Bay Credit Union – texasbaycu.org

Texas Bay Credit Union acts as a steady hand for those just starting their financial journey. They offer specialized starter loans designed specifically for individuals with little to no credit history. These loans are capped at $2,000, which makes them an excellent entry point for anyone looking to prove their reliability to future lenders.

Unlike traditional big-box banks that might automatically reject a profile with a thin credit file, Texas Bay looks at the broader picture of your financial stability. They understand that everyone starts somewhere, and they provide the tools to help you move forward from that starting point.

Beyond basic credit building, they provide options like auto financing to help you stay on the road. Their products are built to be flexible, ensuring that your budget isn’t stretched to a breaking point. For example, their auto financing programs are tailored to help you secure reliable transportation without the predatory interest rates often found in “buy here, pay here” lots.

Pros:

  • Starter loans specifically for building credit.
  • Flexible auto financing options.
  • Established credit union stability.

Cons:

  • Starter loan amounts are limited to $2,000.

2. Solarity Credit Union
Solarity Credit Union – solaritycu.org

Solarity Credit Union approaches banking with a focus on brightness and simplicity. They cater to a wide demographic, from individuals needing personal support to businesses looking for commercial real estate or lines of credit. Their model is built around providing guidance alongside modern digital tools.

They aim to fill the gap between the convenience of a fintech app and the security of a traditional financial institution. If you are looking to manage both personal and business needs, Solarity offers a comprehensive suite of services. They emphasize a “brighter” banking experience, which translates to knowledgeable employees who actually take the time to listen.

Whether you are a small business owner in Austin trying to expand your inventory or a resident in San Antonio looking to consolidate high-interest debt, their consultative approach helps you map out a path forward. They do more than just hand you a check; they help you understand the implications of your financial choices.

Pros:

  • Wide variety of business and personal products.
  • Emphasis on expert guidance and support.
  • Modern digital banking tools.

Cons:

  • May require more traditional documentation than online-only lenders.

3. TexasLoansToday
TexasLoansToday – texasloanstoday.com

When time is of the essence, TexasLoansToday steps up to the plate. They serve over 1,200 Texas cities and towns, making them a true statewide powerhouse. Their primary advantage is speed, often providing a decision on your application within a single day through a very streamlined process.

In emergencies—such as a sudden plumbing crisis or an urgent repair needed to keep a vehicle on the road for work—this speed can be the difference between stability and catastrophe. They are built for those who cannot afford to wait weeks for a bank’s committee to meet.

This lender is particularly friendly to those worried about their credit score. They offer a “no hard credit pull” option, meaning you can check your rates and see what you qualify for without any damage to your score. This is a critical feature for those attempting to rebuild their credit, as every hard inquiry can shave points off an already delicate score.

Pros:

  • Extremely fast 24-hour funding.
  • No hard credit pull during the initial check.
  • Wide coverage across Texas.

Cons:

  • High interest rate potential for some users.

4. Wisetack
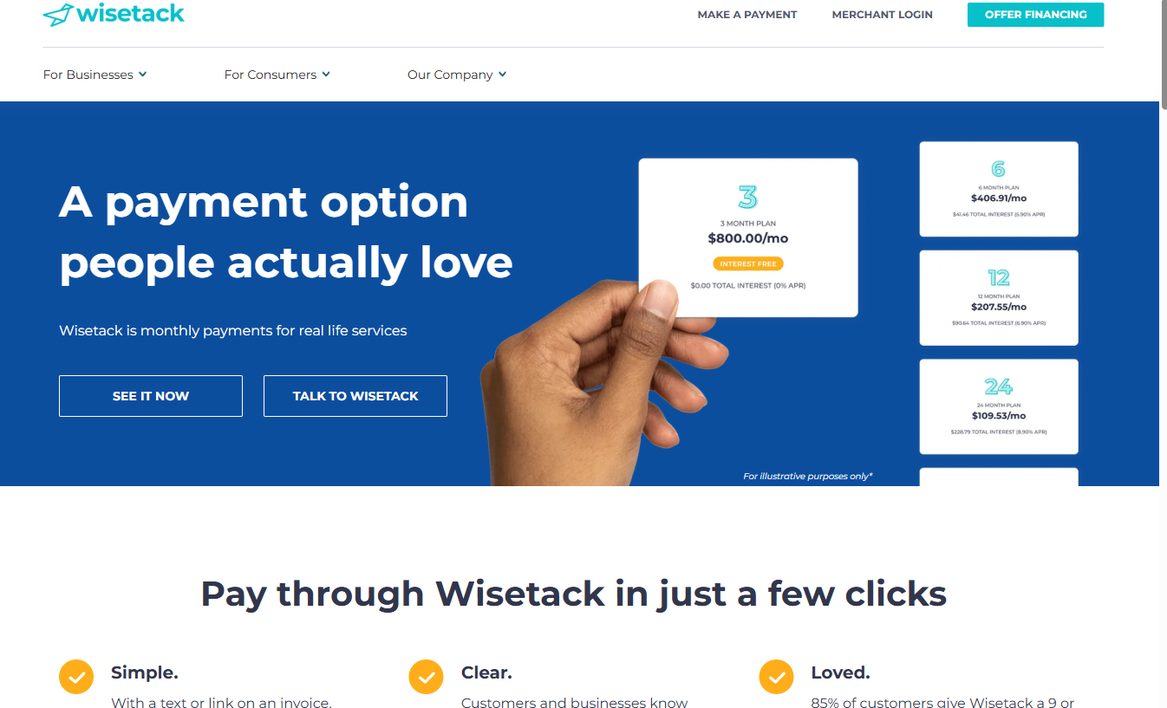
Wisetack – wisetack.com

Wisetack operates a bit differently than a traditional bank, focusing on the intersection of consumers and home service businesses. If you need a repair done on your house—such as HVAC work, roofing, or electrical repairs—this is the way to go. It allows you to see your financing options in under a minute through a simple text or invoice link.

This removes the need to fill out lengthy, intimidating paperwork at a bank branch. The beauty of this system is the transparency. Both the customer and the service provider know exactly what the costs are upfront, which eliminates that awkward “sticker shock” at the end of a job.

This integration creates a closed-loop system where the money goes directly to the service provider, ensuring the job is completed and the consumer is protected. It is highly rated by users who prefer a frictionless, digital-first experience that prioritizes clarity over complexity.

Pros:

  • Instant visibility of financing options via text/link.
  • High customer satisfaction ratings.
  • Seamless integration for home service businesses.

Cons:

  • Limited to financing specific home service transactions.

Understanding the True Cost of Borrowing

Before signing any agreement, it is vital to perform a mathematical autopsy on the loan terms. Many borrowers focus solely on the monthly payment, but this is a dangerous metric. A low monthly payment often indicates a longer loan term, which can result in you paying double or triple the original amount by the time it is satisfied.

To avoid this, you must look at the Total Cost of Loan. To calculate the real impact on your wallet, use this simple step-by-step method:

  1. Identify the APR: Do not just look at the interest rate; look at the Annual Percentage Rate, which includes fees.
  2. Calculate Total Interest: Multiply the monthly payment by the total number of months in the term, then subtract the original principal.
  3. Factor in Fees: Add any origination fees, processing fees, or administrative charges to that total.
  4. Compare: Compare this “all-in” number against other offers to see which lender is actually cheaper over the life of the loan.

For example, a $2,000 loan with a 5% interest rate over 12 months is vastly different from a $2,000 loan with a 25% interest rate over 36 months, even if the monthly payments seem manageable in both scenarios. The latter will cost you thousands more in interest, effectively turning a small repair into a long-term financial burden.

Strategies for Rebuilding Credit While Managing Debt

Taking out a loan to cover a current need should not be a permanent setback. In fact, if managed correctly, it can be the catalyst for improving your financial profile. The goal is to use the liquidity to solve an immediate problem while simultaneously implementing habits that prevent the need for high-interest loans in the future.

Consider the following tactical steps to ensure your borrowing experience leads to growth:

  • Prioritize Credit Builder Products: If your goal is to fix your score, a specialized credit builder product like those offered by Texas Bay Credit Union is often a much smarter move than a standard installment loan. These products are designed to report positive payment history to the bureaus without requiring a large upfront sum.
  • Set Up Autopay: Late payments are one of the fastest ways to destroy a recovering credit score. Even a single 30-day late payment can drop your score significantly. Setting up automatic withdrawals ensures you never miss a due date, even during busy or stressful months.
  • Avoid “Credit Stacking”: It is tempting to take out multiple small loans to cover different expenses. This is a recipe for a debt spiral. Instead, look for a single consolidation option if possible, or prioritize the highest-interest debt first using the “Avalanche Method.”
  • Review Your Statements Monthly: Don’t wait for a collection agency to call. Regularly checking your bank statements and credit reports allows you to catch errors or unauthorized charges before they escalate into serious legal or financial issues.

Making the Right Choice for Your Wallet

The biggest mistake people make when seeking bad credit loans in Texas is rushing into the first offer they see. It is tempting to grab the quickest cash, but a high-interest loan can quickly become a mountain of debt. Always ask about the total cost of the loan, including all fees and the full APR. A lender who is transparent about these costs is a much safer bet than one who hides them in the fine print of a digital application.

You should also consider whether you need a general personal loan or a specific product like a credit builder loan. If your goal is to fix your score, a specialized credit builder product is often a much smarter move than a standard installment loan. Take a breath, compare the numbers, and choose the path that leads to growth, not a cycle of debt. Your financial future in Texas depends on the decisions you make during these critical moments of need.
Top 5 Lenders for Motorcycle Loans for Bad Credit in 2026

Motor cycle loans for bad credit

Top 5 Lenders for Motorcycle Loans for Bad Credit in 2026

Last updated: 2026-10-16

Trying to score a new bike when your credit score is in the gutter feels like hitting a brick wall. Many riders assume a bruised credit history means they are destined to ride a beat-up old machine forever. Perhaps you have a history of late payments or a high debt-to-income ratio. Maybe a recent bankruptcy is still haunting your reports. Regardless of the cause, being denied a loan when you have your heart set on a specific machine is incredibly discouraging.

The reality is that the lending world has shifted. The era of “one size fits all” banking is fading. It has been replaced by a fragmented market where specialized lenders find value in segments that traditional big-box banks often overlook. This list focuses on finding lenders who see the person behind the numbers. They offer pathways to ownership even when your financial past has been a bit bumpy or unpredictable. Whether you want a high-performance street bike or a reliable commuter, there is a financial lane carved out for you.

  1. Roadrunner Financial
  2. FastLendGo
  3. OneMain Financial
  4. SCU Credit Union
  5. Sound Credit Union

How We Evaluated These Lending Options

Evaluating lenders for bad credit requires a different lens than traditional prime lending. When you have a score above 740, lenders compete for your business with the lowest possible rates. When you are working with a score in the 500s or low 600s, the criteria shift. You stop asking “how much can they offer me?” and start asking “will they offer me anything at all?” We looked beyond just the lowest interest rates to see who actually provides accessibility for those with less-than-perfect scores.

It isn’t just about saying “yes.” We looked at how they say it, how they handle your data, and whether their terms are predatory or merely challenging. We prioritized speed and the ability to prequalify without hurting your score. We also looked at the breadth of vehicle types covered. A lender that only works with brand-new motorcycles isn’t helpful if you are hunting for a vintage cafe racer or a used dirt bike.

We also scrutinized the “hidden” costs. Items like origination fees or prepayment penalties can make a “cheap” monthly payment much more expensive in the long run. This is especially true if you plan to pay the loan off early once your credit improves. You don’t want to find out later that you’re locked into a high-cost contract just because the initial monthly payment looked low on the sticker.

Lender Name Loan Amounts Terms Funding Speed Credit Requirements
Roadrunner Financial See site See site Quick Process All credit welcome
FastLendGo $500 – $5,000+ See site Quick access Bad/Fair Credit
OneMain Financial $1,500 – $30,000 24 – 60 months As soon as 1 hour See site
SCU Credit Union See site 60-month options See site New & Used vehicles
Sound Credit Union See site See site See site RV, Boat & Motorcycle

1. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial acts as a bridge between riders and dealerships. They specialize in powersports financing, covering everything from ATVs and side-by-sides to dirtbikes and snowmobiles. It is a heavy hitter for anyone looking to secure a ride at a local dealership without the usual headache. Instead of you running from bank to bank, Roadrunner works with a network of dealers to streamline the approval process.

The standout feature here is the ability to check your rate in about two minutes. This process uses a “soft pull” mechanism. It doesn’t touch your credit score, so you can shop around without the fear of dropping your points further. This is a critical tool for anyone trying to gauge their purchasing power. For example, if you find a used Yamaha XT250 at a dealership, you can quickly see if Roadrunner can facilitate that specific purchase before you even drive to the lot.

Because they focus on the dealership model, they are highly integrated into the sales process. When you sit down with a salesperson, the financing is often already moving in the background. This makes the “buying experience” feel less like a negotiation and more like a transaction. This is especially helpful for those who find the high-pressure environment of a dealership intimidating.

Pros:

  • Prequalify with no impact on credit score
  • Covers a massive range of powersports including golf carts
  • Real-time decisions to save time at the dealership

Cons:

  • Primarily focuses on dealership-based financing rather than direct personal loans

2. FastLendGo

FastLendGo – fastlendgo.com

If you find yourself in a pinch and need cash to secure a deal, FastLendGo offers a direct path. They specialize in personal loans that cater specifically to those with bad or fair credit. Unlike traditional auto loans that are tied to a specific VIN, a personal loan from FastLendGo gives you the cash to buy a bike from a private seller on Craigslist or Facebook Marketplace. This is a common scenario for riders looking for deals on older, high-mileage bikes.

This lender is particularly useful for people who need quick access to cash for various needs, including motorcycle loans. They offer different tiers, from $500 up to $5,000 and beyond. This makes them a flexible partner for many different financial situations. For instance, if you need $2,000 to buy a used Honda Rebel from a private party, a traditional bank might refuse the loan because there is no collateral. FastLendGo’s unsecured personal loan model is designed for exactly this type of flexibility.

Pros:

  • Specialized options for bad and fair credit
  • Quickly compare local personal loan options
  • Flexible loan amounts starting at $500

Cons:

  • Interest rates for bad credit can be significantly higher than prime loans

3. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a massive player in the personal loan space, offering a structured approach to borrowing. They provide loans ranging from $1,500 up to $30,000, which covers the majority of used motorcycle price points. If you are looking to upgrade from a 250cc commuter to a mid-sized cruiser, OneMain’s loan ceiling is likely sufficient to cover the gap.

The speed of funding is impressive. You could have money available as soon as one hour after signing. This rapid turnaround is ideal for riders who have found a “unicorn” bike—a rare model that won’t be available by tomorrow. With fixed monthly payments and terms between 24 and 60 months, it provides a predictable way to manage your debt while you enjoy your new ride. You won’t have to worry about your payment amount changing halfway through the loan term.

Pros:

  • Very fast funding, potentially within one hour
  • Large loan amounts up to $30,000
  • Fixed monthly payments for easier budgeting

Cons:

  • Requires visiting a branch or interacting with their specific system

4. SCU Credit Union

SCU Credit Union – scucu.org

Credit unions often hold the secret sauce for better rates. Unlike commercial banks that answer to shareholders, credit unions are member-owned non-profits. SCU Credit Union offers financing for both new and used motorcycles, including popular brands like Honda and Harley-Davidson. They are a great option for those looking to consolidate existing debt while getting a bike. If you have several high-interest credit card balances, using a SCU loan to roll those into one lower-interest payment can be a powerful way to clean up your balance sheet.

Because they are a credit union, the focus is often on the member’s long-term financial health. They tend to look at the “whole person.” They might consider your steady employment history or your community ties rather than just a single numerical score. Whether you are looking for a 60-month term or looking to build your savings simultaneously, they offer a suite of services that go beyond just the loan itself. They are an excellent choice for the rider who plans on staying with the same institution for years to come.

Pros:

  • Financing available for new and used motorcycles
  • Options to consolidate debt
  • Expertise in various vehicle types

Cons:

  • Membership requirements may apply to certain credit union benefits

5. Sound Credit Union

Sound Credit Union – soundcu.org

Sound Credit Union serves a wide variety of needs, including specialized loans for RVs, boats, and motorcycles. They are a comprehensive institution that looks at your total financial picture. This makes them a “lifestyle” lender for those who don’t just want a motorcycle, but perhaps a trailer to haul it or a boat for the weekend.

For the rider who wants a relationship with their bank, Sound is a strong contender. They offer specialized motorcycle loans that can help you get on the road while maintaining a banking relationship for your future financial needs. This relationship can be invaluable. Once you have established a history of on-time payments with Sound, your next loan—perhaps for a car or a home down payment—may be much easier to secure.

Pros:

  • Specialized motorcycle and powersports loan focus
  • Full suite of banking services available
  • Comprehensive financial support

Cons:

  • Might require more paperwork compared to instant-decision online lenders

Preparation: Improving Your Chances Before You Apply

While the lenders listed above are willing to work with less-than-perfect credit, your chances of securing a lower interest rate increase significantly if you take proactive steps before hitting the “apply” button. Think of this as “pre-flighting” your financial situation.

First, pull your credit report from all three major bureaus (Equifax, Experian, and TransUnion) to ensure there are no errors. A single incorrect late payment reported by a previous landlord or a utility company can tank your score by 50 points. If you find errors, dispute them immediately. A “pending dispute” status can sometimes be taken into account by manual underwriters.

Second, prepare a “financial dossier.” When dealing with lenders like Sound or SCU Credit Union, being able to immediately provide two months of pay stubs, proof of residence, and a clear summary of your monthly expenses can set you apart. It demonstrates that you are a responsible, organized individual. This builds trust, which is the most important currency in the world of subprime lending.

Third, consider a co-signer. If you have a family member with strong credit who is willing to back you, this can be a game-changer. A co-signer essentially tells the lender, “If this rider fails to pay, I will.” This significantly lowers the lender’s risk. It can often move you from a “denied” status to an “approved” status with a much more manageable interest rate.

Navigating the Road Ahead

Before you sign on the dotted line, remember that a loan is a commitment. When dealing with bad credit, the interest rate is often the price you pay for the privilege of immediate ownership. It is vital to look at the total cost of the loan, not just the monthly payment. A $200 monthly payment might seem manageable, but if that payment is spread over 72 months at 18% interest, you will end up paying nearly double the actual value of the motorcycle.

Always ask for the “Truth in Lending” disclosure. This is a standardized document that lenders are legally required to provide. It breaks down the total amount you will pay over the life of the loan, including all interest and fees. If a lender is hesitant to provide this or tries to hide the total cost in fine print, walk away immediately.

Avoid the mistake of rushing into a deal just because a dealer is pushing you to sign. High-pressure sales tactics are common in powersports, especially when they know your credit is a weak point. They may try to offer you a “no money down” deal that looks attractive, but it carries an astronomical interest rate that keeps you in debt for years. Take a moment to compare the offers you received during the prequalification stage. A little bit of patience now can save you thousands of dollars in interest. Your goal shouldn’t just be to get a bike; it should be to get a bike and remain financially free while riding it.

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Car repair loans for bad credit

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Last updated: 2026-10-16

Walking into a mechanic’s shop only to find out your transmission needs a complete overhaul is a gut punch. When the repair bill looks more like a mortgage payment, the stress can feel overwhelming. For many drivers, a sudden mechanical failure is a crisis that demands immediate cash to keep life moving.

A failed alternator might cost $400, but a transmission swap or an engine replacement can easily soar into the $3,000 to $5,000 range. This creates an immediate liquidity gap that most monthly budgets cannot absorb without planning. It is a sudden, sharp financial blow that catches most people off guard.

Finding a lender that accepts less-than-perfect credit scores is the primary goal for most people in this situation. When your credit score has been impacted by medical bills, student loans, or previous missed payments, traditional banking institutions often become inaccessible. You find yourself staring at a locked door when you need a way out.

This ranking focuses on speed, accessibility, and the reality of borrowing when your credit history isn’t your strongest asset. It is about getting back on the road without sinking further into a financial hole. We looked at how these lenders actually function when you are in a pinch.

  1. Manhattan Bank
  2. FastLendGo
  3. Addition Fi
  4. Minute Loan Center
  5. CreditNinja

How We Evaluated These Repair Financing Options

The selection process prioritized lenders that cater specifically to those facing unexpected automotive expenses. We looked for providers that offer quick turnaround times, which is critical when you need your vehicle for work or family obligations. Speed is often the difference between getting to a job and losing a paycheck.

If you are a delivery driver or a commuter with a long distance to travel, a three-day waiting period for funds might mean losing several shifts of income. This effectively increases the “true cost” of the loan. You aren’t just paying interest; you are paying for the time you spent without a car.

We also examined the breadth of loan products offered by each entity. A lender that provides various amounts, from small emergency sums to larger amounts, offers more flexibility for different repair scenarios. A simple brake pad replacement might only require a $300 quick loan.

Conversely, a blown head gasket might require $2,500. We looked for lenders that don’t force you into a massive loan if you only need a small fix, and those that can scale up for major structural repairs. The following comparison highlights the key features available for each provider based on their current service offerings.

Lender Name Loan Amounts Funding Speed Credit Requirements
Manhattan Bank See site See site See site
FastLendGo $500 – $5,000 See site Bad/Fair Credit
Addition Fi Up to $5,000 See site See site
Minute Loan Center See site Same-day Fair Credit
CreditNinja See site Same day* Bad Credit

The Best Lenders for Automotive Repairs

1. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank operates as a traditional banking institution with the security of FDIC insurance. This provides a level of peace of mind that many specialized online lenders simply cannot match. For those who prefer working with a formal bank structure, this is a solid option for various personal loan needs.

Because they are a full-service bank, they offer a more structured approach to borrowing. While this might mean a slightly more thorough vetting process—often involving a review of your debt-to-income ratio and employment history—the stability of an FDIC-insured institution is a massive advantage for long-term financial health.

When applying with a traditional bank, you are typically looking for a “Personal Loan,” which is unsecured. This means you don’t have to put your vehicle up as collateral, which is a significant relief if you are already struggling with car-related expenses. You can keep your title in your hand.

However, because they prioritize stability, they may require a more established banking history or a steady stream of documented income via pay stubs or W-2s. They want to see that your income is as reliable as their vaults.

Pros:
  • FDIC-insured security
  • Established banking reputation
  • Offers personal loans for many occasions
Cons:
  • May have more rigorous application requirements than quick-cash lenders

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo specializes in being a partner for those who might struggle with traditional bank requirements. They offer a wide range of specialized products, including specific options for auto repair loans and even motorcycle loans. This makes them a versatile choice for various mechanical emergencies.

Instead of trying to fit a square peg into a round hole with a general-purpose loan, FastLendGo‘s specialized products are tailored to the reality of automotive ownership. They understand that a car isn’t just a luxury; it is often a tool for survival.

With loan amounts ranging from $500 up to $5,000, they cater to both small fixes and larger, more significant engine repairs. This range is particularly useful for tiered repair needs. You can address the immediate crisis without over-borrowing.

For instance, if your mechanic says, “You need a new fuel pump now, but you can wait six months on the suspension,” FastLendGo allows you to borrow exactly what is needed for the immediate crisis. Their focus on high-speed access makes them a strong contender for anyone in a time-sensitive situation.

Pros:
  • Specific auto repair loan options
  • Flexible loan amounts from $500 to $5,000
  • Designed for bad and fair credit
Cons:
  • Limited to specific states

3. Addition Fi

Addition Fi – additionfi.com

Addition Financial Credit Union offers a membership-based approach to personal banking. For those looking to build a long-term relationship with a financial institution, this is a standout choice. Credit unions are member-owned cooperatives, which often means they operate with a different philosophy than for-profit banks.

Their primary goal is to serve their members, which can translate to more personalized service and competitive terms. It feels less like a cold transaction and more like a community resource. They aren’t just looking at numbers on a screen; they are looking at people.

They offer competitive rates and a variety of loan products. While they are a broader credit union, their ability to help members “borrow smarter” makes them a reliable option for those who want to manage their debt responsibly while fixing their vehicle.

Because credit unions often have slightly more flexible underwriting criteria than large national banks, they may be more willing to look at the “why” behind a low credit score—such as a past medical emergency—rather than just the score itself. They see the human story behind the data.

Pros:
  • Credit union membership benefits
  • Competitive rates for members
  • Diverse range of financial products
Cons:
  • Requires membership to access full benefits

4. Minute Loan Center

Minute Loan Center – minuteloancenter.com

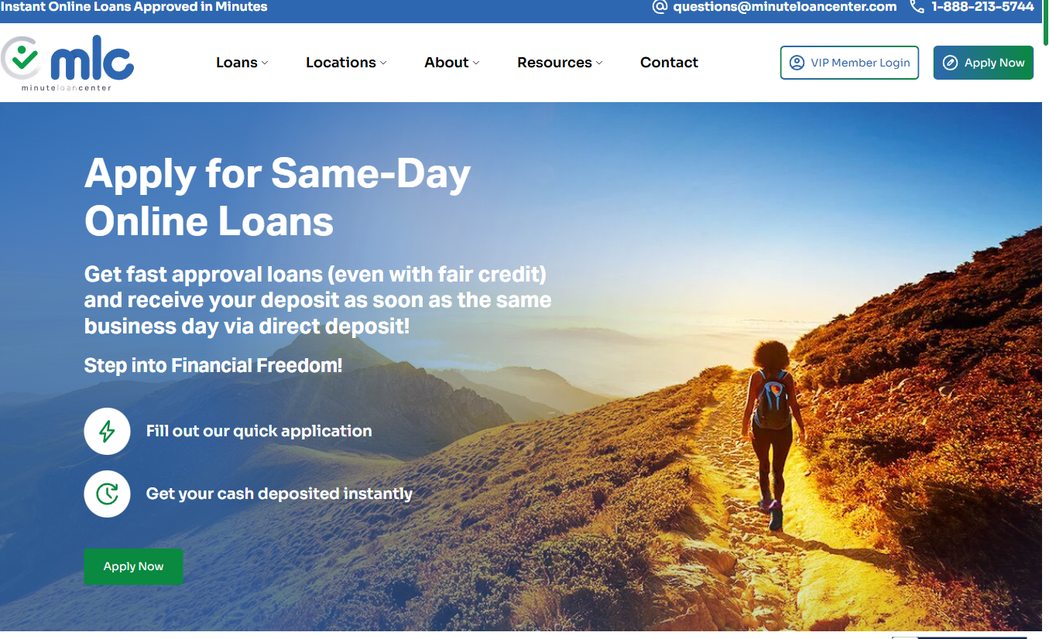
When the car is stuck in the shop and the clock is ticking, Minute Loan Center offers a rapid response. They focus heavily on the speed of the application and the immediacy of the funds. Their model is built for people who need cash to be deposited as soon as the same business day.

This is a vital feature for those living paycheck to paycheck, where a three-day delay in funds could mean a late fee on rent or a missed utility payment. In these moments, every hour feels like a lifetime. They aim to cut that waiting time down to almost nothing.

The platform is designed to be straightforward, aiming to help users step into financial freedom through quick approvals. The digital-first approach means you can often complete the entire process from your smartphone while waiting in the mechanic’s lobby.

This is ideal for the driver who cannot afford to miss a day of work because their vehicle is sidelined and they need to authorize the repair immediately to get it back on the road. They prioritize getting you back to work, which keeps your income flowing.

Pros:
  • Same-day deposit potential
  • Fast approval process
  • User-friendly online application
Cons:
  • Approval is dependent on fair credit status

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja acts as a bridge for those who find themselves unable to get approved by traditional lenders. Their system is designed to match users with loan options that fit their specific credit profile. It is a way to stop guessing and start knowing.

Rather than you spending hours applying to ten different lenders only to get ten rejections, CreditNinja uses a matching algorithm to point you toward the lenders most likely to approve your specific situation. It is a streamlined way to find a solution when other doors have closed.

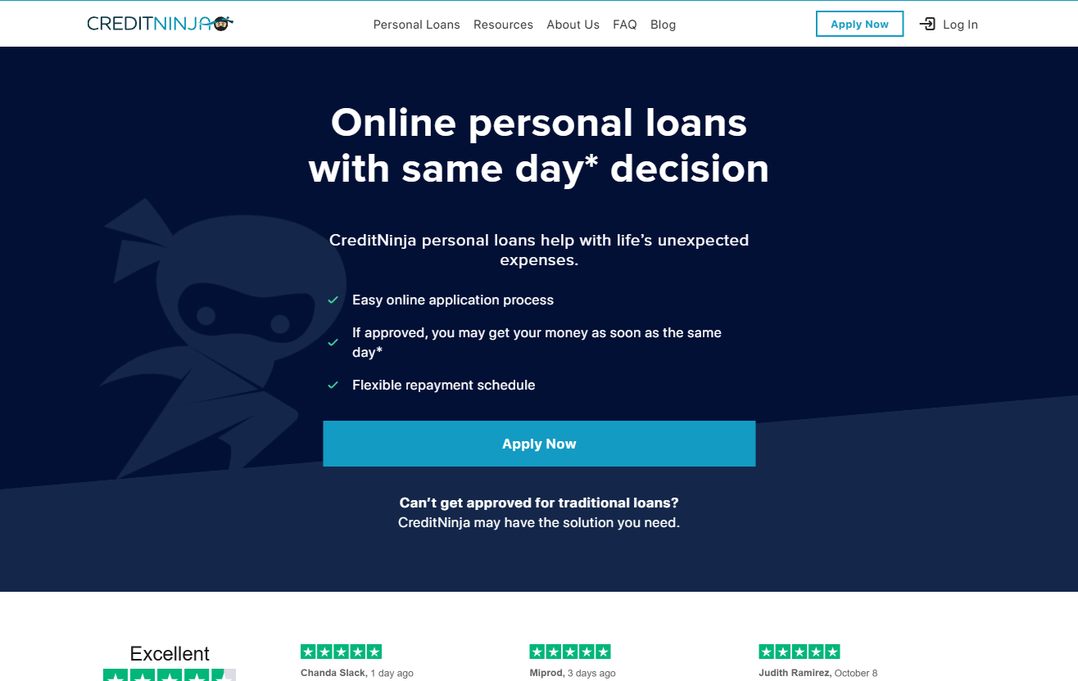
The process is quick and simple, focusing on providing a fast decision. If you are in a pinch and need to know where you stand without a long, drawn-out waiting period, this is an efficient way to explore your options.

It acts as a powerful reconnaissance tool for anyone who is unsure of their eligibility in a high-pressure environment. It helps you narrow your search so you aren’t wasting energy on lenders that will simply say no.

Pros:
  • Same-day decision potential
  • Quick and simple online application
  • Targets those with bad credit
Cons:
  • Does not guarantee approval

Understanding the Total Cost of Borrowing

When you are in an emergency, it is easy to focus solely on the monthly payment, but this can be a dangerous trap. To truly understand your financial obligation, you must look at the Annual Percentage Rate (APR). This includes both the interest rate and any mandatory fees.

A loan with a “low” monthly payment might actually be more expensive over the long term if the interest rate is significantly higher than a standard bank loan. Don’t let a small number hide a large debt. Look at the grand total you will pay back by the end of the term.

Consider these three factors when reviewing a loan offer:

  • The Repayment Term: A 24-month loan will have much lower monthly payments than a 12-month loan, but you will pay significantly more in total interest over that extended period.
  • Origination Fees: Some lenders deduct a fee from the loan amount before you even receive it. If you need exactly $1,200 for a repair but the lender charges a $100 origination fee, you will only receive $1,100, leaving you short at the mechanic.
  • Prepayment Penalties: If you receive a bonus at work or a tax refund and want to pay off the car loan early to save on interest, some lenders charge a fee for doing so. Always check if “prepayment is without penalty.”

Smart Steps to Prepare for Your Loan Application

Securing a loan under pressure is difficult, but being prepared can increase your chances of approval and better terms. Even if you are applying for a high-speed loan, having your documentation ready can prevent delays that could leave you stranded without transport.

Follow these steps to streamline the process:

  1. Gather Documents: Have your most recent pay stubs, a government-issued ID, and your bank account details (for direct deposit) ready. If you are self-employed, have your last two years of tax returns on hand.
  2. Get a Written Estimate: Do not guess the amount you need. Ask your mechanic for a detailed, written estimate that includes parts and labor. Borrowing too little leads to more debt later; borrowing too much leads to unnecessary interest.
  3. Check Your Own Credit: While you may have bad credit, knowing your score helps you understand which lenders (like CreditNinja or FastLendGo) are your most viable targets.
  4. Verify Your Income: Lenders want to see that you have the ability to repay. Even if your credit is poor, a stable, documented income is your strongest asset during the underwriting process.

Navigating your borrowing options requires a balance of urgency and caution. Before signing any paperwork, it is vital to look at the total cost of the loan. Interest rates can vary wildly between a traditional bank and a specialized lender. Always ask for the total amount you will be paying back over the life of the loan, not just the monthly payment.

Another common pitfall is rushing into a high-interest loan just to solve an immediate problem. While speed is important, an expensive loan today can become a heavy burden tomorrow. Compare your options carefully and ensure the repayment schedule fits comfortably within your monthly budget.

If a monthly payment would mean you can’t afford groceries or gas, the loan is too large or the term is too long. You shouldn’t have to choose between fixing your car and feeding your family. Take a breath and look at the math one more time.

Finally, read the fine print regarding any fees. Some lenders charge origination fees or prepayment penalties that can catch you off guard. Taking ten minutes to read the terms can save you hundreds of dollars in the long run, ensuring your car repair doesn’t lead to a financial disaster. Your goal is to get back on the road, not to remain stuck in a cycle of high-interest debt.

Top 5 Lenders for Same Day Personal Loans in 2026

Same day personal loans

Top 5 Lenders for Same Day Personal Loans in 2026

Last updated: 2026-10-16

Life rarely waits for a convenient time to throw a curveball. Whether it is an unexpected car repair that leaves you stranded, an urgent medical bill, or a leaking roof that needs immediate attention, finding quick cash can feel like chasing a ghost in a crowded room. In these high-stress moments, the mental bandwidth required to handle complex financial systems often vanishes first.

This is why many people turn to same-day personal loans to bridge the gap between a sudden crisis and their next paycheck. Choosing a lender is about more than just who moves the fastest. If you prioritize speed above all else, you might find yourself trapped in a high-interest cycle that takes years to escape.

It is about finding a balance between speed, cost, and the long-term impact on your financial reputation. This ranking looks at the most reliable options currently available to help you handle these high-pressure moments without making a mess of your future. We have analyzed the top players in the market for 2026.

  1. JetzLoan
  2. Avant
  3. SoFi
  4. Discover
  5. CreditNinja

How the Top Lenders Were Evaluated

The selection process focused heavily on how fast money hits your account and how easy the application feels. Nobody wants to spend hours filling out paperwork or waiting on hold with a representative only to wait a week for a decision. We looked for lenders that offer digital-first experiences and rapid deposit timelines using modern banking technology.

Beyond speed, we looked at accessibility and transparency. We prioritized lenders that provide clear information regarding credit impacts and loan amounts. It is vital to know if a hard credit pull is required before you start clicking buttons, as this can affect your ability to secure a mortgage or an auto loan later.

A “soft pull” allows you to shop around for the best interest rate without a penalty. This is a critical distinction for anyone trying to maintain a healthy credit profile while seeking emergency funds. We also evaluated the friction within the application journey, such as whether a lender uses automated systems like Plaid to verify income instantly or requires manual pay stubs.

The goal was to identify lenders that respect your time as much as your money. We wanted to see who makes the process painless and who leaves you scrambling for documentation. The following table summarizes our findings across the top five candidates.

Lender Loan Amount Range Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Avant $2,000 – $35,000 Fast decision See site
SoFi See site See site See site
Discover $2,500 – $40,000 As early as next business day No impact to credit score for pre-approval
CreditNinja See site As soon as the same day See site

Ranking of Best Lenders

1. JetzLoan

JetzLoan – jetzloan.com

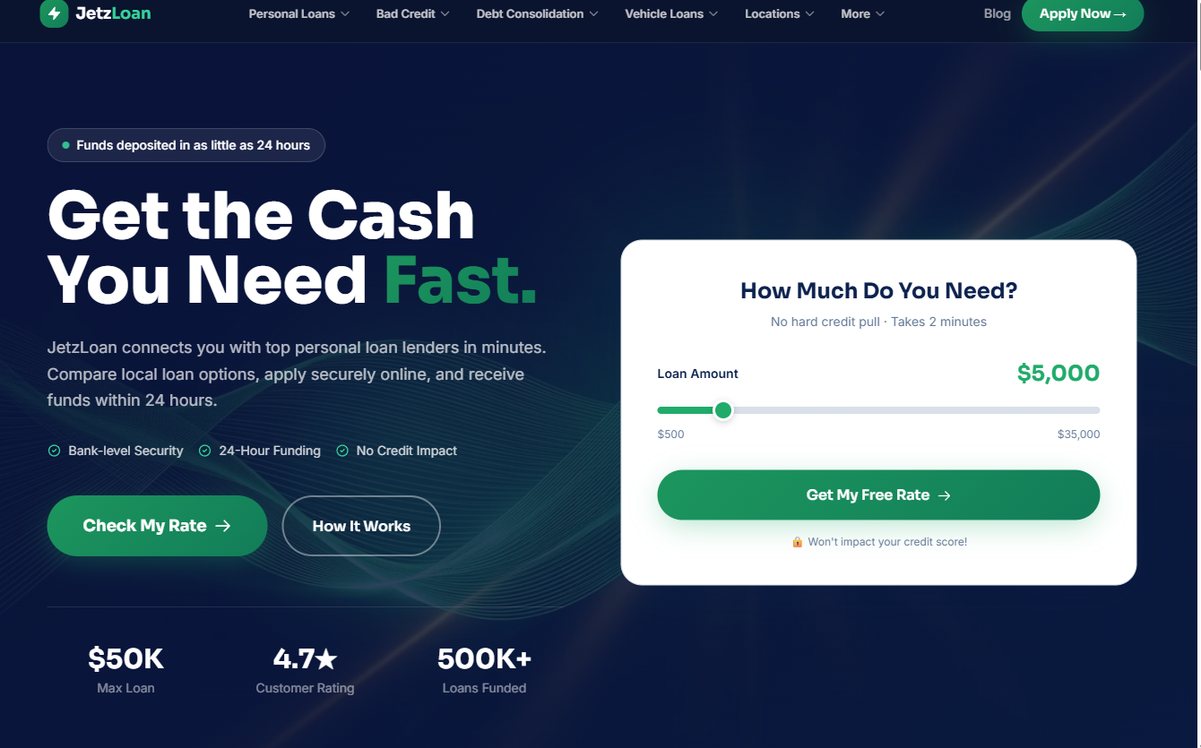
JetzLoan connects borrowers with various top lenders in a matter of minutes. Rather than being a single bank, it functions as a marketplace. This is a significant advantage because it saves you the time of visiting ten different websites to see who will give you the best rate. Instead, you enter your data once, and the platform does the heavy lifting.

The process is remarkably streamlined, requiring less than two minutes to complete the initial form. This makes it a standout for anyone who needs to move quickly without a heavy administrative burden. For example, if you are at a mechanic’s shop and need to pay for a repair immediately to get your car back, the speed of JetzLoan is designed for that exact scenario.

The platform is built for those who might be nervous about their credit standing. Because they offer a way to check rates without a hard credit pull, you can explore your options without any fear of damaging your score. It is a low-pressure way to find significant funding without the “sticker shock” of seeing a credit score drop before you even know if you qualify.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull required for the initial rate check.
  • High customer rating of 4.7 stars.

Cons:

  • Acts as a marketplace rather than a direct lender.

2. Avant

Avant – avant.com

Avant focuses on providing flexible tools for people who are navigating complex financial journeys. They understand that “one size fits all” rarely works in lending. They offer solutions for various needs, including debt consolidation, emergency expenses, and home improvements. This versatility is helpful for someone trying to solve two problems at once.

You might find yourself needing to pay off a high-interest medical bill and a predatory payday loan in a single lump sum. Their application process is simple, utilizing a three-step method to get you from start to finish. This is ideal for someone who needs a quick decision to handle an unexpected life event.

They aim to provide clarity when you might be facing difficult financial questions. They often provide clear terms upfront so there is no confusion about what your monthly payment will look like. This transparency helps prevent any nasty surprises when the first bill arrives in your inbox.

Pros:

  • Simple, three-step application process.
  • Options for debt consolidation and emergency loans.
  • Flexible solutions for different financial goals.

Cons:

  • Specific eligibility requirements are not always immediately transparent.

3. SoFi

SoFi – sofi.com

SoFi is a massive player in the financial ecosystem, offering everything from banking and checking to investing and mortgages. For those who want a one-stop shop for their entire financial life, this is a powerhouse. They cater to a wide range of needs through digital, automated processes that feel much more like a modern tech app than a traditional bank.

While they are known for more traditional long-term financial products, their digital-first approach allows for much faster movement than old-school banks. They are a great option for borrowers who value a high-tech, integrated experience across all their various money management needs. If you already have a high credit score, SoFi is often the gold standard.

They offer premium rates with zero paperwork for those who qualify. The experience is incredibly fluid, making it easy to manage your finances from your phone. It is a sophisticated option for users who want their lending to match their digital lifestyle.

Pros:

  • Comprehensive financial suite including investing and banking.
  • Highly digital and automated application process.
  • Reputable brand with extensive financial tools.

Cons:

  • May require higher credit standards for the best terms.

4. Discover

Discover – discover.com

Discover brings a sense of traditional stability to the online lending world. They offer a wide range of products, including credit cards and personal loans, with a focus on customer service and security. It is a solid choice for someone who wants a well-established name behind their loan.

You might want to know that if you have a question, there is a massive infrastructure of customer support ready to assist them. The platform is particularly useful for those who want to “check before they commit.” You can see if you are pre-approved for certain products with no impact to your credit score.

This allows for a cautious approach to borrowing in an uncertain economic climate. It is a “try before you buy” model that removes the anxiety of the unknown. If you prefer a lender that feels like a pillar of the industry, Discover is a reliable bet.

Pros:

  • Pre-approval checks do not impact credit scores.
  • Wide range of loan amounts available.
  • Highly rated customer service and security.

Cons:

  • Funding may take until the next business day rather than the same day.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is a go-to option for those who might find traditional banks a bit too stingy. They specialize in helping people who may not qualify for standard loans, offering a path to finding solutions for unexpected life expenses. Their application is designed to be quick and simple, focusing on your specific profile.

The standout feature here is the potential for same-day money. If you are approved and sign for your loan, the funds may be deposited directly into your account as early as the same day. This is a lifesaver when a deadline is looming, such as an eviction notice or a utility shut-off warning.

It is designed for high-stakes situations where every hour counts. While you might pay more for this speed, the ability to resolve a crisis immediately is worth a lot to many people. It is a specialized tool for those in urgent need.

Pros:

  • Potential for same-day funding upon signing.
  • Designed for those who struggle with traditional loan approvals.
  • Quick and easy online application process.

Cons:

  • Interest rates can be higher for those with less ideal credit.

The Step-by-Step Process of Securing a Quick Loan

To ensure you get the best possible outcome, you should approach the application process with a specific workflow. Following these steps can prevent common delays that turn a “same-day” loan into a “three-day” headache.

Step 1: Gather Your Documentation in Advance. Even with automated systems, you will likely need to provide your Social Security Number, your monthly gross income, and your primary banking details. Having a digital copy of your most recent pay stub or a bank statement ready to upload can prevent the application from stalling in the “pending verification” stage.

Step 2: Use a Soft Credit Pull First. Always look for the “check your rate” option. This allows you to see the estimated APR and monthly payment without any risk to your credit score. If the rate is significantly higher than you can afford, you can walk away without any lasting financial damage.

Step 3: Compare the APR, Not Just the Monthly Payment. This is where many borrowers make a mistake. A lender might offer a very low monthly payment, but if that is because they have stretched the loan term out to five years, you will end up paying thousands more in interest. Always look at the total cost of the loan over its entire lifespan.

Step 4: Verify the Funding Method. If you need money today, ensure you have a checking account that supports “Real-Time Payments” or “Instant ACH.” Some lenders can send money instantly, but if your bank only processes transfers overnight, you won’t see that cash until the next business morning regardless of how fast the lender acts.

Avoiding Common Pitfalls When Borrowing

The first mistake many people make is rushing into the first offer they see without looking at the fine print. While speed is the primary goal, the cost of that speed can be high. Always check the total cost of the loan to ensure it is manageable. Specifically, look for “origination fees.”

If you borrow $1,000 but the lender takes a $50 origination fee, you only receive $950, but you still owe interest on the full $1,000. Another trap is forgetting to compare different types of credit. Sometimes, a credit card with a low interest rate might actually be cheaper than a quick personal loan for a small amount of money.

Take a moment to breathe and evaluate your total debt-to-income ratio before signing. If your monthly debt payments already consume a large portion of your income, adding another loan could lead to a cycle of borrowing just to pay off previous debts. Avoid the temptation to borrow more than you absolutely need.

Every dollar borrowed is a dollar that must be repaid with interest. Use these tools as a bridge to get you from one stable point to another, not as a permanent lifestyle adjustment. A loan should be a tool for resolution, not a source of new, ongoing stress.

Top 6 Lenders for Christmas Loans for Bad Credit in 2026

Christmas loans for bad credit

Top 6 Lenders for Christmas Loans for Bad Credit in 2026

Last updated: 2026-10-16

The holiday season usually brings a bit of magic, but for many families, those festive lights feel a little dim when the mounting expenses start piling up. Between buying gifts for the kids and hosting those obligatory dinners, bank accounts often look pretty thin by mid-December. Trying to bridge that gap without falling into a debt trap is a delicate balancing act.

When you need a quick injection of cash, your biggest worry is usually how a lender will view a less-than-perfect credit history. It isn’t just about finding the money. It is about finding a partner that won’t penalize you for past financial hiccups. Speed, transparency, and the actual cost of borrowing are the three things that matter most for a smart holiday loan.

  1. Wells Fargo
  2. FastLendGo
  3. LendingPoint
  4. VivaLoan
  5. NetCredit
  6. Prosper

How These Holiday Lenders Were Evaluated

Our selection process focused heavily on how fast a borrower can move from an application to having cash in hand. In the middle of the Christmas rush, waiting two weeks for a decision is simply not an option. We looked at how lenders handle diverse credit profiles, including those with bruised scores or high incomes but very limited history.

We also looked at whether loan amounts were flexible and if the terms were clear. It is vital to know exactly how much you can borrow for a specific need, whether it is a $500 emergency or a $10,000 debt consolidation. Only lenders with clear, accessible information regarding their requirements and funding speeds made the final cut for this 2026 roundup.

Lender Name Loan Amounts Funding Speed Credit Requirements
Wells Fargo See site See site See site
FastLendGo $500 – $5,000+ Quick access Bad credit options
LendingPoint $1,000 – $36,500 See site Check rate (no impact)
VivaLoan $100 – $15,000 As soon as tomorrow All credit types
NetCredit Up to $10,000 Same-day funding available See site
Prosper $2,000 – $50,000 Fast access See site

The Definitive 2026 Holiday Loan Rankings

1. Wells Fargo

Wells Fargo – wellsfargo.com

Established financial institutions often provide a sense of stability that newer fintech companies lack. For those looking to manage their finances through traditional banking channels, this option offers a wide range of services, including checking and savings accounts. It is a massive ecosystem built to handle everything from simple daily transactions to complex wealth management needs.

This lender works well for individuals who prefer a traditional banking relationship. You might benefit from additional services like credit cards or home loans here. While it is a powerhouse in the financial sector, the complexity of their product line means you have to look through various offerings to find the specific personal loan that fits your current holiday budget.

Pros:
  • Extensive range of banking services
  • Established and trusted institution
  • Offers specialized accounts like Clear Access Banking
Cons:
  • Complex product ecosystem can be overwhelming

2. FastLendGo

FastLendGo – fastlendgo.com

When the holiday season hits a fever pitch, sometimes you just need a quick fix. This lender specializes in providing various personal financing solutions tailored to different life scenarios. Whether it is for auto repairs or a sudden dental bill, they offer a variety of loan sizes to match the specific emergency at hand. (fastlendgo.com)

They cater to a wide spectrum of borrowers, including those with bad credit or even those seeking first-time loans. It is a versatile option for those tired of the “one size fits all” approach used by big banks. If you are looking for something specific like a $500 or $1,000 loan, this could be a lifeline.

Pros:
  • Specialized loans for specific needs (Auto, Dental, Roof)
  • Covers a wide range of credit scores
  • Simple online application process
Cons:
  • Focuses on niche loan types rather than general banking

3. LendingPoint

LendingPoint – lendingpoint.com

For those who need a more substantial amount of capital to tackle larger holiday debts or home improvements, this lender steps up. They offer significant loan amounts that can help turn financial stress into a manageable plan. It is an excellent choice for anyone looking to consolidate debt or cover an unexpected large expense.

A standout feature here is the ability to check your rate without impacting your credit score. This allows for a “no-risk” exploration of your options before you commit to a formal application. It is a thoughtful approach for people who are cautious about their credit standing during a high-stress season.

Pros:
  • High loan limits up to $36,500
  • Check rates without credit score impact
  • Versatile loan purposes
Cons:
  • May require higher income to secure larger amounts

4. VivaLoan

VivaLoan – vivaloan.com

Speed is the name of the game when the holiday bills start piling up on the kitchen table. This lender is designed for the person who needs cash essentially yesterday. With the ability to get funds as soon as the next business day, they remove the long waiting periods that often plague traditional lending.

They are incredibly inclusive, welcoming all credit types into their application process. The ability to request small amounts, starting as low as $100, makes them highly accessible for minor holiday emergencies. It is a streamlined, five-minute request process that prioritizes your time and immediate needs.

Pros:
  • Extremely fast funding (as soon as tomorrow)
  • Low entry point starting at $100
  • Welcomes all credit types
Cons:
  • Rapid funding often comes with higher interest rates

5. NetCredit

NetCredit – netcredit.com

This lender operates on the philosophy that a person is much more than just a single number in a database. By using advanced algorithms, they look beyond the basic credit score to find a more holistic view of the borrower. This approach is refreshing for those who have been denied by more rigid institutions.

They offer a flexible range of products including personal loans and lines of credit with amounts up to $10,000. The availability of same-day funding is a massive advantage when you are facing a deadline. It is a modern, tech-forward solution for the contemporary borrower.

Pros:
  • Holistic underwriting approach
  • Same-day funding availability
  • Flexible lines of credit available
Cons:
  • Approval is subject to state-specific underwriting partners

6. Prosper

Prosper – prosper.com

Prosper offers a different flavor of lending through its connection to the peer-to-peer model. This can sometimes lead to more competitive options for those who qualify. They provide a variety of tools, including credit cards and investment options, making them a comprehensive platform for those looking to manage long-term financial health.

With loan terms reaching up to six years, it is a solid choice for those who want to spread out their repayments over a longer period. This can lower the monthly impact on your budget, which is vital when you are already juggling many holiday expenses. It is a strategic choice for the long-term planner.

Pros:
  • Longer repayment terms up to 6 years
  • Peer-to-peer model offers variety
  • Highly rated by financial experts
Cons:
  • Minimum loan amounts may be higher than micro-lenders

Avoiding the Holiday Debt Trap

Borrowing money during the holidays can feel like walking a tightrope. It is easy to get swept up in the excitement of the season and forget that every dollar borrowed today is a dollar that must be paid back with interest tomorrow. Before you sign any agreement, take a deep breath and look at the total cost of the loan.

One major mistake is ignoring the fine print regarding late fees and prepayment penalties. You want to be able to pay the loan off early if you find yourself with extra cash in January, but some lenders will penalize you for being responsible. Always ensure that the repayment schedule fits comfortably within your budget for the first three months of the new year.

Another pitfall is the “quick fix” mentality. While a small loan might solve a problem today, it doesn’t address the underlying habit that led to the shortage. Use this holiday cash as a bridge, not a permanent lifestyle adjustment. If you use these funds to create memories rather than just covering old debt, you might find the holiday spirit much more fulfilling.

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Emergency loans for bad credit

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Last updated: 2026-10-16

Life has a way of throwing a wrench into even the best-laid plans. A sudden transmission failure leaves you stranded on the highway, an urgent root canal brings an unexpected dental bill, or an HVAC breakdown strikes during a heatwave. In those moments, the need for immediate cash feels overwhelming. When your credit score isn’t exactly a glowing endorsement—maybe due to past medical debt or a period of unemployment—finding a lender feels like searching for a needle in a haystack.

This ranking focuses on speed, accessibility, and transparency for people facing urgent financial hurdles. Finding a lender that accepts less-than-perfect credit is only half the battle. The real challenge is ensuring the terms are manageable and the funds arrive before the crisis peaks. We analyzed several providers to see who stands out in this high-stakes market, looking at everything from digital application friction to the actual speed of capital deployment.

  1. Minute Loan Center
  2. FastLendGo
  3. Avant
  4. World Finance
  5. CreditNinja
  6. Reprise

How These Emergency Lenders Were Evaluated

Selecting the right lender requires looking past the flashy advertisements and marketing slogans. The evaluation process focused on how quickly funds could actually reach a borrower’s bank account after approval. In a true emergency, a three-day waiting period is often the difference between a solved problem and a mounting disaster. If you need to pay a mechanic to get to work on Monday morning, a lender that promises funds by Thursday is effectively useless. Speed is the primary metric of value here.

Beyond speed, the criteria included the ease of the application process and the variety of credit profiles accepted. A lender that requires a mountain of paperwork, physical visits to a branch, or multiple days of manual verification might be too slow for a midnight crisis. We also looked for providers that offer clear pathways for those with bad credit, ensuring no hidden surprises lurk in the fine print, such as predatory prepayment penalties or excessive origination fees that balloon the total cost of borrowing.

Lender Name Speed of Funding Max Loan Amount Credit Requirements
Minute Loan Center Same-Day See site Fair credit accepted
FastLendGo See site $5,000 Bad/Fair/Good
Avant See site See site Less than perfect credit
World Finance See site See site See site
CreditNinja Same-Day (with conditions) See site Bad credit okay
Reprise See site See site See site

Ranked Emergency Loan Providers

1. Minute Loan Center

Minute Loan Center – minuteloancenter.com

When the clock is ticking, Minute Loan Center steps into the ring with a focus on velocity. They specialize in same-day and instant online loans, aiming to get deposits into your account via direct deposit as soon as the business day begins. This makes them a heavy hitter for anyone staring down a deadline, such as a utility shut-off notice or a rent payment that is due by the end of the business day.

They cater specifically to those who might struggle with traditional bank requirements, offering approval even for those with fair credit. Because they have been around for over two decades, they have established a reputation for stability. In an era of fly-by-night fintech startups, having a provider that has weathered multiple economic cycles provides an extra layer of peace of mind. It is a solid choice for quick, digital-first relief when you cannot afford to wait for a manual underwriting process.

Pros:

  • Very fast same-day direct deposit.
  • No hidden fees or credit pulls mentioned.
  • Experienced provider with decades of service.

Cons:

  • Primarily focuses on a specific niche of rapid funding.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, ranging from small $500 loans to larger $5,000 requests. They seem to understand that a car repair requires a different approach than a roof repair. For instance, if you need a small amount to cover a tire replacement, a large installment loan might be overkill. Conversely, if you are facing a major home repair, a tiny microloan won’t cut it.

Their platform is designed to help users compare local options quickly to find that middle ground. (fastlendgo.com) The service is built for those who need to skip the long lines and the endless wait times associated with brick-and-mortar lenders. Whether you have bad credit or are just starting your journey with no credit history, they offer a path forward. It is a flexible option for those who need specific amounts for specific crises, allowing for a tailored approach to borrowing that matches the scale of the emergency at hand.

Pros:

  • Wide range of loan amounts from $500 to $5,000.
  • Covers various needs like auto or dental financing.
  • User-friendly comparison interface.

Cons:

  • The comparison model may lead to multiple offers.

3. Avant

Avant – avant.com

Avant approaches personal finance with a focus on long-term movement rather than just quick fixes. While they handle emergency loans, they also offer tools for debt consolidation and credit cards. This makes them a useful option if your emergency is actually part of a larger financial puzzle. For example, if you are taking a loan to cover a medical bill, Avant might also help you restructure your existing high-interest credit card debt to make your monthly budget more sustainable in the long run.

They are particularly welcoming to those with less than perfect credit, providing a bridge to help you move financially forward. Instead of just handing over cash, they aim to provide solutions that fit into your specific life journey. It is a more holistic approach to borrowing that prioritizes the borrower’s future stability rather than just the immediate transaction. It is ideal for the borrower who wants to solve a current crisis while simultaneously improving their credit standing.

Pros:

  • Supports debt consolidation alongside emergency needs.
  • Tailored solutions for different financial stages.
  • Strong focus on moving a borrower forward.

Cons:

  • May have stricter qualifying criteria than specialized lenders.

4. World Finance

World Finance – worldfinance.com

World Finance is a massive entity in the financial landscape, offering a broad spectrum of banking and investment services. While their focus often leans toward more complex financial structures, they maintain a presence in the retail banking space. This provides a level of professional scale that smaller, online-only lenders lack. For many, there is a psychological comfort in dealing with a large-scale institution rather than an unproven app.

For a borrower in a pinch, they represent a more institutional approach to money management. They are a significant player in the global and retail markets, making them a stable entity in the financial ecosystem. It is a choice for those who want a more traditional, large-scale provider and who may prefer the ability to engage with a provider that has a significant, established footprint in the financial sector.

Pros:

  • Highly established and large-scale institution.
  • Broad range of financial services available.
  • Deep expertise in various banking sectors.

Cons:

  • May feel less specialized for a quick, small-dollar emergency.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is built for the “life happens” moments when traditional banks turn you away. Their application process is designed to be quick and simple, requiring only basic information to see if you qualify. This “soft inquiry” style approach is designed to protect your credit score while you are just testing the waters. It is a streamlined approach for when you simply don’t have time to waste on lengthy applications that might lead to a rejection.

If you are approved, you can potentially see your money deposited the same day. However, there is a catch: you must apply and be approved by 10:30 a.m. on a business day to catch that same-day window. This requires a bit of proactive planning even in an emergency. If you wait until 4:00 p.m. to check your options, you might be looking at a delay that pushes your funds into the next business day, potentially missing your deadline.

Pros:

  • Extremely simple and fast online application.
  • Potentially very fast same-day funding.
  • Designed specifically for those denied by traditional banks.

Cons:

  • Strict morning deadline for same-day funding.

6. Reprise

Reprise – reprise.com

Reprise operates in a slightly different lane, functioning as an enterprise demo creation platform. While they offer sophisticated AI toolset and data injection for agents, they are not a traditional consumer lender for personal emergency cash. Their focus is on helping businesses build powerful product tours for their software or services.

They provide incredible capabilities for capturing screens and creating high-fidelity demos that look like real user sessions. If your “emergency” is actually a business need for high-end presentation tools to close a major sales deal, they are a powerhouse. However, for someone needing cash for a broken water heater or a car repair, they are not the right tool. It is important to ensure you are applying to a lender and not a business software provider.

Pros:

  • Advanced AI toolset for demo creation.
  • High-quality data injection for professional presentations.
  • Excellent for enterprise-level product tours.

Cons:

  • Not a consumer loan provider for personal emergencies.

Essential Steps for Securing an Emergency Loan

Navigating the world of rapid lending requires a strategic approach to ensure you don’t exacerbate your financial situation. Follow these steps to maximize your chances of success and minimize your long-term debt burden:

  1. Audit Your Need: Before applying, calculate the exact amount required. If a repair is estimated at $800, don’t borrow $1,200 just because the lender offers it. The interest on that extra $400 will compound quickly.
  2. Verify the “Total Cost of Credit”: Don’t just look at the monthly payment. Look at the total amount you will have paid back by the end of the term. A low monthly payment often means a much longer term and a significantly higher total cost.
  3. Check for Hidden Fees: Look specifically for “origination fees” (charged upfront), “processing fees,” and most importantly, “late payment fees.” In an emergency, your schedule might be chaotic; you need to know the penalty if a payment is a day late.
  4. Confirm the Funding Method: Not all “same-day” loans are created equal. Some require you to visit a physical location, while others use ACH transfers. For true speed, ensure the lender supports instant direct deposit to your existing checking account.

How to Navigate Emergency Borrowing

The most common mistake is rushing into the first offer you see without checking the details. Even in a panic, take a breath and look at the total cost of the loan. A quick fix can become a long-term headache if the interest rates are not clearly understood before you sign. Interest rates for high-speed, bad-credit loans are naturally higher than traditional personal loans, so the speed comes at a premium price.

Avoid the temptation to borrow more than you absolutely need to resolve the immediate crisis. It is easy to think, “If I’m borrowing, I might as well get extra,” but that extra cash comes with extra cost. Stay disciplined, compare the options, and choose the one that gets you through the storm without drowning you later. Use the emergency as a stepping stone to stability, not as a permanent fixture of your monthly budget.