(562) 400-4959 vsfoundation@outlook.com

The Top 7 Lawn Mower Financing Options for 2026
Lawn mower financing

The Top 7 Lawn Mower Financing Options for 2026

Last updated: 2026-10-16

Buying a new mower can feel like a mountain to climb. When a professional-grade zero-turn machine hits several thousand dollars, most people don’t just walk into a dealership and hand over a thick envelope of cash. They need a way to spread that cost over several months or even years.

Whether you are replacing an aging push mower with a high-end riding tractor or expanding a commercial landscaping fleet, the method of payment matters as much as the machine itself. You aren’t just buying iron and blades; you are managing a significant capital outlay.

Finding the right lender involves more than just looking at a monthly payment. You have to weigh interest rates against how a credit check might impact your score. You also need to consider how quickly the machine actually lands in your garage.

A high-interest loan might seem manageable today. However, when stretched over a 60-month term, the total cost of ownership can skyrocket. This list evaluates the most reliable paths to ownership, from manufacturer-direct deals to fast digital loans.

  1. Cub Cadet
  2. JetzLoan
  3. Gravely
  4. K and G Mowers
  5. Manhattan Bank
  6. Minute Loan Center
  7. Yanmar

How These Financing Providers Were Evaluated

The selection process focused on accessibility and the specific needs of different types of buyers. For a homeowner looking to upgrade their yard work, a low-interest manufacturer deal is often the golden ticket. These deals sometimes include promotional periods that allow you to pay off the equipment with zero interest, provided you stay current on all payments.

Commercial landscapers have different problems. If a machine breaks down in the middle of a busy season, they need cash by tomorrow morning, not next week. For them, a three-day approval process is essentially a three-day loss of revenue. They can’t afford to wait on a slow-moving bank while their crew sits idle.

We scrutinized each entry based on funding speed, credit requirement flexibility, and term transparency. We looked at whether a lender requires a hard credit pull and how much leeway they offer for those with less-than-perfect scores. This ensures a balanced view for everyone from the casual gardener to the fleet owner.

We also considered the “total cost of credit.” This includes not just the interest rate, but also potential origination fees, documentation costs, and prepayment penalties. You don’t want to be stuck in a loan that prevents you from paying it off early when you have extra cash.

Lender Name Max Loan Amount Funding Speed Credit Requirements Key Feature
Cub Cadet see site see site see site Manufacturer Financing
JetzLoan $35,000 24 Hours No Hard Credit Pull Fast Digital Funding
Gravely see site see site Subject to Credit Fleet Pricing Available
K and G Mowers see site see site No Credit Impact Prequal 0% APR for 48 Months
Manhattan Bank see site see site see site FDIC-Insured
Minute Loan Center see site Same Day Fair Credit Accepted Instant Online Approval
Yanmar see site see site see site Global Brand Support

Ranking of Top Mower Financing Options

1. Cub Cadet
Cub Cadet – cubcadet.com

Cub Cadet offers a direct route to high-end equipment like the Ultima Series zero-turn mowers. Their financing aims to get you from the showroom floor to your first pass in record time. It is a straightforward way to acquire premium machinery without a massive upfront hit to your savings.

Because they are the manufacturer, the financing is often integrated directly into the point of sale. You don’t have to deal with a third-party bank that doesn’t understand the specific value of the equipment you are buying. It keeps things simple and localized to the brand.

This option works well for the homeowner who knows exactly which model they want and wants to stay within the brand ecosystem. Whether you need a riding mower or a snow blower, the financing is tailored to the specific equipment you are eyeing. Many deals include “no money down” options, which is ideal for seasonal workers who want to preserve their cash for fuel and maintenance.

Pros:
  • Direct manufacturer support
  • Options for specialized equipment
  • Streamlined application process
Cons:
  • Terms are subject to specific model availability

2. JetzLoan
JetzLoan – jetzloan.com

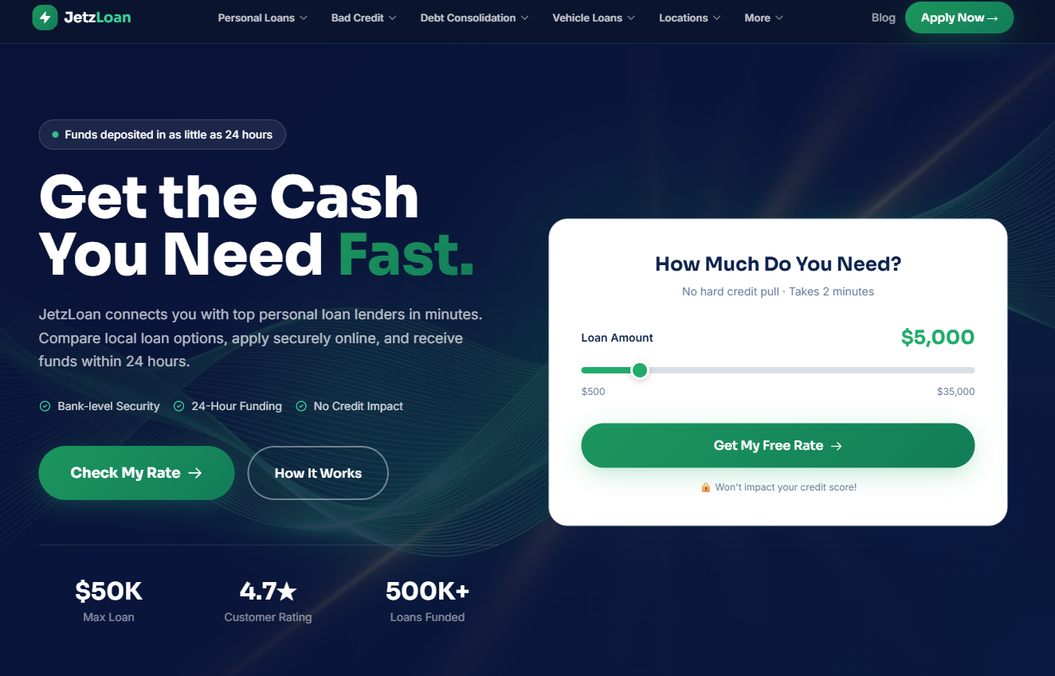
When speed is the name of the game, JetzLoan stands out. They specialize in getting funds deposited into your account in as little as 24 hours. This is a lifesaver if your current mower kicks the bucket in the middle of a busy season.

In the landscaping business, a broken mower isn’t just an inconvenience; it is a halted revenue stream. JetzLoan fills that gap by providing liquidity when traditional banks might take a week to process the paperwork. It is built for the person who needs to keep working.

They offer loans up to $35,000 and do not perform a hard credit pull during the initial check. You can see your rate without any fear of a temporary dip in your credit score. This “soft pull” technology is essential for buyers who want to shop around and compare monthly payments before committing.

Pros:
  • Extremely fast 24-hour funding
  • No hard credit pull for initial rates
  • High maximum loan limit
Cons:
  • Digital-first approach may lack personal interaction

3. Gravely
Gravely – gravely.com

Gravely is a heavy hitter for those who treat lawn care as a professional vocation. Their financing options are built for longevity and serious business. They even offer specialized fleet pricing for pros looking to grow their entire crew’s capabilities.

Unlike consumer-grade financing, Gravely’s options often account for the higher depreciation and higher usage rates of commercial machines. They understand that a commercial mower is a tool that works much harder than a residential one.

If you are looking to outfit a fleet of commercial zero-turn mowers, Gravely provides the structural support to make that happen. They focus on the professional who needs equipment that works as hard as they do. This might include tax-advantaged leasing options or specialized business lines of credit as your client list grows.

Pros:
  • Excellent fleet pricing programs
  • Designed for commercial-scale use
  • Strong brand reputation
Cons:
  • Credit approval is strictly required

4. K and G Mowers

K and G Mowers – kgmowers.com

K and G Mowers provides an aggressive deal for those looking to maximize their purchasing power. They offer 0% APR financing for up to 48 months on various mowers and tractors. This is a massive advantage for someone wanting to keep their cash liquid while still getting new gear.

At 0% APR, every dollar you pay goes directly toward the principal of the machine. You aren’t being eaten up by interest charges that can add hundreds or even thousands to the total price. It is a very efficient way to use your money.

Their process is user-friendly, allowing you to get prequalified without a credit impact. Based in Paris, TX, they also provide local delivery and in-house service. This hybrid model—combining online prequalification with local, physical service—is ideal for buyers who want modern fintech convenience with the security of a brick-and-mortar business.

Pros:
  • 0% APR for up to 48 months
  • No credit impact prequalification
  • Local delivery and service available
Cons:
  • Physical location is localized to Texas

5. Manhattan Bank
Manhattan Bank – manhattanbank.com

For those who prefer the security of a traditional institution, Manhattan Bank offers a stable alternative. As an FDIC-insured entity, they provide the peace of mind that comes with working with a bank backed by the U.S. Government. This is vital for large-scale commercial purchases.

If you are seeking a high-limit business loan that requires deep scrutiny of your company’s financial history, a bank is often the right path. They offer personal and business loans for many different occasions, catering to various needs.

While it might not be as “instant” as a fintech app, the stability and professional oversight of a bank can be vital for complex financing. If you are planning to build a massive equipment warehouse or purchase multiple heavy tractors, a relationship with an established bank can provide more flexible long-term lines of credit.

Pros:
  • FDIC-insured security
  • Personal and business loan options
  • Established banking reputation
Cons:
  • Likely slower than instant digital lenders

6. Minute Loan Center
Minute Loan Center – minuteloancenter.com

Minute Loan Center is the go-to for people who need money immediately and may have had a bumpy road with their credit. They focus on fast approval, even for those with fair credit, and can offer same-day deposits via direct deposit. This is perfect for emergencies.

Imagine a mower fails on a Monday and you need a new one working by Tuesday to fulfill your contracts. This is an excellent choice for that “emergency replacement” scenario. They emphasize a transparent process with no hidden fees, which helps take the stress out of a high-pressure decision.

While the interest rates might reflect the higher risk of the loan, the speed and accessibility make it a vital resource for maintaining business continuity. It is about keeping your business moving when things go wrong.

Pros:
  • Same-day loan disbursement
  • Approvals for fair credit holders
  • No hidden fees
Cons:
  • Interest rates may be higher for non-prime credit

7. Yanmar
Yanmar – yanmar.com

Yanmar represents a global standard for heavy-duty, high-quality machinery. While they are a massive international entity, their financing is about providing a way to access world-class equipment across various regions. Their structures often reflect the high resale value of Yanmar machines.

This high resale value can make securing a loan easier through specialized agricultural or commercial lenders. They are a great choice for those who want the absolute best in engineering and a brand that supports its machinery globally.

It is a long-term investment in quality that spans continents. When you finance a Yanmar, you aren’t just buying a machine; you are investing in a piece of infrastructure that is expected to serve you for a decade or more.

Pros:
  • World-class machinery quality
  • Global brand presence
  • Highly durable equipment
Cons:
  • Less focus on consumer-level quick financing

The True Cost: Interest vs. Opportunity Cost

When deciding between a low-interest manufacturer deal and a high-speed digital loan, you must weigh interest costs against opportunity costs. For example, if a manufacturer offers 0% APR for 48 months, but a digital lender like JetzLoan offers a 5% interest rate but provides the money 4 days faster, which is better for you?

If those 4 days allow you to complete three landscaping jobs that generate $1,200 in profit, then the “expensive” loan actually saved you money. The speed of the capital outweighed the cost of the interest. You have to look at the bigger picture of your cash flow.

Conversely, if you are a homeowner with a large savings account, paying cash might seem like the best move to avoid interest. However, if that cash could be earning 5% in a high-yield savings account while you only pay 3% on a mower loan, you are actually losing money by paying cash. Understanding the math is the difference between a smart purchase and a financial burden.

Common Financing Pitfalls to Avoid

Before you sign any paperwork, take a moment to breathe and look at the fine print. Many people fall into the trap of only looking at the monthly payment. A low monthly payment sounds lovely, but if it comes with a massive interest rate over five years, you will end up paying for that mower twice.

Always calculate the “Total of Payments.” Multiply the monthly payment by the number of months to see the real cost. It is a simple calculation that reveals the truth behind the marketing. You need to know exactly how much cash is leaving your pocket over the life of the loan.

Always check if the lender offers a “no credit impact” prequalification. This allows you to shop around and compare different offers from companies like JetzLoan or K and G Mowers without hurting your credit score. It is like window shopping; you want to see the price before you commit to the test drive.

Watch out for the “hidden” costs that often hide in the shadows of a contract. Some lenders might charge origination fees or high late fees if you miss a single payment. If you are buying for a business, ensure the terms align with your seasonal income.

You might want to ask specifically about “seasonal payment” options. These allow you to pay more in the summer and less in the winter—a feature many commercial lenders are willing to provide for established businesses. It keeps your finances balanced when the grass isn’t growing.
The 7 Best Lenders for Tractor Financing in 2026

Tractor financing

The 7 Best Lenders for Tractor Financing in 2026

Last updated: 2026-10-16

Securing enough capital to keep a farm running often feels more taxing than the actual harvest. Whether you need a new fleet of combines for a large-scale operation or a single utility machine for a small hobby farm, the terms you sign today will dictate your cash flow for years. It is a high-stakes game of math and timing.

One miscalculated interest rate or an unexpected balloon payment can throw your seasonal budget into chaos. You don’t want a year of hard work to spiral into a permanent cycle of debt. Choosing a lender is less about finding a transaction and more about finding a partner that won’t become a barrier to your success.

When weighing your options, pay attention to how flexible the terms are and how fast the cash arrives. You should also consider how a lender treats your specific credit history. You might be tempted by the speed of a digital approval, but don’t ignore the long-term stability and lower rates often found at established, brick-and-mortar institutions.

  1. Mahindra
  2. FastLendGo
  3. AgDirect
  4. Yanmar
  5. Manhattan Bank
  6. VivaLoan
  7. Roadrunner Financial

How These Financing Options Were Evaluated

We looked across a wide spectrum of agricultural needs to pick these lenders. Our list includes everything from specialized equipment manufacturers to community-focused banks. We wanted a mix of speed, accessibility for different credit scores, and the ability to handle various types of machinery. We didn’t just read marketing brochures; we looked at how these lenders fit into the actual lifecycle of a farm.

Speed of decision-making and collateral requirements were our primary metrics. Some lenders excel at rapid digital applications using “soft” pulls that won’t ding your credit. Others offer the heavy-duty, long-term stability you get through secured loans from traditional banks. We also looked at the “niche” factor—whether a lender is built for high-value tractors or for the quick cash needed for seasonal repairs.

This variety ensures there is a match for every situation, whether you are looking to buy a $200,000 harvester or a $5,000 utility trailer. Every farm has a different rhythm, and the financing needs to match that pace. You shouldn’t have to fit your business into a lender’s rigid box.

Lender Name Loan Amounts Funding Speed Credit Requirements Terms/Specialty
Mahindra see site see site 550 FICO minimum 6-year warranty options
FastLendGo $500 – $5,000+ Fast access All credit types Personal financing focus
AgDirect see site Seconds for most See site New and used equipment
Yanmar see site see site see site Global availability
Manhattan Bank see site see site see site Personal and business
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome Small personal loans
Roadrunner Financial see site Real-time decision All credit scores Powersports focus

Top-Tier Agricultural Lenders

1. Mahindra

Mahindra – mahindratractor.com

Mahindra has built a massive reputation in the tractor industry. They offer specialized financing for many different needs, which is helpful if you might struggle to meet traditional bank requirements. It is a solid choice if you want a brand with deep roots in the farming community, providing the kind of security that comes with manufacturer-backed terms.

The company provides options for people with a minimum credit score of 550 FICO. This makes it a viable path for those with a limited credit history or anyone who has seen a temporary dip in their score due to seasonal fluctuations. Their dealer network makes the process easier, often allowing for on-site consultations and direct applications right at the dealership.

Pros:

  • Low entry barrier with 550 FICO minimum
  • Covers those with limited credit history
  • Strong brand reputation and presence

Cons:

  • Credit approval is subject to specific terms

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a versatile option for anyone needing quick access to cash. While they cover a wide range of personal loans, their speed makes them a useful tool for immediate operational needs. This includes things like buying fuel in bulk or paying for emergency repairs that don’t fit into your standard operating costs. (fastlendgo.com)

If you find yourself facing an unexpected repair or a sudden need for working capital, this lender moves fast. They cater to a broad demographic, including those with bad credit or high-income individuals looking for specific loan structures. Their model relies on high-speed digital processing, which is perfect for the modern farmer who cannot afford to wait weeks for a bank committee to meet.

Pros:

  • Extremely fast access to cash
  • Covers various states across the US
  • Flexible for bad credit scenarios

Cons:

  • Primarily focused on personal loans rather than specialized ag-equipment

3. AgDirect

AgDirect – agdirect.com

AgDirect is a heavyweight in the world of specialized farm equipment financing. They provide options for both new and used machinery, whether you are buying from a dealer, an auction, or a private party. This flexibility is a massive advantage if you find a great deal on a used implement at a local auction and need financing that moves as fast as the auction hammer.

Their digital process is impressively quick. Most applications get a credit decision in seconds, allowing you to move on a piece of equipment before a competitor grabs it. This “instant” aspect is vital in a market where high-demand machinery can sell within hours. It is a modern way to handle agricultural lending, cutting out the friction of physical paperwork.

Pros:

  • Ultra-fast credit decisions for most
  • Covers new, used, and private sales
  • Seamless online application process

Cons:

  • Primarily focused on equipment rather than general cash flow

4. Yanmar

Yanmar – yanmar.com

Yanmar is a global name that brings international expertise to the table. They serve a massive range of regions, from the United States to Europe and Asia. This makes them a reliable choice for those who want a manufacturer with global reach and a standardized level of service.

When you work with a manufacturer-aligned lender, you deal with people who understand the specific value of the machinery. They know a tractor’s utility is tied to the season, so they may offer specialized terms or repayment schedules that a general bank might overlook. This alignment can lead to better terms for highly specialized agricultural implements.

Pros:

  • Massive global presence and reliability
  • Manufacturer-linked expertise
  • Diverse regional availability

Cons:

  • Highly regionalized availability for certain products

5. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank offers a more traditional, stable approach. They provide a range of personal and business loans, which is vital for established operations looking for structured banking relationships. For a farm that has been running for decades, a stable banking partner is often more important than a quick loan.

If you prefer speaking with a human being, you can talk directly to a loan officer here. This is incredibly helpful when navigating complex business loans, like land purchases or large-scale facility upgrades. Being able to walk into a branch and explain your specific agricultural cycle provides a level of comfort that purely digital lenders cannot match.

Pros:

  • Option to speak with a loan officer directly
  • FDIC-insured stability
  • Offers both personal and business products

Cons:

  • May require more traditional documentation than fintech lenders

6. VivaLoan

VivaLoan – vivaloan.com

VivaLoan is built for the person who needs money quickly without a mountain of paperwork. They specialize in small personal loans, ranging from $100 up to $15,000. This is an agile way to bridge a small financial gap, like a sudden part failure that requires an immediate purchase from a supplier.

Speed is the main selling point here, with funds potentially available as soon as the next business day. For a farmer needing a quick fix for a small piece of equipment or an unexpected expense like a vet bill, this is very efficient. It fills the gap between using a credit card and taking out a major commercial loan.

Pros:

  • Extremely fast funding, often by the next day
  • Low minimum loan amounts
  • Welcomes all credit types

Cons:

  • Loan amounts are relatively small for major machinery

7. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial is a specialized player focused on the powersports and smaller utility vehicle market. They are an excellent choice if your “tractor” needs involve ATVs, side-by-sides, or golf carts used for farm tasks. Many modern farms rely heavily on these smaller, mobile vehicles for daily operations.

They offer a streamlined pre-qualification process that does not impact your credit score. This allows you to see what you might qualify for without any immediate risk to your financial standing. You can test the waters of different financing tiers without the fear of a “hard inquiry” lowering your score right before a larger application.

Pros:

  • No credit score impact to check rates
  • Specialized in utility/powersports vehicles
  • Quick real-time decisions

Cons:

  • Limited to specific vehicle types like ATVs and side-by-sides

Understanding the True Cost of Borrowing

Many farmers make the mistake of looking only at the monthly payment. While a low monthly payment is tempting for cash flow, you must calculate the Total Cost of Ownership (TCO) for your debt. This means looking at the interest over the entire life of the loan. A 7-year loan with a low interest rate might actually cost you $5,000 more in total interest than a 5-year loan with a slightly higher rate.

Keep these three factors in mind before you sign anything:

  • Amortization Schedule: How much of your payment goes toward the principal versus interest in the early years?
  • Prepayment Penalties: If you have a great harvest and want to pay the loan off early to save on interest, will the lender charge you a fee?
  • Variable vs. Fixed Rates: In an inflationary environment, a variable rate can become dangerous if interest rates spike. A fixed rate provides the certainty needed for long-term budgeting.

Preparing Your Financial Application

Whether you go to a local bank or an online fintech, the quality of your application determines the speed and terms you get. Lenders want to see that you are a low-risk operator with a clear plan for the capital you are requesting.

To maximize your chances of approval and better rates, follow these steps:

  1. Organize Your Financial Statements: Have your last two years of tax returns, current balance sheets, and profit and loss (P&L) statements ready. Having these ready to upload can prevent delays.
  2. Define the Asset’s Value: If you are financing equipment, have the specific make, model, year, and serial number ready. For used items, have a clear idea of the current market value.
  3. Check Your Own Credit: Don’t wait for the lender to find an issue. Check your report for errors. If you have a low score, be prepared to explain why—such as a seasonal debt cycle—to provide context.
  4. Have a Repayment Plan: Be ready to explain how this purchase will generate the revenue to pay back the loan. For example: “This new harvester will reduce labor costs by 15%.”

Selecting the Best Path Forward

Before signing any contract, look at the total cost of borrowing. Don’t just look at the monthly payment; look at the interest over the life of the loan. A lower monthly payment often means a much longer term, which can end up costing you significantly more in the long run.
Avoid the mistake of rushing into a deal just because the equipment is available. Always compare terms from a manufacturer-based lender against a local community bank. Often, the bank might offer better long-term rates, while the manufacturer offers better immediate convenience and specialized coverage.

Finally, keep your credit score in mind. If your score is on the lower side, focus on lenders like Mahindra or VivaLoan that are more accommodating to diverse credit profiles. Knowing your own financial strength before you start shopping will save you hours of frustration and help you secure the tools you need to grow.

The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026

Personal loan after bankruptcy

The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026

Last updated: 2026-10-16

Trying to fix your finances after a bankruptcy can feel like walking through a thick fog. You might need a quick car repair to get to work, or perhaps an unexpected medical bill popped up right after your discharge. Sometimes, it is just about bridging a gap caused by a sudden change in employment. The goal is to find a lender who sees your current potential instead of just your past mistakes.

The way people borrow money has changed a lot. Where a bankruptcy once acted as a permanent “no,” modern fintech companies and community institutions are looking at your recent behavior. They care about the trajectory of your finances today rather than just the scars left on your credit report from years ago. It is about where you are going, not just where you have been.

Picking the right lender involves more than just glancing at an interest rate. You have to weigh how fast you can get the cash, what the minimum requirements are, and how much flexibility the company offers. Some providers focus on rapid cash for emergencies, while others offer structured installment plans to help you rebuild your credit over time. It is a balancing act between speed and long-term stability.

Accessibility is a tricky term that does not mean the same thing to everyone. A lender that is incredibly easy to get approved with might charge a premium for that convenience. On the other hand, a lender with stricter rules might offer the lower rates you need for long-term debt management. You have to decide whether you need a quick fix or a long-term strategy.

  1. FastLendGo
  2. SoFi
  3. Prosper
  4. Avant
  5. Allegiance Credit Union
  6. VivaLoan
  7. World Finance

Evaluating Lenders for Post-Bankruptcy Borrowing

This ranking focuses heavily on how easy it is to get approved and how fast you see the money. Financial emergencies do not wait for a perfect credit score to resolve themselves. We prioritized lenders that provide clear paths for people with different credit histories. If a delay of three days means you lose your utility service, you need a lender that moves quickly.

We also looked at the variety of loan amounts available. A lender that only offers tiny microloans might not help if you need to consolidate debt or fix a roof. Conversely, traditional banks often have massive hurdles, requiring collateral or credit scores that a post-bankruptcy borrower simply cannot reach yet. We looked for “soft” credit pulls so you can shop around without hurting your score.

Lender Name Loan Amounts Funding Speed Credit Requirements
FastLendGo $500 – $5,000+ Quick access Bad/Fair/Good/Great
SoFi see site see site see site
Prosper $2,000 – $50,000 Fast access see site
Avant see site see site see site
Allegiance Credit Union see site see site see site
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome
World Finance see site see site see site

The Top Ranked Lenders for Rebuilding Credit

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a great option for anyone stuck in a tight spot. They offer a wide range of options, from small $500 loans to larger $5,000 packages. This flexibility is helpful if you are juggling several different needs, like a small repair for a car and a larger bill for your taxes.

The whole platform is built for speed, which is perfect if you need cash immediately. Whether you are dealing with dental bills, auto repairs, or home maintenance, they make it easy to compare local options. Traditional banks often require mountains of paperwork and multiple trips, but FastLendGo uses a digital-first approach to get things moving quickly.

It is a solid choice for a quick fix when you cannot afford to wait around for a long approval process.

Pros:
  • Wide variety of loan amounts from $500 to $5,000 and beyond.
  • Covers specific needs like auto, dental, and roof financing.
  • Accommodates various credit tiers from bad to great.
Cons:
  • May not offer the lowest rates for those with excellent credit.

2. SoFi

SoFi – sofi.com

SoFi works more like a complete financial ecosystem. While many know them for banking and investments, they offer sophisticated tools to help manage your money. Their high-yield savings accounts can help you start rebuilding your savings effectively, giving you a safe place to park cash while your credit score climbs.

By automating your savings through their platform, you can build a buffer that helps you avoid high-interest debt in the future. This lender is perfect for the person who wants to manage everything in a single place, from checking accounts to mortgages.

They are more selective than the micro-lenders, but their products are built for people who have moved past their hardest financial struggles. It is a polished option if you are looking toward long-term stability and wealth growth.

Pros:
  • Integrated banking, investing, and insurance services.
  • High APY options for savings accounts.
  • User-friendly digital platform.
Cons:
  • Typically requires a higher credit tier for the best terms.

3. Prosper

Prosper – prosper.com

Prosper gives you a look into peer-to-peer (P2P) lending. They provide substantial amounts, ranging from $2,000 up to $50,000. This makes them a heavy hitter if you need to tackle major debt or large expenses like tuition or home renovations. Because they rely on individual investors rather than a bank’s pool of money, their criteria can be different from traditional lenders.

Their platform is fast and secure. You can see your rates in about a minute through a soft credit pull. This is vital if you are worried about hurting your credit score while you are just shopping around for the best deal.

For anyone wanting to move away from standard bank loans, Prosper offers an efficient experience. It is a strong choice for large-scale financing when a traditional bank might have given you a hard no.

Pros:
  • High loan ceilings up to $50,000.
  • Quick rate checking with minimal impact to credit.
  • Fast and secure online application process.
Cons:
  • Peer-to-peer models can sometimes have variable approval rates based on investor demand.

4. Avant

Avant – avant.com

Avant focuses on helping you move your financial life forward. They offer solutions like credit cards and installment loans, which are great for proving you can make consistent, on-time payments. Their approach feels more like a partnership, providing tools to help you reach specific goals like debt consolidation.

Whether you need to combine several high-interest payments into one manageable monthly bill or you just need an emergency loan for a sudden crisis, Avant has options. They aim to provide clear answers to difficult financial questions.

Their model is tuned for the middle-ground borrower. These are people who might not have elite scores but have shown steady income and responsibility through their recent financial history.

Pros:
  • Specializes in debt consolidation and emergency loans.
  • Flexible solutions for different life stages.
  • User-focused support and tools.
Cons:
  • Specific eligibility criteria can be difficult to navigate.

5. Allegiance Credit Union

Allegiance Credit Union – allegiancecu.com

Allegiance Credit Union is a community-focused institution that has been around since 1963. They operate under the idea that every story matters, including those of people rebuilding after a setback. This approach is different from large, impersonal national banks where you are just a number on a screen.

In a credit union, your local environment and your relationship with a loan officer actually carry weight. They offer products designed to help you save, borrow, and build a stronger future. If you prefer a mission-driven banking experience, a credit union is a refreshing change.

They often provide more personalized guidance during the application. This is incredibly helpful when you need to explain why your past bankruptcy is behind you and why your current situation is stable and looking up.

Pros:
  • Strong community roots and long-standing reputation.
  • Mission-driven approach to member well-being.
  • Diverse products for saving and borrowing.
Cons:
  • Geographic limitations may apply to membership.

6. VivaLoan

VivaLoan – vivaloan.com

VivaLoan is built for speed. They offer loans starting as low as $100 up to $15,000. This wide spectrum lets you find exactly what you need, whether it is a tiny amount for new tires or a larger sum for a major life event. This flexibility is vital if you are still in the stabilization phase of your recovery.

One of their best features is the speed of funding. You can often receive your money as soon as the next business day. With a five-minute application process and an open policy for all credit types, they are a lifeline in an emergency.

While the ease of use is hard to beat, you should use these funds strategically. You want to avoid falling into a cycle of high-interest borrowing that can keep you stuck.

Pros:
  • Extremely fast funding, often by the next business day.
  • Very low minimum loan amount of $100.
  • Welcomes all credit types.
Cons:
  • High speed and accessibility can come with higher costs.

7. World Finance

World Finance – worldfinance.com

World Finance is a specialized player in the market. They offer a variety of services, including retail and private banking. Their focus often leans toward more structured financial environments and specialized segments, providing options for people who do not fit into a standard consumer lending box.

This can include people with unconventional income streams or those needing very specific loan structures. They provide a deep look into both global and local economic trends for their clients.

For those seeking a more complex financial partner, they offer services that go beyond a simple personal loan. Their expertise is useful for borrowers navigating a sophisticated recovery involving multiple asset types.

Pros:
  • Wide breadth of financial services and insights.
  • Expertise in diverse banking sectors.
  • Professional focus on market trends.
Cons:
  • May be more complex than a standard consumer lender.

Strategies for Maximizing Your Approval Odds

Securing a loan after a bankruptcy discharge requires a strategic approach. Lenders want to see “stability indicators.” Even if your score is still recovering, you can improve your odds by providing organized documentation of your income. This means having recent pay stubs, bank statements, and tax returns ready to go. A lender is much more likely to say yes if they see a clear, unbroken line of income.

Another smart move is to consider a “secured” loan if “unsecured” options are proving too difficult. A secured loan is backed by an asset, like a car title or a savings account. Because the lender has collateral, their risk is much lower, which often leads to higher approval rates and better interest rates. Once you pay that loan back, your credit score usually gets a significant boost.

This path paves the way for the larger, unsecured loans you might need later on. It is a way to prove your reliability to the banks while you are still getting back on your feet.

Common Pitfalls to Avoid During Your Search

When you are looking for a loan, the biggest mistake is rushing into the first offer you see. You must compare the total cost of borrowing, not just the monthly payment. A low monthly payment can hide a much higher interest rate or a term that is so long you end up paying double what you borrowed. Always ask for the Annual Percentage Rate (APR) to see the true cost.

Another mistake is failing to check your credit report for errors before you apply. Even after a bankruptcy is discharged, mistakes can linger. A debt that was included in your bankruptcy might still show as “unpaid” on your report. Clean up your records first to give yourself the best chance of success.

Finally, read the fine print regarding prepayment penalties. Some lenders charge a fee if you try to pay the loan off early. This is the last thing you want when you are trying to move out of debt quickly. Approach your search with patience. The journey to financial health is a marathon, not a sprint.

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Holiday loans for bad credit

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Last updated: 2026-10-16

The holiday season often brings a whirlwind of expenses that can catch anyone off guard. Between unexpected gifts, last-minute travel tickets, and seasonal hosting costs like grocery surges and decor, the financial squeeze can feel overwhelming. For those facing the holidays with less-than-perfect credit, finding a reliable way to bridge the gap is essential for a stress-free December.

Rather than relying on high-interest payday loans that can lead to a cycle of debt, many are turning to specialized lenders that prioritize speed and accessibility. When selecting a lender, the priority shifts from finding the lowest APR to finding speed and accessibility.

A lender that offers quick funding can be a lifesaver when a last-minute purchase is needed, such as a sudden car repair required to get home for the holidays or an unexpected catering bill for a family gathering. It is vital to look for transparency regarding fees and how the application process might impact your current credit standing.

Understanding the difference between a “hard pull”—which can temporarily lower your score—and a “soft pull”—which is essentially harmless—is the first step in making an informed decision.

  1. JetzLoan
  2. Addition Fi
  3. OppLoans
  4. World Finance
  5. Sound Credit Union
  6. OneMain Financial

How These Holiday Lenders Were Evaluated

The ranking process focused on speed, accessibility, and the ability to secure funds despite a challenging credit history. Each option was assessed based on how quickly money hits a bank account and whether the application process involves a hard credit pull. This is a crucial distinction for anyone looking to shop around without damaging their score.

We analyzed the “time-to-cash” metric, which measures the elapsed time from the moment you click “apply” to the moment the funds are available for spending in your checking account. Accessibility was also a key pillar. Lenders were evaluated on their ability to serve individuals who might be turned down by traditional banks.

Traditional banking institutions often rely heavily on FICO scores and long-term credit history, which can be a barrier for those with recent setbacks. Our evaluation looked for providers that offer clear terms, minimal hidden fees, and a straightforward path from the initial application to receiving the necessary cash for seasonal needs.

We specifically prioritized lenders that provide a “pre-qualification” step, allowing you to see potential terms before committing to a formal application.

Lender Name Max Loan Amount Funding Speed Credit Impact Terms/Rates
JetzLoan $50,000 As little as 24 hours No hard credit pull See site
Addition Fi See site See site See site See site
OppLoans See site Same-day funding available No FICO score impact See site
World Finance See site See site See site
Sound Credit Union See site See site See site
OneMain Financial $30,000 As soon as 1 hour No credit score impact Starting at 11.99% APR

Top Rated Lenders for Seasonal Funding

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan connects borrowers with top personal loan lenders in just a few minutes. It is an ideal solution for those who need a significant amount of cash, with loan limits reaching up to $50,000. The process is designed to be incredibly fast and transparent, removing the bureaucratic red tape often found in big-box banking. (jetzloan.com)

This option is perfect for individuals who need flexibility without the fear of a credit score dip. Because there is no hard credit pull during the initial check, you can explore your options freely. This “soft inquiry” approach allows you to gauge your eligibility and potential interest rates without the risk of a score decrease.

Funds can be deposited into your account in as little as 24 hours. This makes it suitable for those facing a tight deadline, such as a holiday travel booking that is about to expire.
Pros:

  • High maximum loan amount of $50,000
  • Fast 24-hour funding
  • No hard credit pull during the rate check
Cons:
  • Connecting with lenders takes a few minutes of application time

2. Addition Fi

Addition Fi – additionfi.com

Addition Financial operates as a full-service credit union, offering a wide variety of banking products. While they provide traditional loans, their focus is on building a long-term relationship with members. They offer competitive rates designed to help people borrow smarter and save more over time.

Unlike some predatory lenders, credit unions are member-owned. This means their primary goal is to serve their community rather than maximize shareholder profits. This is a great choice for those who want more than just a quick loan. They provide checking, savings, and various investment options.

It is a more stable, community-oriented approach for anyone looking to manage their finances more holistically during the holidays. If you are planning to make a large purchase, such as a used vehicle for holiday travel, their specialized loan products might offer better terms than a general personal loan.

Pros:

  • Diverse range of banking and investment services
  • Competitive rates on various products
  • Member referral incentives available
Cons:
  • May require membership to access full benefits

3. OppLoans

OppLoans – opploans.com

OppLoans is built around the idea that a credit score doesn’t tell the whole story. Their platform works with bank partners to provide personal loans that consider more than just a FICO number. They look at a broader range of financial data, which is helpful for individuals who may have a high income but a low credit score due to past student loans or medical debt.

Speed is their specialty, with same-day funding available if you are approved. The application is quick and easy, often providing decisions within minutes. This makes them a streamlined option for those facing an immediate cash crunch during the holiday season, such as a sudden need for emergency home repairs before guests arrive.

Pros:

  • Same-day funding available
  • Decisions often made in minutes
  • Does not affect FICO score when applying
Cons:
  • Approval is subject to bank partner criteria

4. World Finance

World Finance – worldfinance.com

World Finance provides a broad spectrum of financial services, ranging from retail banking to specialized asset management. They offer a sophisticated approach to finance that covers everything from insurance to complex investment strategies and corporate governance. Their infrastructure is designed to handle a wide variety of financial needs, making them a versatile option for a diverse client base.

This entity is suited for individuals or businesses needing specialized financial structures rather than a simple quick cash injection. Their scope is much wider than a standard personal lender, offering deep expertise in various global economic sectors.

If your holiday needs involve more complex financial planning or business-related seasonal inventory financing, their expertise may be relevant.
Pros:

  • Extensive range of financial services
  • Expertise in multiple banking sectors
Cons:
  • May be more complex than a simple holiday loan provider

5. Sound Credit Union

Sound Credit Union – soundcu.org

Sound Credit Union serves its members with a comprehensive suite of loan products. They offer everything from personal and student loans to specialized financing for RVs, boats, and motorcycles. Their focus is on providing a variety of paths to meet different financial goals, ensuring that members have options whether they are looking for a small personal loan or a large asset-backed loan.

For those who need a specific type of loan, such as an auto or home loan, they offer a structured environment. They provide a range of services including mobile and online banking, making it easy to manage your money on the go. This is particularly useful during the holidays when you might be traveling and need to check your balance or transfer funds instantly via your smartphone.

Pros:

  • Wide variety of specialized loan types
  • Convenient mobile and online banking
  • Comprehensive service list from checking to retirement
Cons:
  • May require specific membership criteria

6. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those needing quick access to personal loans between $1,500 and $30,000. They pride themselves on offering more options than most people expect. You can often see your potential options in just five minutes without any obligation, which is ideal if you are comparing multiple lenders at once.

If you need money immediately, they offer a path to receive funds as soon as one hour after the loan is signed. With fixed monthly payments and terms ranging from 24 to 60 months, they provide a predictable way to handle seasonal expenses. This predictability is vital for budgeting; knowing exactly what you owe each month prevents any surprises when you are trying to save for January expenses.

Pros:

  • Extremely fast funding (as soon as 1 hour)
  • Fixed monthly payments for budget stability
  • Large network of 1,300 branches for personal help
Cons:
  • Interest rates can vary based on creditworthiness

Step-by-Step: How to Apply for Seasonal Funding

Securing a loan during the busy holiday season requires a methodical approach to ensure you get the best terms without unnecessary delays. Follow these steps to maximize your chances of success:

  1. Assess Your Total Need: Before applying, calculate exactly how much you need. Don’t just guess; look at your gift list, planned grocery budget, and any expected travel costs. Borrowing more than you need can lead to unnecessary interest costs.
  2. Check Your Credit Score: While many lenders offer soft pulls, knowing your score helps you set realistic expectations for the interest rates you might receive.
  3. Gather Documentation: To speed up the process, have your most recent pay stubs, proof of identity (like a driver’s license), and bank account details ready. Digital copies of these documents will significantly reduce application time.
  4. Compare Pre-Qualifications: Use the lenders mentioned above to check your eligibility. Focus on lenders that offer a “no hard credit pull” option to protect your score while you shop around.
  5. Review the Total Cost: Look beyond the monthly payment. Check the “Total Repayment Amount” to see exactly how much you will have paid by the end of the loan term.

Avoiding Common Financial Pitfalls

Before signing any agreement, it is vital to read the fine print. Many people fall into the trap of only looking at the monthly payment amount. However, the total cost of the loan is determined by the APR and the length of the term. A small monthly payment over a long period can end up costing significantly more in the long run.

For example, a $2,000 loan with a $100 monthly payment sounds manageable, but if the term is 36 months, you will have paid back $3,600—meaning you paid $1,600 in interest alone. Another mistake is failing to compare options. Even if you are in a rush, taking ten minutes to check a second or third lender can save hundreds of dollars.

Always ensure you are not paying hidden fees or unnecessary service charges that could eat into your holiday budget. Watch out for “origination fees”—charges taken directly from the loan amount before you even receive the cash—as these can significantly decrease the actual amount of money you receive.

Finally, consider your repayment plan. The goal of a holiday loan should be to bridge a temporary gap, not to create a long-term debt burden. Plan to pay the loan back as quickly as possible once the holiday season ends and your normal income stream resumes. By being diligent now, you can enjoy the festivities without the lingering shadow of financial stress in January.

The 6 Best Lenders for Roof Financing in 2026

Roof financing

The 6 Best Lenders for Roof Financing in 2026

Last updated: 2026-10-16

A leaking roof is more than a nuisance. It is a direct threat to your home’s foundation. When rain starts dripping through the ceiling, homeowners often scramble to find the liquid cash needed for immediate repairs. Water infiltration leads to mold, electrical hazards, and compromised beams. This can turn a simple shingle replacement into a catastrophic renovation project.

Financing helps bridge the gap between a sudden emergency and long-term stability. It allows you to secure materials and professional labor before the damage spreads. Choosing a lender depends on your credit health and how fast you need the money. Some people need funds by tomorrow morning for a contractor’s deposit. Others want the lowest interest rate to keep total costs down.

A homeowner with a 780 credit score might access premium, low-interest unsecured loans. Meanwhile, someone with a 620 score might prioritize approval speed over the lowest APR. Every financial situation requires a different strategy to get the job done right.

  1. JetzLoan
  2. LightStream
  3. United Finance
  4. Allegiance Credit Union
  5. Roadrunner Financial
  6. Avant

How These Financing Options Were Evaluated

We matched specific lender profiles with the common needs of homeowners facing roofing dilemmas. Speed of funding was a primary metric. Water damage does not wait for a slow approval process. We gave significant weight to lenders offering rapid, digital-first applications. We looked at how quickly a user moves from “application submitted” to “funds in bank.”

Accessibility for various credit tiers was another major factor. Roofing is often an unplanned expense. Many applicants might not have a perfect credit score due to recent life changes. We prioritized lenders that offer transparent terms without impacting credit scores during the initial inquiry. This allows consumers to window shop for the best rates using soft credit pulls.

We also examined the flexibility of loan terms. A roof replacement can cost $6,000 for a small repair or $25,000 for a full installation. Lenders offering tiered loan amounts and adjustable repayment periods are more valuable for the diverse range of roofing needs encountered by modern homeowners.

Lender Name Max Loan Amount Funding Speed Credit Requirements Other Notable Details
JetzLoan $50,000 As little as 24 hours No hard credit pull to check rate 4.7★ Customer Rating
LightStream See site Next day funding possible Excellent credit required for lowest rate 9.99%–24.94% APR with AutoPay
United Finance $20,000 See site See site See site Established 1922
Allegiance Credit Union See site See site See site Serves central Oklahoma
Roadrunner Financial See site Real-time decision All credit scores welcome Specializes in powersports/vehicles
Avant See site See site See site Offers credit cards and loans

Ranking the Top Lenders

1. JetzLoan

JetzLoan – jetzloan.com

When the clouds turn gray and the drips start hitting the floor, time is the ultimate enemy. JetzLoan connects homeowners with top personal loan lenders in minutes. This is built for those who value speed above almost everything else. If you are dealing with an active leak during a storm, you cannot wait for a loan officer to call you back on Monday.

The platform is incredibly user-friendly. You can fill out a simple form in under two minutes. This efficiency is a lifesaver for those who need to secure a roof before a storm hits. It provides a way to get cash quickly without the usual headache of traditional banking bureaucracy. The digital interface works great on mobile, so you can start the process from your phone in your driveway.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull to check your initial rate.
  • High customer satisfaction with a 4.7-star rating.

Cons:

  • Maximum loan amount is capped at $50,000.

2. LightStream

LightStream – lightstream.com

LightStream is a heavyweight in the lending space, especially for those with a stellar credit history. They offer an uncomplicated approach to lending. It is a breath of fresh air when you are already stressed about home maintenance. They specialize in high-value, low-interest personal loans for almost any purpose, including a full roof overhaul.

Their rates are quite competitive if you use AutoPay. This makes them a premier choice for the financially savvy homeowner. This lender is ideal for someone who has been diligent about their finances and wants to leverage good credit for a low fixed rate. It is a smooth, digital experience that can get funds into your account as quickly as the next day.

Pros:

  • Low fixed rates starting from 9.99% APR.
  • AutoPay discounts are available to lower costs.
  • Very fast approval and funding process.

Cons:

  • Requires excellent credit to access the best rates.
  • Rates are higher if you do not use AutoPay.

3. United Finance

United Finance – unitedfinance.com

Stability is the name of the game with United Finance. Having been in business since 1922, they bring a level of institutional trust that is hard to find in the modern fintech era. While many newer apps pop up and disappear, United Finance has weathered nearly a century of economic shifts. This provides security for those worried about the longevity of their lender.

They offer a straightforward approach to personal loans for home repairs. If you want a lender that understands the value of a long-standing reputation, this is a strong contender. They offer personal loans up to $20,000. This is a solid choice for medium-sized roofing projects or minor repairs, such as replacing a chimney flashing or a few damaged shingles.

Pros:

  • Decades of experience and proven reliability.
  • Simple and accessible online application process.
  • Personal loans available for big and small needs.

Cons:

  • Loan amounts are capped at a lower $20,000 limit.

4. Allegiance Credit Union

Allegiance Credit Union – allegiancecu.com

Credit unions often feel like a community. Allegiance Credit Union is no exception. They focus heavily on the individual story, whether you are saving for a first home or rebuilding after a setback. This mission-driven approach makes the borrowing process feel much more personal than dealing with a faceless national conglomerate.

Serving central Oklahoma since 1963, they are a great option for members who prefer a local institution over a massive national bank. Their products are designed to help you borrow smarter and build a stronger financial future. Because they are member-owned, their interests are often more closely aligned with yours than a traditional profit-driven bank.

Pros:

  • Strong focus on member financial well-being.
  • Community-oriented service model.
  • Provides various tools to help meet life goals.

Cons:

  • Membership is likely restricted to specific geographic areas.

5. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial is a bit of a wildcard in the roofing space. Their primary expertise lies in powersports financing. However, their streamlined, rapid decision-making process is highly efficient. They are built for speed and ease of use, making them a unique option for non-traditional borrowing needs.

The beauty of their system is the lack of commitment during the prequalification phase. You can see what you qualify for without any impact on your credit score. This is a massive relief when you are just trying to gauge your options. It is particularly useful if you are comparing several different loan offers simultaneously to see which fits your monthly budget.

Pros:

  • Real-time decisions with no credit score impact.
  • All credit scores are welcome.
  • Personalized loan offers that remain valid for 30 days.

Cons:

  • Specializes in vehicle/powersports, which may limit roofing-specific terms.

6. Avant

Avant – avant.com

Avant is a versatile player that caters to various financial life stages. Whether you need a personal loan for home improvement or a credit card to cover a sudden emergency, they offer a suite of solutions. Their digital platform handles the complexities of modern life, providing a clear interface for managing your debt.

They focus on flexibility. No two financial journeys are exactly the same. This makes them a good fallback option for those who need a specific tool for a specific problem, like an unexpected roofing bill. If you aren’t sure whether a single large loan or a credit card with a lower limit is better, Avant’s diverse lineup offers that choice.

Pros:

  • Wide range of products including credit cards and loans.
  • Flexible choices designed to meet diverse needs.
  • Friendly support and user-friendly digital tools.

Cons:

  • May not offer the specialized rates of a dedicated home improvement lender.

Comparing Loan Types for Roofing Projects

When deciding how to fund your roof, you must understand the distinction between different types of debt. Most homeowners choose between a personal loan, a home equity line of credit (HELOC), or a specialized home improvement loan. Each has a different impact on your financial profile and your home’s equity.

Loan Type Speed of Funding Impact on Equity Best For…
Personal Loan Fast (1-3 days) None (Unsecured) Emergency repairs and smaller projects.
HELOC Slow (Weeks) High (Secured) Large, planned renovations with high budgets.
Home Equity Loan Slow (Weeks) High (Secured) Fixed-rate financing for massive structural work.

For an emergency leak, a personal loan is almost always the superior option because of the speed of funding. Waiting three weeks for a HELOC appraisal while rain is actively pouring into your living room is not a viable strategy. However, if you are replacing the entire roof on a large estate, a home equity product may offer much lower interest rates over a longer period.

Navigating the Financing Landscape

Before signing anything, you must shop around. A single interest rate difference might seem small on paper—perhaps only 0.5%—but over a five-year loan, it can represent thousands of dollars in extra interest. Always compare the total cost of the loan, including any hidden fees or origination costs that might be rolled into the principal balance.

One common mistake is rushing into the first offer because you are in a panic. While speed is essential, a desperate decision can lead to predatory terms or high APRs. Take a moment to check if the lender offers a “no hard credit pull” option. This “soft pull” allows you to compare JetzLoan against LightStream without any penalty to your creditworthiness.

Finally, ensure the loan term aligns with your monthly budget. A longer term, like 60 or 72 months, will lower your monthly payment. This is great for immediate cash flow and keeping overhead low. However, it will significantly increase the total interest you pay over the life of the loan. Aim for the shortest term you can comfortably afford to minimize the “cost of money.”

Top 4 Dental Financing Options Ranked for 2026

Dental financing

Top 4 Dental Financing Options Ranked for 2026

Last updated: 2026-10-16

Walking into a dentist’s office only to receive a price tag that feels like a punch to the gut is a common nightmare. Most people find themselves staring at a bill for implants or crowns, wondering if they will ever see their bank account balance rise again. Whether it is an emergency root canal necessitated by a sudden infection or a planned cosmetic procedure like veneers that promises a total transformation, the upfront cost can be staggering. Finding a way to bridge that gap without breaking the bank is essential for maintaining both your physical health and your financial stability.

Choosing the right way to pay for your smile isn’t just about the monthly payment. It involves looking at interest rates, how a lender treats your credit score, and how quickly you can get the green light. A high interest rate might make the monthly installment seem manageable, but over a 24-month period, you could end up paying thousands more than the actual cost of the dental work. Conversely, a lender that requires an impeccable credit score might leave you in pain while you wait weeks for an approval. This ranking looks at the most prominent players in the market to help you decide which path leads to a healthy smile.

  1. CareCredit
  2. Cherry
  3. FastLendGo
  4. iCare

How These Dental Payment Solutions Were Evaluated

The selection process focused on the specific needs of patients facing unexpected oral health costs. We looked at whether a lender provides quick decisions, which is vital when a toothache won’t quit. Speed often matters just as much as the actual cost of the loan when you are in pain. If you are sitting in a waiting room with a throbbing molar, you don’t want to be told you have to wait three business days for a manual underwriting process to finish. You need a solution that works in real-time.

We also weighed the accessibility of these options for individuals with varying credit profiles. Some patients have pristine scores and can qualify for the lowest possible APRs, while others are just trying to keep their heads above water and may have a history of late payments or high credit utilization. A good financing partner should offer a way forward, regardless of whether your credit history is a polished gem or a bit of a mess. We evaluated lenders based on three primary pillars: speed of approval, ease of application, and the breadth of credit eligibility. We also considered the “hidden” costs, such as origination fees or penalties for early repayment, which can turn a simple payment plan into a long-term debt trap.

Lender Name Primary Use Case Speed of Decision Credit Requirement Loan Amounts
CareCredit Health & Wellness Instant Subject to Approval See site
Cherry Flexible Payment Plans Fast Broad Eligibility See site
FastLendGo Personal Loans Quick All Credit Tiers $500 – $5,000+
iCare No-Nonsense Financing Instant No Credit Check See site

Understanding the Cost of Delaying Care

It is tempting to push a dental bill to the “next month” pile, but in dentistry, procrastination is often the most expensive financial decision you can make. Oral health issues are rarely static; they are progressive. A small cavity that costs $200 to fix today can evolve into a cracked tooth requiring a $1,500 crown in six months, or an even more expensive $2,500 root canal and buildup if the infection reaches the nerve.

When comparing financing options, it is helpful to view the cost of the loan against the cost of the untreated condition. If a lender offers a 0% interest plan for six months, the “cost” of the money is effectively zero, making it a highly efficient way to manage cash flow. However, if you choose a high-interest personal loan to avoid a waiting period, you must calculate if the interest paid is less than the projected increase in the cost of the dental procedure if it worsens. In many cases, the interest on a loan is a small price to pay to prevent a surgical emergency later.

Ranking the Best Lenders for Your Dental Care

1. CareCredit

CareCredit – carecredit.com

CareCredit operates as a specialized health and wellness credit card designed for medical and dental needs. It is a heavy hitter in the industry, accepted at over 285,000 locations. This makes it a very convenient choice if your dentist is already part of their vast network of providers. Because it is a dedicated credit line, it doesn’t clutter your primary personal credit card utilization, which can help keep your credit score stable if managed correctly.

The application process is designed to be painless, offering instant credit decisions so you aren’t left waiting. It is an ideal solution for those who want a dedicated line of credit specifically for health-related expenses and want to pay over time. Many providers offer “deferred interest” promotions—for example, 6, 12, or 24 months of 0% interest. This is a powerful tool, but it comes with a significant caveat: if you fail to pay the full balance by the end of the promotional period, you are often backdated and charged all the interest that would have accrued from day one. You must be disciplined to make this work.

Pros:

  • Extremely wide acceptance at dental offices nationwide.
  • Instant decisions mean you can start treatment quickly.
  • Prequalification does not impact your credit score.

Cons:

  • Subject to credit approval and standard card terms.

2. Cherry

Cherry – trycherry.com

Cherry has carved out a niche by offering more modern, patient-friendly payment plans. They are known for having broader eligibility criteria, which is a breath of fresh air for those who might be nervous about traditional bank loans. It feels less like a rigid contract and more like a helpful tool. Instead of a revolving credit card, Cherry often functions more like a structured installment loan, where you know exactly how much you owe and when each payment is due.

This option is perfect for patients who want a straightforward payment structure without the heavy lifting of traditional credit cards. It aims to make ownership of your dental care feel immediate and much less intimidating for the average person. Because Cherry integrates directly with many dental practice management softwares, the checkout process at the dentist’s office is often as simple as a few clicks on a tablet, allowing you to walk out with your treatment scheduled and your financing settled in minutes.

Pros:

  • Broad eligibility criteria for a wider range of people.
  • Provides a flexible alternative to standard credit cards.
  • Streamlined process for quick payment plan setups.

Cons:

  • May not offer the same high limits as traditional credit lines.

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, including dental work. They cater to a wide spectrum of borrowers, from those with great credit to those struggling with bad credit. This makes them a go-to for people who need a personal loan specifically for dental care where the dentist’s in-house financing might be too restrictive or unavailable. Unlike a credit card, which you use at the point of sale, a personal loan from FastLendGo is often deposited directly into your bank account.

If you need a lump sum of cash to cover a large procedure, this is a strong contender. They offer various loan sizes, starting from small amounts like $500 up to $5,000 or more, making them quite flexible for different treatment scales. This is particularly useful if you are paying a dentist who does not participate in any third-party financing programs. Having the cash in hand allows you to negotiate a “cash discount” with some providers, which can sometimes offset the interest cost of the loan itself.

Pros:

  • Accepts various credit levels, including bad credit.
  • Offers specific loan amounts for different needs.
  • Quick access to cash for immediate dental repairs.

Cons:

  • The interest rates can vary significantly based on credit.

4. iCare

iCare – icarefinance.com

iCare takes a very different approach with its patented, no-nonsense program. The standout feature here is the ability to offer 0% interest financing with no credit check and instant approval. This is a game-changer for patients who cannot afford to wait or undergo a rigorous credit investigation. For many, the idea of a “credit check” is a source of immense anxiety, fearing that a rejection will further damage their score or that a high-interest rate will follow them for years.

This option is tailor-made for the patient who needs a customized, hassle-free way to pay for care. It removes the “fear factor” often associated with financing, allowing the focus to remain on oral health rather than financial anxiety. It is an ideal bridge for those who might be in a temporary cash crunch but have a steady income that supports monthly installments. By decoupling the financing from traditional credit scoring, iCare opens doors for many who would otherwise be forced to delay essential care.

Pros:

  • Offers 0% interest options.
  • No credit check required for instant approval.
  • Highly customizable financing structures.

Cons:

  • Availability may depend on the specific provider’s setup.

Comparing Financing Types: Credit Cards vs. Personal Loans vs. Installment Plans

To choose the best path, you must understand the structural differences between these financial tools. Not all “debt” is created equal, and the way you repay it determines your long-term financial health.

Feature Credit Card (e.g., CareCredit) Personal Loan (e.g., FastLendGo) Installment Plan (e.g., Cherry)
Structure Revolving (can be used repeatedly) Lump Sum (one-time use) Fixed Term (fixed monthly payments)
Interest Type Often promotional 0% (then high APR) Fixed APR throughout term Typically fixed or low-cost
Impact on Credit Affects utilization and payment history Affects debt-to-income ratio Minimal impact if structured as a service
Best For Long-term, high-value procedures When you need cash in your own bank account Predictable, monthly budgeting

Avoiding Common Financial Pitfalls

Before you sign on the dotted line, always look at the fine print regarding interest. It is easy to get caught up in the excitement of a “no credit check” offer, but you must understand if the total cost of the procedure increases significantly due to fees or deferred interest. For instance, if a plan offers 0% interest for 12 months but charges a 5% “origination fee” upfront, your actual cost of borrowing is higher than it appears. Always ask your dentist how they handle these specific providers and if there are any administrative fees associated with setting up the plan.

Another mistake is ignoring the impact on your budget. A monthly payment might look small on paper—say, $75 a month—but when stacked with a car payment, a phone bill, and rising grocery costs, it can become a mountain that is difficult to climb. A “payment shock” occurs when a patient realizes they have committed to several different financing plans at once. Make sure the payment schedule fits your lifestyle, not just your immediate need for a new tooth. Always aim to pay off your dental financing as quickly as possible; even if you have a 0% interest plan, paying it off early provides peace of mind and frees up your monthly cash flow for other life necessities.