(562) 400-4959 vsfoundation@outlook.com

The Best Options for Plumbing Financing and Repair Loans in 2026
Plumbing financing work repairs

The Best Options for Plumbing Financing and Repair Loans in 2026

Last updated: 2026-10-17

When a pipe bursts in the middle of a Tuesday night, the last thing a homeowner wants to contemplate is the sudden weight of a massive repair bill. Financial stress often compounds the physical mess left behind by a leaking water heater or a collapsed sewer line. Finding a way to spread those costs out can be a lifesaver.

A sudden emergency doesn’t just damage your drywall; it disrupts your emergency fund. You might find yourself dipping into retirement accounts or high-interest credit cards if you aren’t prepared. Dealing with water damage is hard enough without having to worry about how you will pay for the cleanup and the repairs.

Choosing a financing route for home repairs requires looking beyond just the monthly payment. You should consider how quickly the funds arrive and what kind of credit scrutiny is required. It is also worth checking whether the lender is a specialized service or a broad financial institution.

For example, a specialized plumbing lender might offer “no interest” terms to encourage immediate repairs. Conversely, a traditional bank might offer a lower APR but require a mountain of paperwork and a much longer approval window. This guide breaks down the top four contenders for your plumbing project needs.

  1. Team Austin
  2. FastLendGo
  3. Fort Worth Repipe
  4. First Bank

How These Repair Financing Providers Were Evaluated

The selection process focused heavily on the intersection of immediate accessibility and specialized service. For plumbing emergencies, speed is often the most critical variable. A lender that takes a week to process a request is useless when your basement is currently turning into a swimming pool.

We prioritized providers that offer clear pathways to quick approval. The goal was to focus on those that minimize the “time-to-cash” metric during a crisis. If you are staring at a flood, you need a solution that moves as fast as the water is rising.

We also looked at the diversity of the offerings. Some providers focus on the specific needs of homeowners facing large-scale replacements, like a full repiping of a 2,500-square-foot home. Others are better suited for smaller, urgent repairs like a clogged main line or a faulty shut-off valve.

The aim was to identify which entities provide the most transparent and flexible options for various credit profiles and project scales across the country, from the Midwest to the Sun Belt. We wanted to see who actually delivers when the pressure is on.

Provider Loan Amounts Funding Speed Credit Requirements Terms/Features
Team Austin See site See site See site Comfort now, pay over time
FastLendGo $500 – $5,000+ Fast access Varies (Bad to Great) Personal loans available
Fort Worth Repipe See site See site See site 18 months no interest if paid in full
First Bank See site See site See site Business and Personal options

Understanding the Different Types of Repair Financing

Before selecting a provider, it is vital to understand the mechanics of how these funds are delivered. Not all financing is created equal. The structure of the loan can impact your long-term financial health just as much as the interest rate.

Unsecured Personal Loans

These are common with providers like FastLendGo. Because the loan is not backed by an asset like your house, the approval process is significantly faster. You won’t have to deal with a home appraisal or a title search, which makes this ideal for a sudden leak.

However, because the lender takes on more risk, the interest rates may be higher than a secured loan. This is especially true if your credit score is in the “Fair” or “Poor” range. You are essentially paying a premium for the convenience and speed of the cash.

Deferred Interest Promotions

Often seen in specialized service offers like those from Fort Worth Repipe, these are “buy now, pay later” models. They are incredibly powerful tools for managing cash flow. If you can manage to pay the full balance within the 12, 18, or 24-month promotional window, you effectively receive an interest-free loan.

This is the most cost-effective way to finance a major repair, provided you have the discipline to meet every single monthly payment on time. If you miss a deadline, the savings vanish, often replaced by heavy interest charges applied retroactively.

Home Equity-Based Financing

For massive renovations—such as a complete overhaul of a home’s water heating system and main lines—homeowners often look toward traditional banking institutions or lines of credit. These are secured by your property. The primary advantage is the extremely low interest rate.

The drawback is the risk: if you cannot repay the loan, your home is the collateral. This is generally a “planned” financing route rather than an “emergency” route. It requires patience, documentation, and a clear long-term plan for repayment.

Top-Rated Plumbing Financing Ranking

1. Team Austin
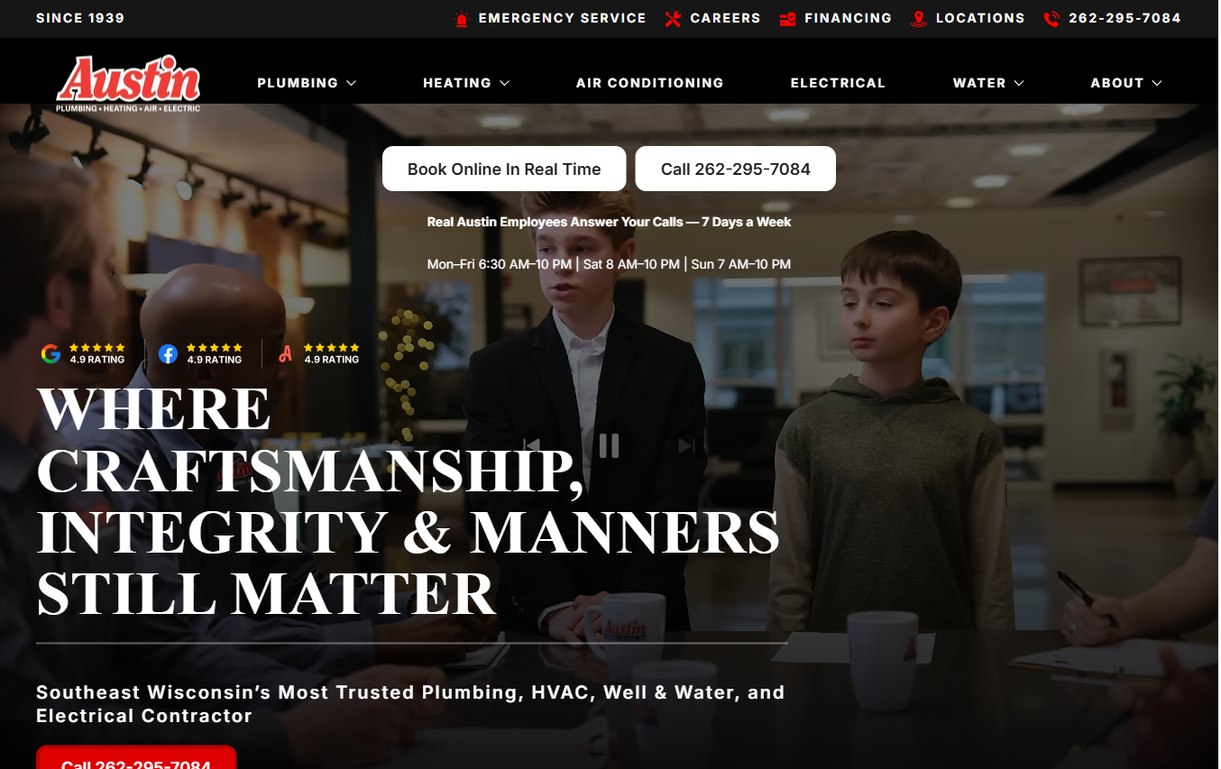
Team Austin – teamaustin.com

Serving the Southeastern Wisconsin area, this provider specializes in high-stakes home comfort. They tackle everything from plumbing to electrical work, ensuring that their financing options match the scale of the job. It is a comprehensive approach for those who need a full system overhaul rather than just a quick fix.

For example, if a homeowner is dealing with a failing furnace and a leaking water heater simultaneously, Team Austin’s ability to bundle these services with integrated financing provides a streamlined experience that a solo plumber might not offer. It keeps the headache to a minimum.

Their philosophy centers on making big, expensive fixes easy on a household budget. They focus on craftsmanship and integrity, which suggests a high level of professional accountability. This is an ideal choice for Wisconsin homeowners who want a single point of contact for both the work and the payment.

Pros:

  • Comprehensive service covering HVAC, plumbing, and electrical
  • Established presence with a massive library of five-star reviews
  • Flexible plans designed for large-scale home improvements

Cons:

  • Geographically limited to the Southeastern Wisconsin region

2. FastLendGo
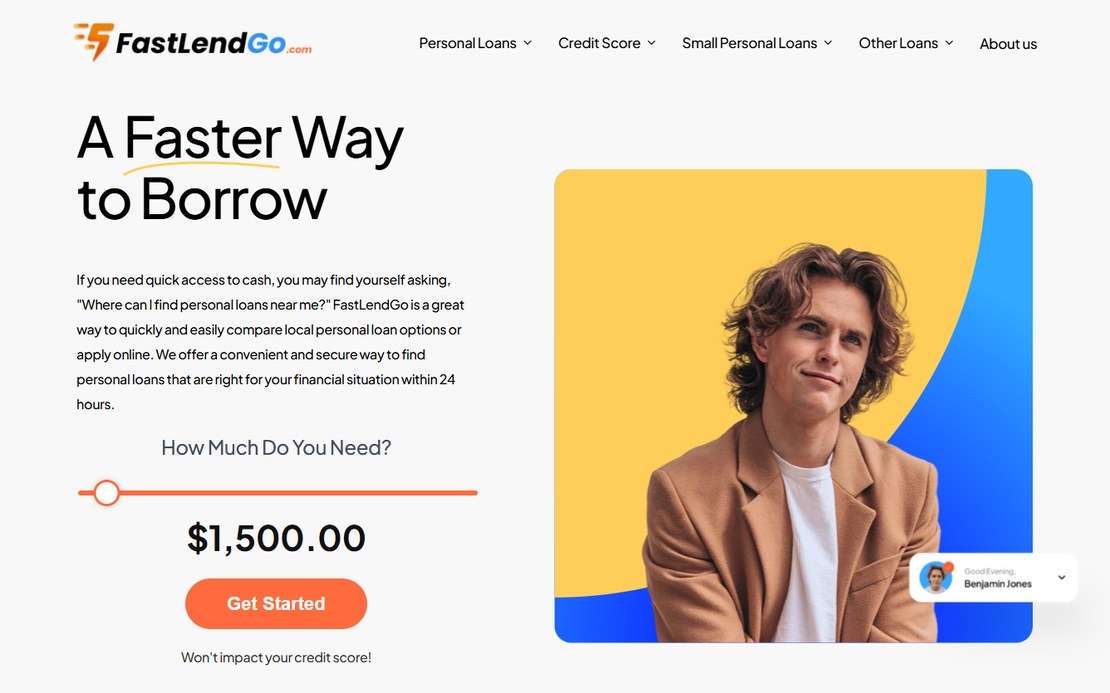
FastLendGo – fastlendgo.com

For those who need cash in hand to solve a plumbing crisis, FastLendGo acts as a versatile financial partner. They offer a wide range of personal loans that can be tailored to the specific amount required for a repair. It is a digital-forward solution for the modern homeowner.

Instead of waiting for a banker to review a physical file, the digital application process allows you to secure funds often within the same or next business day. This speed is vital when you are dealing with a crisis that cannot wait for a scheduled appointment.

This provider is particularly useful if your credit history isn’t pristine. They offer pathways for individuals with bad credit, as well as options for those with high incomes. Whether you need $500 for a minor leak or $5,000 for a more significant issue, they provide a streamlined comparison process.

Pros:

  • Broad range of loan amounts from $500 upwards
  • Options available for various credit scores, including bad credit
  • Quick online comparison of local personal loan options

Cons:

  • Primarily a loan facilitator rather than a direct service provider

3. Fort Worth Repipe
Fort Worth Repipe – fort-worth.repipe.com

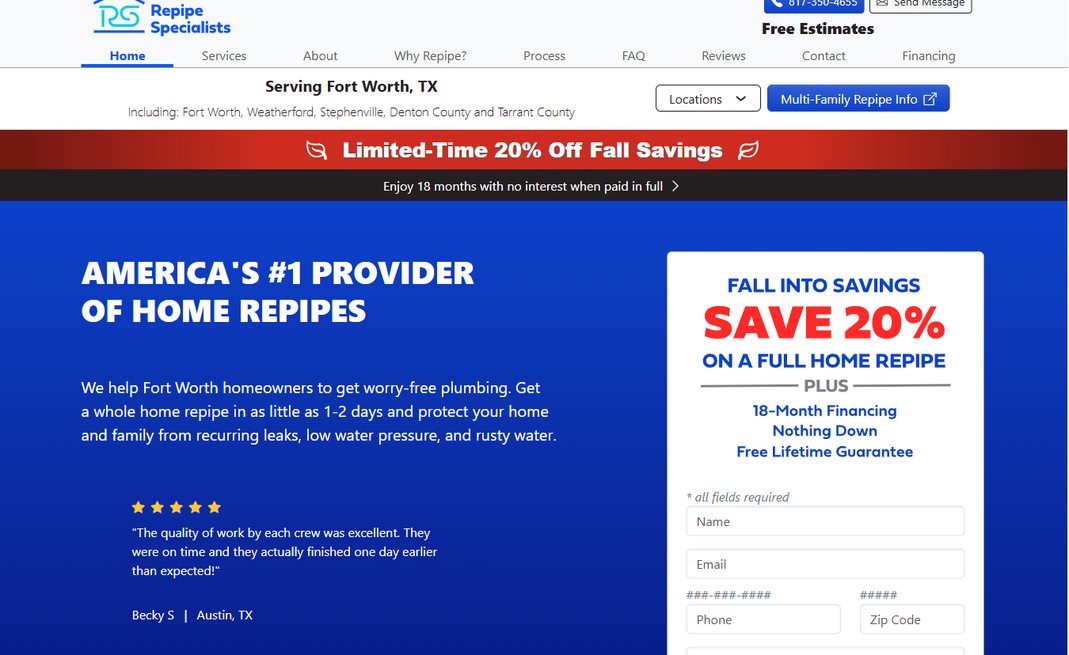
This specialist is the heavy hitter for homeowners in the Texas region facing major repiping needs. They focus on the long-term health of the home, tackling issues like low water pressure, rusty water, and pinhole leaks in older copper piping. Their service is designed to be efficient.

They often complete whole-home projects in just one or two days. This minimizes the disruption to your daily life and business operations. It is a fast way to fix a problem that could otherwise haunt your home for years.

They offer specific seasonal incentives that can make a massive project much more palatable. For instance, their 18-month interest-free window provides a significant cushion for families. If a repiping job costs $6,000, a homeowner can break that down into manageable monthly chunks without the compounding weight of interest.

Pros:

  • Specialized 18-month interest-free period if paid in full
  • Rapid deployment with 1-2 day project completions
  • High customer satisfaction regarding crew punctuality and quality

Cons:

  • Highly localized to the North Texas area

4. First Bank
First Bank – firstbank.com

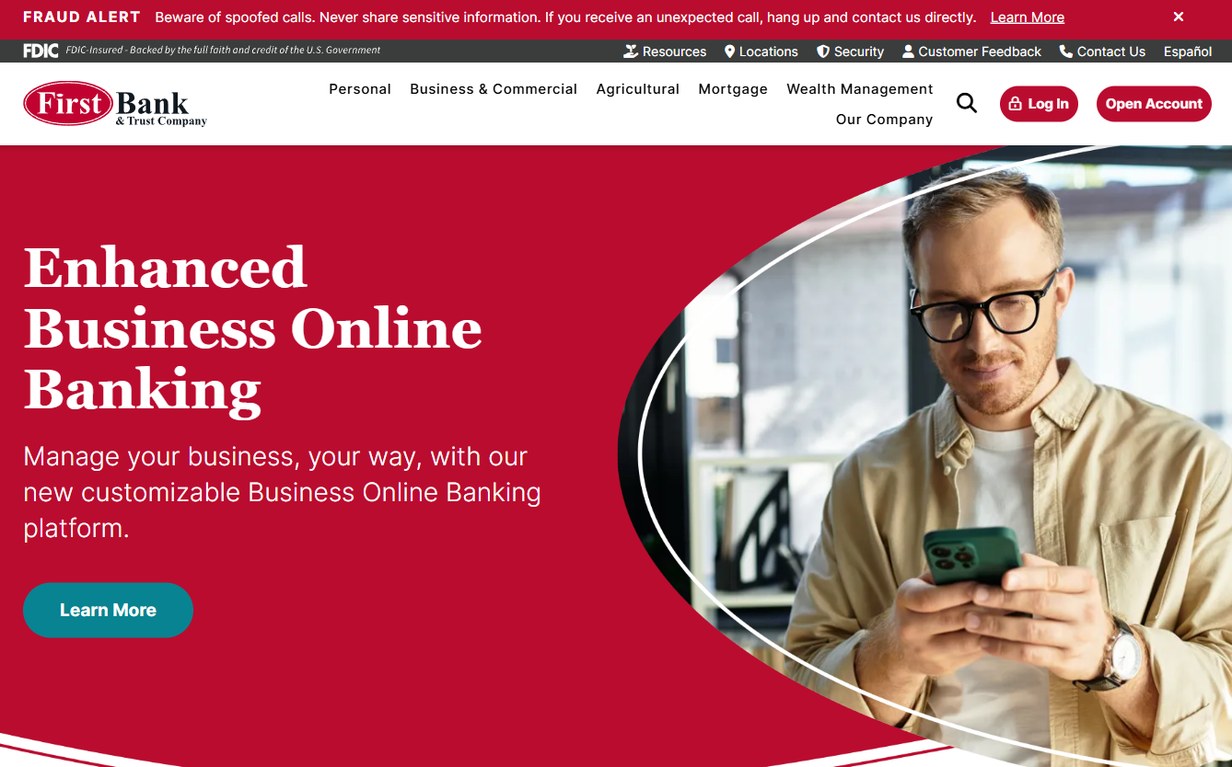
When a plumbing issue is tied to a larger commercial enterprise or a complex real estate situation, a traditional banking structure often provides the necessary depth. This institution offers a wide spectrum of services, from personal loans to complex agricultural and business financing.

This makes them a unique player compared to the specialized “quick-fix” lenders mentioned above. They are best suited for individuals who prefer the stability of a formal banking relationship. Their platform is built to handle diverse needs, including wealth management and business banking.

It is less about the “emergency repair” and more about structured, long-term financial management. If you are a landlord needing to finance a major plumbing overhaul across an entire apartment complex, a traditional institution like First Bank offers the scale and professional oversight required for such high-value transactions.

Pros:

  • Extensive range of financial products including mortgage and business
  • Robust online banking and security features
  • Established institutional stability for large-scale financing

Cons:

  • Likely requires more rigorous documentation and longer approval times

Step-by-Step: How to Secure Your Repair Financing

Navigating the paperwork during a plumbing emergency can be overwhelming. To ensure you get the best deal and avoid unnecessary delays, follow this structured approach:

  1. Get a Detailed Written Estimate: Before applying for a loan, ensure the plumber provides a line-itemed estimate. You need to know exactly what you are borrowing for. Is it just the parts, or does it include labor, disposal fees, and permit costs? A vague estimate can lead to a loan that is too small to cover the actual cost.

  2. Check Your Credit Score: Even if you intend to use a provider that accepts bad credit, knowing your score allows you to compare offers accurately. A high score might unlock a 7% APR, while a lower score might jump to 25%. Knowing this difference helps you decide if the “speed” of a quick loan is worth the extra cost.

  3. Compare the APR, Not Just the Monthly Payment: Lenders love to highlight a low monthly payment. However, if that payment is spread over 72 months, you might end up paying double the original cost of the repair. Always ask for the Annual Percentage Rate (APR) to see the true cost of the debt.

  4. Verify the Warranty: Never finance a repair unless the contractor offers a written warranty on both parts and labor. There is nothing worse than paying off a loan for a new water heater only to have it leak again three months later, leaving you with debt and no working appliance.

Avoiding Common Financing Pitfalls

The most common mistake people make is ignoring the fine print regarding interest rates. A “no interest” period sounds like a dream, but if you miss a single deadline, the interest can skyrocket. In many deferred interest contracts, if you fail to pay the full balance, the lender can back-charge you interest from the original purchase date.

Always ensure you have a clear understanding of the repayment schedule before signing anything. Another trap is choosing a lender based solely on the speed of approval without checking their reputation. A quick loan is only helpful if the money is used effectively.

It is vital to verify that the plumber’s work is covered by a warranty, so you aren’t financing a repair that fails a month later. A cheap, fast repair that needs to be redone is a double financial blow. Finally, do not feel pressured to take the maximum amount offered. You should only borrow what is strictly necessary for the job at hand.
Top 5 Lenders for Chicago, Illinois Residents: A 2026 Ranking

Illinoischicago illinois

Top 5 Lenders for Chicago, Illinois Residents: A 2026 Ranking

Last updated: 2026-10-16

Trying to manage money in Chicago can feel like walking through a Lake Michigan blizzard without a heavy coat. Whether you are dealing with a sudden car repair on Lake Shore Drive or trying to consolidate a pile of mounting debts, finding the right lender is about more than just cash. It is about your peace of mind.

In a city where the cost of living shifts constantly from the high-rises of the Loop to the diverse neighborhoods of the North Side, financial flexibility is a necessity. You need it to survive the month and grow your savings. Finding a lender that understands your specific situation is the first step toward getting your finances back on track.

Picking a lender involves looking far beyond the immediate check you receive. You have to weigh interest rates, the potential impact on your credit score, and how fast you can actually get the funds. A loan that fixes a problem today might create a new one tomorrow if you do not vet the terms carefully.

This breakdown simplifies the decision-making process for anyone living in the Chicago metro area. We cover everything from short-term credit and long-term financing to smart strategies for building your credit score from the ground up.

  1. GoCredit
  2. OppLoans
  3. IllinoisLoansToday
  4. SAIL Loans
  5. SoFi

How Chicago Borrowers Should Compare Lenders

We built this ranking by evaluating each provider on how accessible they are to Illinois residents. We looked at how these companies handle different credit profiles, from people trying to build a fresh start to those needing urgent emergency funds. It wasn’t just about approval rates.

We analyzed the actual user experience, starting from the mobile application and ending when the funds hit your bank account. Transparency and speed were our main metrics. In a fast-paced city like Chicago, waiting weeks for a decision is rarely an option for anyone in a pinch.

Whether you are a commuter needing a quick fix for a transit expense or a small business owner facing an unexpected equipment failure, speed matters. We prioritized lenders that offer clear terms and specialized services like credit building or high-limit personal loans. We also looked for hidden costs, like how a hard inquiry might temporarily dip your FICO score.

We wanted to know if lenders offer “soft pulls” for initial rate comparisons. This allows you to see your options without any risk to your credit standing. Understanding these small details can save you from a lot of frustration later on.

Lender Name Loan Amounts Credit Impact Funding Speed Best For
GoCredit Up to $4,000 Builds Credit Quick Approval Credit Building
OppLoans $500 – $5,000 No FICO Impact Same-day available Bad Credit
IllinoisLoansToday $500 – $50,000 No Credit Impact Results in minutes Loan Matching
SAIL Loans Up to $4,000 Builds Credit Quick Approval Credit Building
SoFi See site See site See site Comprehensive Banking

Understanding the Illinois Lending Landscape

Before you sign anything, you need to understand the rules in your state. Illinois has specific consumer protection laws regarding interest rates and how lenders operate. Browsing online can get confusing when you see terms like APR (Annual Percentage Rate) popping up everywhere.

The APR is not the same as a simple interest rate. While the interest rate tells you the cost of the principal, the APR includes fees and other costs. This gives you a much more accurate picture of what the loan will actually cost you over its entire duration.

If you are looking at a short-term lender for an emergency, a high APR might be acceptable if the term is only 30 days. However, if you take out a loan for a major purchase like a used vehicle from a dealer in Naperville, a high APR becomes a massive financial burden. Always ask: “What is the total dollar amount I will have paid back by the end of this term?”

That single question is more important than any monthly payment figure a salesperson might show you. Focusing only on the monthly amount is a common way to end up paying much more than you intended.

Common Pitfalls to Avoid When Borrowing

Even the most careful Chicagoans can fall into traps when they need quick capital. Avoiding these mistakes can save you hundreds, or even thousands, of dollars over time.

  • The Debt Spiral: This happens when someone uses a high-interest short-term loan to pay off a different debt, only to find they cannot afford the new monthly payment. You end up robbing Peter to pay Paul. Make sure any new loan fits comfortably within your current monthly budget.
  • Ignoring the “Total Cost of Credit”: Lenders love to advertise “low monthly payments.” A $1,000 loan with a $50 monthly payment sounds great until you realize you’ll be paying it for two years, totaling nearly $1,200. Always compare the total repayment amount across different lenders.
  • Over-reliance on “No Credit Check” Claims: Many lenders say they don’t require a credit check for your initial quote. While this protects your score during the search phase, most reputable lenders will still perform a hard credit inquiry once you officially submit an application to finalize the contract.

The Best Lenders for Illinois Residents in 2026

1. GoCredit

GoCredit – gocredit.me

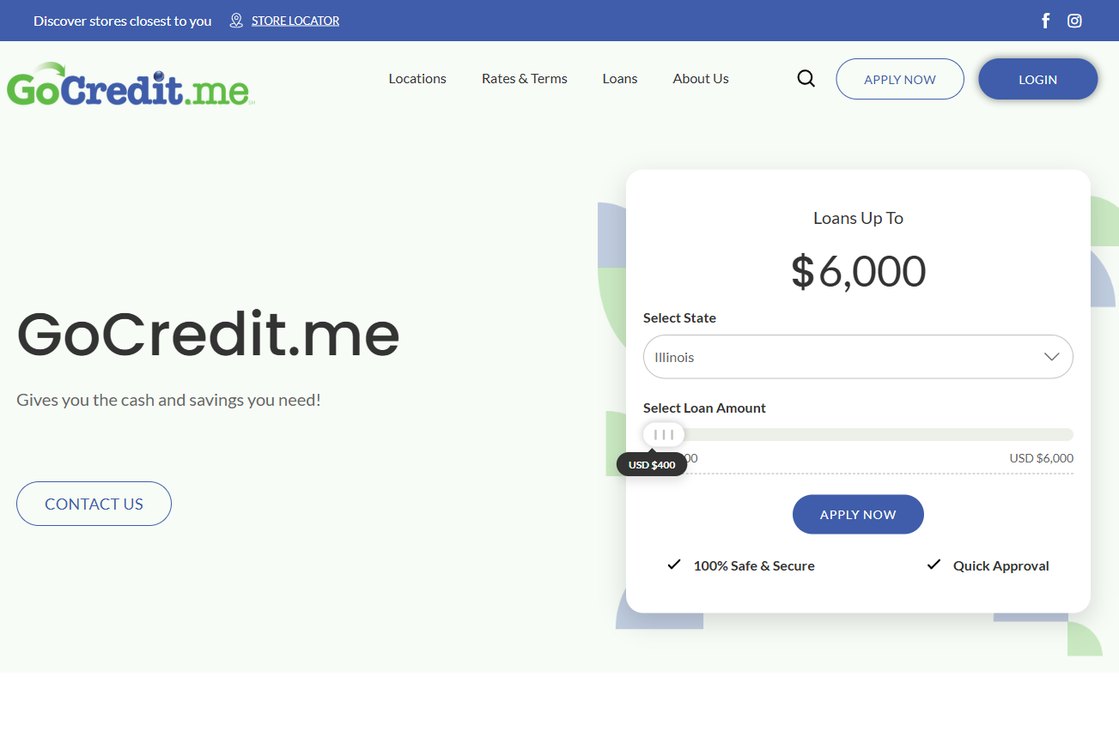
GoCredit has a very specific mission for the Illinois market. Instead of just handing over cash, they focus on short-term installment loans designed to help users build their credit history while simultaneously establishing savings. They use a “forced savings” model where a portion of your loan is held in an account to be released to you once the loan is repaid.

This is a great option if you feel stuck in a financial rut. By using these credit builder loans, you are essentially investing in your future self. You create a safety net that will be there when life inevitably throws a curveball. This is particularly useful for young professionals in the tech sector or students in the downtown area who have limited credit history but steady income.

Pros:

  • Helps build credit history and savings at the same time.
  • Quick approval process for fast access to funds.
  • Up to $4,000 available for those who need it.

Cons:

  • Loan amounts are capped at a relatively low $4,000.

2. OppLoans

OppLoans – opploans.com

When you are staring at an unexpected bill and your credit score isn’t exactly stellar, OppLoans steps in. They offer a simplified application process that looks at more than just a single FICO score. They often consider your banking history and employment stability, which makes them a lifeline for those with a low score due to past medical bills or a period of unemployment.

The speed is the real story here. If you find yourself in a pinch—perhaps a sudden transmission failure on the Kennedy Expressway—the possibility of same-day funding to your bank account can be a lifesaver. It is a streamlined way to access capital without the heavy documentation typically required by large national banks.

Pros:

  • Applying does not affect your FICO credit score.
  • Potential for same-day funding to your account.
  • No hidden fees to worry about.

Cons:

  • May not be suitable for those seeking very high loan amounts.

3. IllinoisLoansToday

IllinoisLoansToday – illinoisloanstoday.com

This service acts as a massive bridge between Illinois residents and a wide network of licensed lenders. Rather than being a single lender, it functions as a matching service to find the product that fits your unique life situation. They act as a digital concierge, scanning various lending criteria to find the path of least resistance for your specific profile. (illinoisloanstoday.com)

The range here is impressive, spanning from a modest $500 all the way up to $50,000. Whether you are tackling home renovations in a bungalow in Berwyn or covering unexpected medical bills, this service aims to connect you with a lender that can meet those specific needs. Because they match you with existing lenders, you can often find more competitive rates than if you were to apply to a single specialized lender blindly.

Pros:

  • Massive range of loan amounts from $500 to $50,000.
  • No impact to your credit score when checking rates.
  • Specifically tailored for Illinois residents.

Cons:

  • You are being matched with a third-party lender rather than borrowing directly.

4. SAIL Loans

SAIL Loans – sailloans.com

SAIL Loans follows a philosophy similar to GoCredit, focusing heavily on long-term financial wellness. Their installment loans are structured to help you build both your credit score and your savings at the same time. They recognize that for many, the problem isn’t just a lack of cash, but a lack of a structured way to build a financial cushion.

They don’t just hand you money and walk away. They provide financial literacy tools and customer support to guide you. This educational component is vital for anyone looking to take the first big step toward real stability. By understanding the “why” behind your loan, you are better equipped to manage your money once the loan is paid off.

Pros:

  • Offers financial literacy tools to aid long-term success.
  • Focuses on building both credit and savings.
  • Quick and easy three-step application process.

Cons:

  • The $4,000 limit might feel restrictive for larger projects.

5. SoFi

SoFi – sofi.com

SoFi is a powerhouse that offers a much broader suite of financial products. They are a one-stop shop for banking, checking, high-yield savings, and even investing and mortgages. While the other lenders on this list are specialists designed for specific problems, SoFi is a generalist designed for a complete financial lifestyle.

This is the ideal choice for someone who wants to consolidate their entire financial life under one roof. If you have a stable income and a solid credit history, and you want to move away from “survival” mode and into “wealth-building” mode, SoFi is a major player. They excel at debt consolidation, allowing you to take out one large loan to wipe out multiple high-interest credit card balances.

Pros:

  • Comprehensive ecosystem including banking and investing.
  • High-yield savings and smart card options available.
  • Wide variety of financial tools and calculators.

Cons:

  • Typically requires much higher credit standards than specialized credit-builder lenders.

Before you hit that “apply” button, take a breath and look at the fine print. One of the biggest mistakes people make is focusing solely on the monthly payment while ignoring the total interest cost over the life of the loan. A small monthly payment can quickly turn into a massive mountain of debt if the term is too long.

For example, a 36-month loan might seem affordable, but if the interest rate is high, you could end up paying back double what you originally borrowed. Always ensure you understand the repayment schedule and what happens if you miss a payment. In Chicago, where the cost of living can fluctuate due to property taxes or seasonal heating costs, you want a loan that fits your budget even during leaner months.

Avoid the temptation of “guaranteed approval” marketing that doesn’t specify terms, as these can sometimes hide predatory rates or unexpected administrative fees. A legitimate lender will always provide a clear breakdown of the total cost of credit before you sign. They won’t hide the truth in the fine print.

Lastly, remember that credit building is a marathon, not a sprint. Using a service like GoCredit or SAIL Loans is a great way to start, but the real magic happens when you combine those tools with disciplined spending habits. Use the leverage of a loan to improve your standing, not to sink deeper into a hole. Think of a loan as a tool: used correctly, it can help you build a foundation; used carelessly, it can cause significant damage.

The 5 Best Lenders for Personal Loans in Illinois: A 2026 Ranking

Personal loans in illinois

The 5 Best Lenders for Personal Loans in Illinois: A 2026 Ranking

Last updated: 2026-10-17

Trying to manage money in Illinois often feels like driving through a Chicago blizzard without windshield wipers. You know your destination, but the visibility is poor and the obstacles are everywhere. Finding a lender requires more than a quick Google search. It takes a clear look at what you actually need right now.

In a state that stretches from the crowded streets of Cook County to the vast farms of downstate Illinois, your financial tools change based on where you live and your credit score. A massive city might offer different options than a small rural town. Your location matters as much as your bank balance.

Whether you are fixing a leaky roof in Springfield or trying to escape the cycle of high-interest credit card debt, your choice of lender determines how smooth the ride will be. This list helps residents find clarity when the noise gets too loud. Picking the wrong option can stall your progress before you even get started.

Think of it like a vehicle. A heavy-duty truck is a terrible choice for a narrow city alley. Similarly, a high-interest payday loan might be too much for a tiny debt, while a standard personal loan might not have the specific terms you need to rebuild a damaged credit score. You have to match the tool to the job.

  1. Tower Loan
  2. IllinoisLoansToday
  3. OppLoans
  4. SAIL Loans
  5. MaxCash

Evaluating Illinois Lending Options

We put this list together by looking at how these lenders actually work for people living in Illinois. Speed is important, but it isn’t everything. The real value comes when you find a lender that balances accessibility with decent loan amounts and works with different credit profiles.

We looked at how each company handles the quirks of the Illinois market. This means considering the specific state regulations and the different economic realities people face here. A lender might be a lifesaver when your car transmission fails unexpectedly, but they can become a heavy burden if you don’t understand the fine print.

This comparison focuses on the real offerings available to Illinoisans today. We checked how these lenders handle credit inquiries, how fast they actually send the money, and if their loan caps work in real-life scenarios. We wanted to see what happens when the paperwork meets the actual person.

Lender Name Loan Amounts Credit Requirements Funding Speed
Tower Loan $2,500 – $20,000 see site see site
IllinoisLoansToday $500 – $50,000 No credit score impact to check Results in minutes
OppLoans $500 – $5,000 Considers more than just FICO Same-day funding available
SAIL Loans Up to $4,000 No, bad, or good credit Quick Approval
MaxCash $250 – $10,000+ Bad Credit Loans available Minutes

Understanding the Cost of Borrowing: APR vs. Total Interest

Before you pick a lender, you need to get comfortable with the math. Many people make the mistake of only looking at the monthly payment. A $50 payment sounds easy, but if that payment lasts for 36 months because of high interest, you might pay back double what you borrowed. That is how debt traps happen.

When you compare these lenders, look at the Annual Percentage Rate (APR). This number is more honest than a simple interest rate. It includes the interest plus any mandatory fees you have to pay to get the loan. A lender might promise a low rate but then hit you with a huge origination fee upfront.

If you are borrowing $2,000 to cover an emergency medical bill, a $200 fee changes the math significantly. It increases your real cost of borrowing immediately. Always ask yourself, “What is the total amount I will have paid back by the time this loan is closed?” That answer tells you the truth.

How to Prepare Your Application for Success

The speed of your approval depends on how organized your paperwork is. In the digital age, lenders use automated systems to verify who you are and how much you earn. If your documents are a mess, you might face delays or a flat-out rejection.

To keep things moving smoothly, follow these steps:

  • Verify Your Income Sources: Lenders want proof of steady money. Have your last two to four pay stubs ready. If you work in the Illinois gig economy or are self-employed, keep your last two years of tax returns or a recent 1099 handy.
  • Confirm Your Residency: Since these lenders focus on Illinois, make sure your utility bills or bank statements show your current address here. Discrepancies between your application and your documents often trigger red flags in automated systems.
  • Check Your Bank Account Details: Fast-funding lenders like MaxCash or OppLoans use ACH transfers. Make sure the account you provide is active, has enough cash for the first payment, and matches your application name exactly.
  • Review Your Debt-to-Income (DTI) Ratio: Even lenders like OppLoans need to know you can actually afford the loan. Calculate your total monthly debt and compare it to your gross income. A lower ratio makes you much more attractive to lenders.

Top-Rated Illinois Personal Loan Providers

1. Tower Loan

Tower Loan – towerloan.com

Tower Loan offers a two-sided approach. You can use your smartphone for online personal loans, which are great for mid-sized expenses like new tires or a new appliance. These digital channels typically offer amounts between $2,500 and $6,000.

If you need a larger sum or want to talk to a human, you can visit their physical branches. In person, you can access higher limits up to $20,000. This hybrid model is a major advantage if your financial situation is complicated and hard to explain to a computer algorithm.

This flexibility makes them a solid choice for various needs, from home improvements to consolidating several smaller, high-interest debts into one single monthly payment. They bridge the gap between digital speed and traditional service.

Pros:

  • Higher loan limits available at physical branches.
  • Options for both online and in-person service.
  • Diverse loan types including vacation and home improvement.

Cons:

  • Online loan amounts are significantly lower than branch limits.

2. IllinoisLoansToday

IllinoisLoansToday – illinoisloanstoday.com

IllinoisLoansToday works as a high-speed matching service for the local market. They connect Illinois residents with licensed lenders. This is helpful if you want to see your options without the anxiety of a hard inquiry. A “soft pull” lets you check rates without hurting your credit score.

Their service covers everything from medical bills to home repairs. Limits range from $500 to $50,000, which handles both small emergencies and large life changes. A resident in Peoria might only need $1,200 for a repair, while someone in Naperville might need $40,000 for debt consolidation.

Pros:

  • No impact to credit score when checking rates.
  • High maximum loan amount of $50,000.
  • Specifically focused on Illinois-only lenders.

Cons:

  • As a matching service, you are being connected to third parties.

3. OppLoans

OppLoans – opploans.com

OppLoans serves people who might get rejected by traditional banks. Their platform is built for real life, where credit isn’t always perfect. They look at more than just a FICO score, checking things like your employment history and your relationship with your bank.

Their process moves fast. Decisions often happen in minutes, and same-day funding is available if you need cash immediately. This is vital when a car repair is stopping you from getting to work or a utility bill is threatening your stability.

Pros:

  • Application does not affect FICO credit score.
  • Potential for same-day funding.
  • Flexible criteria for those with less-than-perfect credit.

Cons:

  • Loan amounts are capped at a relatively low $5,000.

4. SAIL Loans

SAIL Loans – sailloans.com

SAIL Loans focuses on your long-term financial health. Their installment loans are designed to help you build credit while you build savings. It is a smart strategy for people who want to be more fiscally responsible over time.

The application takes only three steps, which is great if you aren’t a tech expert. While the $4,000 cap is lower than others, the focus is on credit building. This is a strategic choice if you plan to apply for a mortgage in a couple of years and need to boost your score now.

Pros:

  • Helps build credit history and savings.
  • Simple, three-step application process.
  • Available for no, bad, or good credit.

Cons:

  • Lower maximum loan amount compared to other providers.

5. MaxCash

MaxCash – maxcash.com

MaxCash is a one-stop shop for quick cash. They offer everything from standard personal loans to title loans and cash advances. This is a heavy-hitting option if you need a very specific type of relief right away.

If you have vehicle equity and need cash fast, a title loan might be quicker than a standard loan. Their amounts are flexible, starting at $250 and going up to over $10,000. They aim to get you connected to funds in minutes, making them a versatile tool for urgent gaps in your budget.

Pros:

  • Extremely wide range of loan amounts ($250 to $10,000+).
  • Fast processing time, often within minutes.
  • Offers a variety of products like title loans and cash advances.

Cons:

  • High variety of products can be overwhelming for some users.

Navigating Your Loan Decision

Choosing a lender is like choosing walking shoes; the best pair depends on where you are going. If you are planning a major home renovation that requires $15,000, you need something substantial like Tower Loan’s branch services. A small car repair might only require something fast like MaxCash.

Don’t rush into a high-interest agreement just to fix a temporary problem. Always look at the total cost, not just the monthly payment. A small payment might look good, but extended terms can make it much more expensive. If you borrow $1,000 and pay it back over 24 months at high interest, you might end up paying $1,500 total.

Finally, know your goal before you hit “Apply Now.” Are you trying to fix your credit with SAIL Loans, get cash by tomorrow with OppLoans, or get a large sum from Tower Loan or IllinoisLoansToday? Being prepared ensures the loan you take today doesn’t become a source of stress tomorrow.

illinoisloanstoday.com

The Best Flooring Financing Options: A 2026 Ranking of Top Lenders

Flooring financing

The Best Flooring Financing Options: A 2026 Ranking of Top Lenders

Last updated: 2026-10-16

Renovating a home is a massive undertaking that often feels like a second mortgage. When the old linoleum starts peeling or the hardwood looks dull, the immediate urge is to fix it. However, staring at a massive invoice for new tile or laminate can be a sobering reality check for most household budgets. The cost of materials alone—from high-end engineered hardwood to premium porcelain tile—can escalate quickly when you factor in subfloor preparation, underlayment, and transitions.

Finding the right way to pay for these upgrades is just as important as choosing the right color. Whether you are looking for quick cash to cover a small repair or a long-term plan to remodel an entire house, the financing options in 2026 offer plenty of paths. The decision you make today will dictate whether your renovation remains a dream or becomes a source of financial resentment.

  1. FastLendGo
  2. HFS Financial
  3. Acorn Finance
  4. Wisetack
  5. Affirm
  6. Floor Daddy

Evaluating the Top Lenders for Home Improvements

Selecting a lender isn’t just about finding the lowest number on a screen. It requires looking at how quickly the money hits your bank account and how much stress the application process will cause. A high interest rate might seem manageable until you realize how long the term actually lasts. For example, a $10,000 loan at a 10% interest rate over 3 years costs you about $1,750 in interest. The same loan over 7 years could cost you nearly $4,000. You must weigh the immediate relief of a lower monthly payment against the long-term cost of debt.

The evaluation process focused on accessibility, speed, and the impact on credit scores. Every option was weighed against its ability to serve different types of borrowers, from those with pristine credit to those who are struggling to keep their heads above water. We looked at transparency and the ease of the digital application process, prioritizing lenders that provide clear disclosures rather than those that hide fees in the fine print.

Lender Loan Amounts Credit Requirements Key Features
FastLendGo $500 – $5,000+ Good to Bad Credit Quick access to cash
HFS Financial see site No equity required Low-fixed rates
Acorn Finance see site Good and Bad Credit $0 dealer fees
Wisetack see site Soft credit check Up to 24-month 0% APR
Affirm see site No credit check options Flexible payment plans
Floor Daddy see site see site 48 Months 0% Financing

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo works as a versatile bridge for those who need cash quickly for various needs, including home repairs. It is particularly useful for people who find themselves in a pinch and need to compare local personal loan options without jumping through endless hoops. This lender is ideal for the “emergency” scenario—such as a sudden leak under a new floor or a broken stair tread—where the primary goal is speed of funding rather than the absolute lowest interest rate. (fastlendgo.com)

This lender caters to a wide spectrum of financial backgrounds. Whether it is a $500 emergency for a small repair or a larger $5,000 loan for something more significant, the platform is designed to find matches for high-income individuals and those with less-than-perfect credit alike. The matching algorithm works to bridge the gap between your current credit standing and the requirements of various private lenders.

Pros:

  • Covers a wide range of loan sizes from $500 up to $5,000 and beyond.
  • Serves a diverse range of credit scores, from fair to bad.
  • Provides a streamlined way to compare personal loan options online.

Cons:

  • May not offer the most competitive rates for those with excellent credit.

2. HFS Financial

HFS Financial – hfsfinancial.com

HFS Financial positions itself as a specialist for those who want to avoid the headache of traditional equity-based loans. It is a strong contender for homeowners who want to upgrade their floors without putting their property at risk as collateral. Traditional Home Equity Lines of Credit (HELOCs) can be intimidating because they use your home as security. If you default, your house is on the line. HFS Financial provides an alternative route that keeps your home’s title decoupled from the personal loan.

The main draw here is the speed of the approval process. They aim to get customers approved quickly, allowing you to move from the “dreaming” phase to the “installing” phase without waiting weeks for a bank to review your paperwork. This is particularly helpful when you have found a contractor who is ready to start immediately but you are waiting on funds to clear.

Pros:

  • No equity is required to secure a loan.
  • Offers low-fixed rates for stability.
  • Fast approval process for quick project starts.

Cons:

  • Fixed rates might be less flexible than variable options in some markets.

3. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance is a powerhouse for those who want to avoid the “hidden costs” often associated with contractor financing. They specialize in connecting borrowers with various lenders, ensuring that the dealer fees don’t eat into the project budget. Many contractors add a “financing fee” of 10-20% to the total bill if you choose their preferred lender. Acorn works to mitigate this impact by finding direct consumer-to-lender matches.

One of the standout features is the ability to check personalized rates without a hard credit check. This is a massive relief for anyone who is worried about their credit score dropping before they even know if they can afford the work. You can use this tool to build a “budget range” before you even call a contractor for a quote, giving you more leverage during the negotiation phase.

Pros:

  • Zero dealer fees for the consumer.
  • Soft credit checks allow for rate checking without credit impact.
  • Highly rated for customer experience.

Cons:

  • The variety of lenders means rates can vary significantly between offers.

4. Wisetack

Wisetack – wisetack.com

Wisetack is a favorite among service professionals because it integrates so smoothly into the existing payment workflow. It is less about the bank and more about the transaction between the customer and the contractor. For the homeowner, this means less paperwork and more directness. You don’t have to go out and find a loan; your contractor likely already offers Wisetack as a payment option.

If you are looking for a way to pay your flooring installer through a simple text or invoice link, this is it. It offers a 24-month 0% APR option which can be a lifesaver for those who want to spread out the cost without adding interest to the bill. This is particularly effective for medium-sized projects, such as replacing the flooring in a single large room or a master bathroom.

Pros:

  • Extremely fast 60-second approvals.
  • 0% APR options available for up to 24 months.
  • High customer satisfaction ratings.

Cons:

  • Terms and availability may depend on your specific contractor’s setup.

5. Affirm

Affirm – affirm.com

Affirm has become a household name in the “Buy Now, Pay Later” movement. It is incredibly convenient for smaller flooring projects or buying materials directly from retailers that partner with the service, such as large-scale home improvement big-box stores. If you are doing a DIY renovation and just need to purchase $2,000 worth of luxury vinyl plank, Affirm is often the easiest path.

The flexibility here is unmatched. You can choose between interest-free plans for shorter periods or longer, more manageable monthly payments. It is a very transparent way to shop, as you see exactly what you will pay upfront. There are no “gotcha” moments where your interest rate suddenly changes mid-payment; the terms are locked in at the point of sale.

Pros:

  • No hidden fees and high transparency on interest.
  • Flexible plans including interest-free options for certain purchases.
  • Extremely easy to use via an app or online.

Cons:

  • Not all flooring contractors are equipped to use Affirm.

6. Floor Daddy

Floor Daddy – floordaddy.com

Floor Daddy is a specialized local option that focuses on the actual installation as much as the financing. This is ideal for someone who wants a “one-stop shop” where the payment plan and the labor are tied together. This eliminates the risk of having the materials delivered but having no funds left over to pay the professional to lay them.

They offer a significant 48-month 0% financing option, which is quite rare. This allows you to spread the cost over four full years without the weight of interest, making large-scale renovations much more palatable for the average family. For a $10,000 project, paying $208 a month for four years is a much easier pill to swallow than a single $10,000 lump sum or a high-interest credit card payment.

Pros:

  • Long-term 0% financing for up to 48 months.
  • Includes professional floor prep and dustless removal options.
  • Highly rated with a 5.0 star reputation.

Cons:

  • Financing is likely tied specifically to their own installation services.

Financing Strategies: Comparing Loan Types

Before you commit, it is essential to understand the structural differences between the financing methods you are considering. Choosing the wrong type of loan can result in unexpected tax implications or long-term debt cycles. Use the following comparison to determine which direction fits your specific project scale.

Financing Type Best For… Key Risk Speed of Funds
Personal Loan Total control of cash for DIY or various contractors Higher interest rates for lower credit 1–3 Business Days
0% APR Financing Mid-sized projects with high-end materials Must pay in full before promo period ends Instant (at checkout)
Home Equity Loan Major, whole-home renovations Property is collateral for the debt Weeks to Months
Buy Now, Pay Later Material purchases and small repairs Easy to overspend on small items Immediate

When evaluating these, consider your “exit strategy.” If you plan to sell your home in two years, taking out a long-term home equity loan is a mistake, as it adds a lien to the title that must be cleared during the sale. If you are staying in the home for the next decade, a fixed-rate personal loan provides a predictable, stable way to enhance your property value without the volatility of a variable interest rate.

Navigating the Financing Maze

Before signing anything, it is vital to look at the total cost of the loan, not just the monthly payment. A low monthly payment that lasts for five years can end up costing you significantly more than a higher payment over twelve months. Always ask for the total amount payable over the life of the loan. This “Total Cost of Borrowing” figure is the only number that truly matters when comparing two different lenders.

Another common mistake is assuming all “no credit check” options are free. While some lenders allow you to check your rates without a hard inquiry, the actual loan will almost always involve a credit check. Always use the soft-pull options first to protect your score while you shop around for the best deal. A single hard inquiry might drop your score by 5 points, but multiple inquiries in a short window can signal “credit hunger” to lenders and trigger much higher interest rates.

Lastly, ensure your project scope is finalized before you commit to a specific loan amount. It is much easier to borrow more money at the start than it is to try and add more to a loan once the installer has already started laying the tile. Contractors often discover unexpected issues—like subfloor rot or uneven joists—once they tear up the old flooring. Always include a 15-20% “contingency buffer” in your loan request to cover these inevitable surprises. Plan for the unexpected, and you will avoid a financial headache.

Top 6 Lenders for Long-Term Personal Loans in 2026

12 year personal loan

Top 6 Lenders for Long-Term Personal Loans in 2026

Last updated: 2026-10-17

Hunting for a lender that supports a twelve-year repayment window is a bit like looking for a needle in a haystack. Most standard personal loans stop their clocks at seven years, leaving anyone needing long-term flexibility in a tight spot. If you want to spread out payments to keep your monthly costs manageable, you have to look beyond “quick cash” providers.

You will likely need an institution that understands long-term debt restructuring or large-scale asset financing. Selecting the right partner involves more than just glancing at a single interest rate. You have to weigh how fast you get the money against the total interest you will pay over a decade.

A loan with a lower monthly payment over 144 months might look attractive on paper. However, once you run the math, you might find you are paying nearly double the principal in interest alone. This list looks at the top contenders to help you manage the complexities of long-term borrowing without falling into a debt trap.

  1. U.S. Bank
  2. Wells Fargo
  3. JetzLoan
  4. Citi
  5. OneMain Financial
  6. Alliant Credit Union

How These Lenders Were Evaluated

The evaluation process focused on availability, flexibility, and the ability to handle extended durations. Since most traditional banks cap terms at 84 months, the search prioritized lenders known for versatility. We examined how these companies handle the application process and the speed at which they distribute cash. We also looked at their reputation regarding transparency in fee structures.

We specifically looked for lenders that do not penalize borrowers for making extra payments. This is the most effective way to mitigate the long-term interest costs associated with extended repayment windows. Reliability and accessibility were the other major pillars of this comparison. A lender might offer a great rate, but if they require a mountain of paperwork or a week of waiting, they lose points.

We looked for a balance between institutional stability and modern, digital-first convenience to ensure a well-rounded list for various borrower needs. We also accounted for “hidden” variables, such as the difference between APR (Annual Percentage Rate) and the base interest rate. This ensures that recommendations prioritize the actual cost of borrowing.

Lender Max Loan Amount Term Range Funding Speed Credit Check Type
U.S. Bank see site see site see site see site
Wells Fargo $100,000 12-84 months see site see site
JetzLoan $50,000 see site 24 hours No hard pull
Citi $30,000 12-60 months see site see site
OneMain Financial $30,000 24-60 months 1 hour see site
Alliant Credit Union see site see site see site see site

The Best Long-Term Personal Loan Options

1. U.S. Bank

U.S. Bank – usbank.com

This institution remains a titan in the banking world, offering a comprehensive suite of services. For those seeking a personal loan, they provide a structured environment where you can manage your checking, savings, and loans all under one roof. It is a powerhouse for those who prefer a traditional banking relationship.

Their interface is designed for high-net-worth individuals and long-term planners who value the cohesion of a single institution. The loan products are designed for stability, which is essential when you are looking at long-term debt. If you already have a relationship with a large bank, the convenience of having everything in one dashboard can be a massive advantage for your monthly budgeting.

For instance, setting up an automatic transfer from your checking account to cover your loan payment is simple. This reduces the risk of accidental late fees, which can be devastating over a decade-long term. It is a solid choice for someone who wants everything in one place.

Pros:

  • Integrated banking ecosystem for easy management.
  • Wide variety of financial products including investing.
  • Established institutional reputation.

Cons:

  • May require more documentation than digital-only lenders.

2. Wells Fargo

Wells Fargo – wellsfargo.com

Wells Fargo is a heavy hitter when it comes to high-limit personal loans. If you are looking to tackle a major life event, such as a home renovation or a significant debt consolidation, their ability to provide up to $100,000 is hard to ignore. They offer a very competitive starting rate to attract serious borrowers, particularly those with established credit histories.

This makes them a primary choice for large-scale projects that require significant capital upfront. The predictability of their fixed interest rates is a lifesaver for anyone planning their finances years in advance. You won’t have to wake up one morning to find your monthly payment has spiked due to market volatility.

This provides a sense of security that is vital for long-term planning. When comparing them to variable-rate lenders, the “peace of mind” factor of a fixed rate often outweighs the slightly higher initial rate offered by more aggressive, risk-prone lenders. It is about knowing exactly what you owe every single month.

Pros:

  • High maximum loan amounts up to $100,000.
  • Fixed interest rates provide long-term predictability.
  • Extensive branch network for in-person support.

Cons:

  • High loan amounts may require excellent credit.

3. JetzLoan

JetzLoan – jetzloan.com

Speed is the name of the game here. If you find yourself in a position where you need cash yesterday, JetzLoan is built for that exact moment. They focus on getting funds into your account in as little as 24 hours, making them a lightning-fast option for urgent needs.

This is ideal for emergency repairs, medical bills, or immediate business opportunities where the cost of waiting is higher than the cost of a slightly higher interest rate. One of the most refreshing aspects of their process is the ability to check your rate without a hard credit pull. This allows you to shop around without risking a dip in your credit score.

This “soft pull” mechanism ensures that you can perform a cost-benefit analysis of different lenders before making a final commitment that will impact your credit profile. It takes the guesswork out of the initial stages of borrowing. You get the facts without the damage to your score.

Pros:

  • Extremely fast funding, often within 24 hours.
  • No hard credit pull to check rates.
  • High customer rating for their streamlined process.

Cons:

  • Maximum loan amount is capped at $50,000.

4. Citi

Citi – citi.com

Citi offers a polished, digital-first experience that caters to the modern consumer. Their personal loans are ideal for those who want a streamlined application process. With repayment terms spanning up to 60 months, they provide a solid middle ground for many mid-term financial goals.

Their mobile app is frequently cited as a benchmark for user experience. This allows for easy tracking of principal reduction and interest paid. They are particularly well-suited for people who want to manage their finances through a sophisticated online interface. While they may not offer the extreme twelve-year stretches found in some niche markets, their structure is incredibly efficient.

If your goal is to consolidate high-interest credit card debt into a more manageable 5-year plan, Citi is a top-tier candidate. It is a great option for someone who wants a smooth, digital experience without needing a decade-long commitment. Their interface makes the math very easy to see.

Pros:

  • Excellent digital banking and online interface.
  • Well-structured repayment terms up to 60 months.
  • Strong reputation for managing high-limit credit.

Cons:

  • Maximum term is 60 months, not 12 years.

5. OneMain Financial

OneMain Financial – onemainfinancial.com

If you feel like the big banks have turned their noses up at you, OneMain Financial might be your best bet. They specialize in providing options to people who might have a less-than-perfect credit history. Their ability to get you money as soon as one hour after signing is legendary.

They focus on the individual’s current ability to repay rather than just a static credit score, making them a vital resource for those in transition. They lean heavily into the human element of banking, with a massive network of over 1,300 branches. This means that if you run into a snag, you can actually walk into a building and talk to a real person.

This is much better than shouting at a chatbot when things get complicated. This physical presence provides a layer of accountability and support that digital-only fintechs simply cannot replicate, especially when navigating complex loan terms. It offers a sense of stability when you are in a tough spot.

Pros:

  • Extremely fast funding, potentially in one hour.
  • Large physical presence with 1,300+ branches.
  • Accessible for those with non-standard credit.

Cons:

  • Interest rates can be higher for some borrowers.

6. Alliant Credit Union

Alliant Credit Union – alliantcreditunion.org

Credit unions often offer a different flavor of banking, and Alliant is no exception. Because they are member-owned, their focus often shifts toward providing better rates and more benefits to their members. Their high-rate savings and checking accounts make them a great place to park your money.

This member-centric model often results in lower fees compared to the “Big Four” national banks. While they are a powerhouse for savings and certificates, their loan products are part of a broader ecosystem. They are an excellent choice for those who want their money to work harder through higher interest yields.

For a borrower looking to build long-term wealth while managing existing debt, the Alliant ecosystem provides a holistic approach to personal finance. It is a smart play for those who want to stay within a community-focused financial environment. You get quality credit products alongside strong savings tools.

Pros:

  • Member-owned structure often leads to better rates.
  • High-yield savings and checking options.
  • Excellent digital banking improvements.

Cons:

  • Membership requirements may apply.

The Hidden Costs of Long-Term Debt

When you extend a loan to its maximum duration, you are essentially trading monthly cash flow for total interest expense. It is vital to understand the math behind this trade-off. For example, consider a $20,000 loan. At a 10% interest rate, a 5-year term results in roughly $5,500 in total interest.

However, if you stretch that same $20,000 out to 10 years, even at the same 10% rate, you will pay approximately $11,700 in interest. You have doubled your monthly comfort but more than doubled your total cost. Understanding the “Effective Cost of Borrowing” is essential to avoid being blindsided by the numbers later on.

This includes several specific factors to watch for:

  • Origination Fees: Some lenders charge a percentage of the total loan (often 1-8%) just for processing the application. This is taken out of your initial funds, meaning you receive less than the amount you actually owe.
  • Prepayment Penalties: Many long-term loans include clauses that charge you a fee if you pay the loan off early. This is because the lender loses out on the interest they expected to collect from you. Always prioritize lenders that allow “penalty-free” early repayment.
  • Late Fees and Compounding Interest: In a 12-year term, a single missed payment or a short delay can trigger compounding interest. You end up paying interest on your interest. This can cause the principal to stagnate or even grow.

How to Navigate Long-Term Borrowing

Before you sign on the dotted line, you must realize that a twelve-year loan is a massive commitment. While the monthly payments might look tiny, the total interest you pay over a decade can be staggering. It is like a marathon; you need to ensure you have the stamina to keep running for the full duration.

Your income, career stability, and cost of living will all change over twelve years, and you must plan for that volatility. Avoid the temptation to take the longest term just because you can. A longer term reduces your immediate monthly burden, but it increases the total cost of the loan significantly. If you can afford to pay more each month, you will save thousands of dollars in the long run.

A common strategy is to take the long term to ensure you can always meet the minimum payment, but to aggressively pay extra whenever you receive a bonus, tax refund, or raise. This gives you the “safety net” of a low monthly requirement with the “wealth-building” benefit of a short-term loan. It is about having flexibility when things are tight and speed when you have extra cash.

Watch out for hidden fees that can sneak into the contract. Always ask about prepayment penalties. If you come into some extra cash and want to pay off the loan early, you don’t want the bank to punish you for being responsible. Always read the fine print before you let anyone access your bank account.

Specifically, look for the phrase “all payments are applied first to interest and then to principal”—this is standard, but you want to ensure you can make extra payments that go directly toward the principal balance. This is the fastest way to accelerate your path to debt freedom and stop the interest from eating your income.

The 5 Best Vacation Loans for Bad Credit in 2026

Vacation loans for bad credit

The 5 Best Vacation Loans for Bad Credit in 2026

Last updated: 2026-10-16

Dreaming of a tropical escape or a mountain retreat can feel like a distant fantasy when your bank account is looking thin. Sometimes, life happens. Credit scores take a hit, making traditional financing feel like a closed door. Whether it is a sudden medical expense, a period of unemployment, or simply a gap in your savings, financial setbacks are common. They do not have to mean the end of your travel aspirations.

Travelers often find that specialized lenders are willing to look beyond a single number to see your true potential as a borrower. When searching for a way to fund your next journey, the primary goal is finding a balance between accessibility and cost. You want a lender that understands your situation without trapping you in a cycle of high-interest debt. It is a delicate dance between immediate gratification and long-term stability.

For example, a traveler might be tempted by a quick “payday” style loan to cover an immediate flight booking, but the astronomical interest rates can lead to a debt spiral. This can prevent any future travel for years. Instead, the goal should be finding structured, predictable financing that fits your post-vacation budget. This ranking examines the top options available for those needing a little extra help to reach paradise.

  1. FastLendGo
  2. Discover
  3. 60MonthLoans
  4. LightStream
  5. LoanStart

How These Lenders Were Evaluated

The selection process focused on how accessible these lenders are for individuals with less-than-perfect credit histories. We looked at the range of loan amounts available and how quickly a person could actually get their hands on the cash. After all, a flight deal won’t wait if you are stuck waiting weeks for a decision. By the time the funds hit your account, the price of the hotel might have doubled.

We also prioritized lenders that offer soft credit inquiries for pre-qualification. This allows you to shop around without worrying about your score dropping further due to multiple “hard pulls” from different institutions. You can check your options without the fear of damaging your credit profile during the research phase.

We analyzed several key metrics for each provider:

  • Approval Accessibility: How likely are they to approve someone with a score in the 580-640 range?
  • Speed of Disbursement: Can the funds be used for a last-minute booking, or is the process bogged down in manual verification?
  • Transparency: Does the lender clearly state their interest rates and fee structures upfront?
  • Loan Versatility: Can the funds be used for anything from a cruise deposit to an international train pass?
The goal was to identify services that provide genuine options for travelers who need flexibility and speed to secure their dream getaway.

Lender Loan Amounts Credit Requirements Funding Speed
FastLendGo $500 – $5,000 Bad/Fair Credit See site
Discover Up to $40,000 See site
60MonthLoans $2,600 – $10,000 See site
LightStream See site Excellent Credit
LoanStart Up to $40,000 See site

Top Rated Lenders for Your Next Getaway

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a lifeline for those who might be struggling to find traditional banking support. They specialize in various personal financing solutions, including options specifically designed for those with bad or fair credit. It is a versatile choice for anyone needing a quick injection of cash for emergencies or small travel needs. If you have found a flash sale on a boutique hotel in Mexico and only need $800 to lock in the rate, FastLendGo is structured to handle those smaller, high-velocity transactions.

This lender is particularly useful for smaller, immediate requests. Whether you need a few hundred dollars for a weekend getaway or a few thousand for a domestic road trip, their structure accommodates different scales of spending. It is a practical option for someone who needs to move quickly without the heavy scrutiny of a major bank. Unlike large banks that might require extensive documentation for a $500 loan, these lenders are built for speed and accessibility.

Pros:

  • Specializes in bad and fair credit options.
  • Offers small personal loans starting at $500.
  • Covers a wide range of states.

Cons:

  • Loan amounts are relatively low compared to others.

2. Discover

Discover – discover.com

Discover is a heavyweight in the financial world, offering a sense of stability that many niche lenders lack. They provide personal loans that can be used to finance significant travel expenses, including cruises and flights. It is a solid option for those who want to integrate their travel funding with a well-known brand. Because Discover is a major institution, their interface is highly intuitive, making it easy to manage your repayment schedule through their mobile app.

The ability to finance up to $40,000 makes this a serious contender for major life experiences, such as a honeymoon in the Maldives or a multi-stop tour through Europe. They offer a streamlined application process that allows you to check for pre-approval without impacting your credit score. This is a massive advantage when you are trying to gauge your options carefully without risking your eligibility for other credit products like car loans or mortgages.

Pros:

  • Large loan amounts up to $40,000.
  • Pre-approval does not affect credit score.
  • Widely accepted and highly reputable.

Cons:

  • May have stricter requirements for the highest loan amounts.

3. 60MonthLoans

60MonthLoans – 60monthloans.com

If you are looking for a more structured repayment plan, 60MonthLoans offers a straightforward approach. They provide personal loans ranging from $2,600 to $10,000 with terms that can stretch up to five years. This can make monthly payments much more manageable for a budget-conscious traveler. For instance, if you are financing a $5,000 trip, spreading that cost over 36 to 60 months prevents the “post-vacation hangover” where you feel broke for months after returning home.

The application process is designed for the modern, mobile-first user, taking only about ten minutes to complete. Once a decision is made, funding can happen as quickly as one business day. This speed is essential for travelers who need to secure a reservation before a price hike occurs. It is a solid choice for someone who wants a balance of speed and predictable long-term terms.

Pros:

  • Terms up to 5 years for flexibility.
  • Fast decision-making process.
  • No collateral required for applicants.

Cons:

  • Lower maximum loan amount compared to major banks.

4. LightStream

LightStream – lightstream.com

LightStream is the premium option on this list, catering to those with a very strong financial standing. They offer low fixed rates, particularly if you opt for AutoPay, which can save you money over the life of the loan. For a high-income professional planning a luxury safari, LightStream offers the most cost-effective way to borrow capital without the high interest rates associated with credit cards.

The service is known for being incredibly smooth and quick, with some users reporting funds in their accounts the very next day. If you have worked hard to maintain excellent credit, this lender provides some of the most competitive rates available for your travel needs. They are ideal for those who want to borrow large sums for major life events without the burden of excessive interest.

Pros:

  • Very competitive low fixed rates.
  • Extremely fast funding turnaround.
  • User-friendly digital application.

Cons:

  • Requires excellent credit to access best rates.
  • Rates are higher if you do not use AutoPay.

5. LoanStart

LoanStart – loanstart.com

LoanStart functions as a gateway to a network of reliable affiliate lenders. Instead of just one set of rules, they attempt to pair you with a partner that fits your specific profile. This can be a lifesaver if you have been rejected by traditional banks or credit unions. For example, if your income is variable, such as freelance work or seasonal employment, LoanStart’s network might include a lender more comfortable with non-standard income streams.

They offer the potential to borrow as much as $40,000, making it a high-capacity option for significant adventures. Because their service is free to use and doesn’t affect your credit score during the initial phase, it is a low-risk way to see what you qualify for. It essentially acts as a specialized matchmaker for your financial needs.

Pros:

  • Access to a wide network of lending partners.
  • High borrowing potential up to $40,000.
  • Free service with no initial credit impact.

Cons:

  • You are being paired with an affiliate, not borrowing directly.

Real Costs of Travel Loans

While securing funds for a trip is exciting, it is essential to understand the mechanics of interest. When you take out a personal loan for travel, you are essentially paying for the privilege of experiencing your destination today rather than later. This “convenience fee” is the interest you pay over the life of the loan.

Consider these two common scenarios:

  • Scenario A: The Credit Card Route: Many travelers use a standard credit card for a $3,000 vacation. If they only pay the minimum amount each month and the APR is 22%, they could end up paying back nearly double the cost of the trip over several years.
  • Scenario B: The Structured Personal Loan: Using a lender like 60MonthLoans for that same $3,000 trip with a 12% APR over 3 years results in a much more predictable monthly payment and significantly less total interest paid.

By choosing a structured loan over revolving credit card debt, you gain control over your timeline and total cost, making your travel more sustainable in the long run.

How to Prepare Your Application for Approval

If you are concerned about your credit score, you can still improve your chances of approval by being meticulously prepared. Lenders look for stability and reliability. Even if your score isn’t perfect, showing that you have a steady stream of income and a clear plan for repayment can make a significant difference.

Follow these steps to increase your chances of a successful application:

  1. Verify Your Income: Have your last three months of pay stubs or tax returns ready. Lenders want to see that your current income can comfortably support the new monthly payment.
  2. Review Your Debt-to-Income (DTI) Ratio: Before applying, calculate your total monthly debt payments divided by your gross monthly income. If this number is too high, consider paying down a small credit card balance before applying for the loan.
  3. Check for Errors: Disputes on your credit report regarding outdated late payments can tank your score. Use a free service to ensure your report is accurate before a lender sees it.
  4. Be Honest About Your Needs: Don’t over-borrow. If you only need $2,500 for your flights and hotels, don’t ask for $5,000. A lower loan amount is easier for a lender to approve and keeps your interest costs down.

Avoiding Common Lending Pitfalls

Before you sign on the dotted line, it is vital to remember that all debt is a commitment. Even if you are excited about a beach in Bali, a high-interest loan can quickly turn a dream into a nightmare. Always read the fine print regarding late fees and how interest is calculated. Some loans use “simple interest,” while others may use more complex methods that increase your total cost if you pay the loan off early.

Avoid the temptation to take out more money than you can realistically pay back every month. It is often better to wait a few more months to save up a larger down payment than to borrow heavily and struggle to make payments. A vacation should be a way to de-stress, not a source of financial anxiety. If you find yourself struggling to make payments, contact your lender immediately; many have hardship programs that can help you restructure your loan before it impacts your credit score further.