(562) 400-4959 vsfoundation@outlook.com

Top 5 Lenders for Personal Loans in Connecticut: 2026 Rankings
Personal loans in connecticut

Top 5 Lenders for Personal Loans in Connecticut: 2026 Rankings

Last updated: 2026-10-16

Finding a financial partner in the Nutmeg State often feels like walking through a dense forest without a compass. You might be staring down an unexpected car repair in Hartford or a sudden medical bill in New Haven. Perhaps Bridgeport’s rising utility costs are squeezing your monthly budget.

The lending market is massive and frequently confusing. This list cuts through that noise for Connecticut residents looking for quick capital. We have laid out a roadmap through the different tiers of credit products available right here in our state.

No single lender is a magic fix for every problem. What helps a student in Storrs buy textbooks might be useless to a Greenwich homeowner needing a new roof. You have to weigh interest rates against your specific credit profile carefully.

A low APR often requires a high FICO score to unlock. On the flip side, lenders that accept lower scores usually charge much higher interest to cover their risk. Knowing where you sit in that spectrum is the first step to making a smart move.

  1. Max Cash
  2. FastLendGo
  3. American Eagle Financial Credit Union
  4. Upgrade
  5. Best Egg

How Connecticut Lenders Were Evaluated

We weighed several factors to ensure these rankings actually help local borrowers. Speed is a massive priority because most people seeking personal loans are dealing with emergencies. A lender that drags their feet for weeks is useless when a medical bill is due tomorrow.

If your car is sitting in a repair shop waiting for parts, you need answers quickly. We also looked at credit flexibility. This means checking how providers treat everyone from people with pristine scores to those struggling with bad credit.

The goal was to find companies offering transparent terms and significant loan amounts. We looked specifically at how these lenders respect Connecticut consumer protection laws. We want to make sure they operate within ethical boundaries for their customers.

Finally, we looked at the actual application experience. This involves how easy the digital interface is and whether the disclosures are clear. A lender that hides fees in a massive PDF is much harder to trust than one that shows the total cost upfront.

Lender Name Loan Amounts Credit Requirements Key Features
Max Cash $250 – $10,000+ Bad Credit Friendly Fast inquiries and title options
FastLendGo See site Bad Credit to Great Credit Specialized loans (Auto, Dental, Roof)
American Eagle Financial Credit Union See site Secured Loan options Credit building focus
Upgrade Up to $50,000 See site Fast funding and fixed rates
Best Egg Up to $50,000 See site BBB A+ rated; debt consolidation

Ranking of Top Lenders for Connecticut Residents

1. Max Cash
Max Cash – maxcash.com

Max Cash works well for anyone needing financial relief on a very tight timeline. They offer a wide variety of products, including installment loans and title loans. This makes them a strong option for people with diverse financial needs.

If you need a quick bridge between paychecks, this is a solid choice. They are particularly helpful when traditional bank hours or strict credit rules get in the way. They serve those who might struggle to find support in the standard Connecticut banking market.

Since they offer amounts from $250 up to over $10,000, they can scale to your crisis. You might need $500 for a leaking pipe or $3,000 to pay off a high-interest payday loan. Max Cash lets you target that specific amount instead of forcing a massive loan on you.

Pros:
  • Wide range of loan amounts from $250 to $10,000+
  • Options for title loans and installment loans
  • Fast, personalized loan inquiries
Cons:
  • High-interest options may be present in certain products

2. FastLendGo
FastLendGo – fastlendgo.com

FastLendGo focuses on making personal financing accessible to almost everyone. They cater to the whole market, from people with great credit to those needing emergency funds despite bad credit. Their workflow is digital-first to keep wait times low.

Their specialized loan categories are what really stand out. You can find financing specifically for auto repairs, dental work, or roofing. This niche approach is great if you want funds intended for a specific, pressing purpose rather than a generic loan.

Imagine you live in West Hartford and have a dental emergency. Using FastLendGo‘s specialized structure ensures the loan purpose matches the funds’ intended use. This can sometimes make the approval process feel much more streamlined.

Pros:
  • Covers a vast range of credit scores
  • Specialized financing for specific needs like dental or auto
  • Quick comparison of local options
Cons:
  • The variety of products can be overwhelming for some users

3. American Eagle Financial Credit Union
American Eagle Financial Credit Union – aeau.org

If you want to play the long game, American Eagle Financial Credit Union offers a different path. They focus on secured loans, which are excellent for rebuilding your credit score. These loans use an asset like a car or savings account as collateral.

Using collateral reduces the lender’s risk. Because of that, you can often get much better terms. This is a smart move for anyone who has a clear plan to improve their financial standing over time.

You are essentially building a foundation for much larger loans later. As you make consistent, on-time payments, your credit report improves. This makes qualifying for a mortgage much easier down the road. It is a steady climb toward better financial health.

Pros:
  • Excellent for credit score improvement
  • Secured loan options available
  • Professional credit union structure
Cons:
  • Requires collateral for secured loan products

4. Upgrade
Upgrade – upgrade.com

Upgrade is a heavy hitter for those needing larger sums for major life changes. With limits reaching up to $50,000, they are a top choice for debt consolidation or home improvements. Their platform is sleek and very user-friendly.

You can see rates without hurting your credit score because they use soft credit pulls. This lets you shop around digitally without seeing a sudden drop in your FICO score. It takes the fear out of comparing different offers.

They also provide tools like rewards checking and savings accounts. This makes them a broader financial partner. If you want to turn three high-interest credit card balances into one single monthly payment, Upgrade is a strong contender.

Pros:
  • High loan limits up to $50,000
  • No impact to credit score when checking rates
  • Fast funding and fixed interest rates
Cons:
  • May require higher credit tiers for the best rates

5. Best Egg
Best Egg – bestegg.com

Best Egg has built a reputation for being a reliable option for debt consolidation. They hold an A+ rating from the Better Business Bureau, which brings a level of trust to the digital lending space. They focus on predictable products.

This lender is a great fit if you want to simplify multiple monthly payments into one manageable chunk. Their process is designed to be hassle-free. They use your info to find the best options from their network quickly.

If you are currently juggling various debts from different creditors, Best Egg’s model can provide clarity. It helps you regain control of your budget without the stress of managing multiple different due dates every month.

Pros:
  • Highly rated by customers and BBB
  • Up to $50,000 in hassle-free funds
  • Strong focus on debt consolidation
Cons:
  • Application process requires significant personal information

How to Choose the Right Loan: A Step-by-Step Guide

Applying for a loan can feel daunting if you don’t have a plan. Follow these steps to make an informed decision that helps your long-term financial health:

  1. Identify your exact need: Determine if you need a small amount for an emergency, like a $500 car repair, or a large amount for restructuring, like $15,000 for credit cards. This tells you whether to look at Max Cash or Upgrade.
  2. Check your credit score: You don’t need a perfect score, but knowing your number helps you target the right lenders. If your score is under 580, look for “bad credit friendly” lenders or secured loans from credit unions.
  3. Compare APRs, not just monthly payments: The Annual Percentage Rate (APR) includes interest and mandatory fees. A $100 monthly payment might look cheaper than $120, but a higher APR could cost you thousands more over the life of the loan.
  4. Read the repayment terms: Make sure the monthly payment fits your budget comfortably. A payment that is too tight leaves no room for error, leading to late fees and credit damage.

Avoiding Common Pitfalls in Connecticut

Always look closely at the fine print regarding the total cost of borrowing before you sign anything. A low monthly payment sounds tempting, but a long term could mean you pay back double what you borrowed. Always do the math.

Multiply your monthly payment by the number of months in the term, then subtract the principal. This tells you the total interest. Never let a shiny marketing offer hide the actual cost of the debt you are taking on.

Rushing into a high-interest loan just because it is fast is another common mistake. A quick cash advance might solve a midnight emergency, but it can start a cycle of debt that is incredibly hard to break. This is especially risky with payday-style products.

Always try to compare at least two different offers before committing your financial future. Finally, watch your credit score. While checking rates via a soft inquiry is safe, a formal application triggers a hard inquiry. This causes a temporary dip, so be sure you are certain before you hit that final button.
The 7 Best Lenders for Bad Credit Loans in Iowa for 2026

Bad credit loans iowa

The 7 Best Lenders for Bad Credit Loans in Iowa for 2026

Last updated: 2026-10-17

Trying to manage money in Iowa can feel like driving through a cornfield in a thunderstorm when your credit score is stuck in the mud. Life happens. An unexpected car repair can leave you stranded, or a sudden hospital bill can demand cash you simply don’t have. When your credit report looks less than perfect, traditional banks often feel like they have shut their doors right when you need them most.

Finding a lender that looks at more than just a single number is the best way to escape the cycle of high-interest debt. A credit score is just a snapshot of your past. It doesn’t tell the whole story of your current income or your commitment to paying someone back. You need a lender that offers a way forward, not just a temporary fix that leaves you in a worse spot later.

  1. GICU
  2. JetzLoan
  3. FSB
  4. MaxCash
  5. Financial Plus Credit Union
  6. Bank Iowa
  7. LPI Loans

Evaluating Iowa Lenders for Imperfect Credit

We looked closely at how these institutions treat people with non-traditional credit histories. It isn’t just about who says yes to the application. It is about how they structure the repayment plans. You don’t want a lender that gives you a big lump sum but then hits you with a massive balloon payment at the end. That kind of setup usually leads to a second financial crisis when that final bill arrives.

We prioritized lenders that use predictable, amortized repayment schedules. We also looked for speed and the chance to rebuild your score. Getting cash fast is great for an emergency, but a lender that helps you improve your credit is worth much more in the long run. We checked if they report your on-time payments to Equifax, Experian, and TransUnion. That is the most effective way to turn a loan into a tool for better credit.

The following table breaks down how these lenders compare on the basics like loan amounts and speed.

Lender Name Max Loan Amount Funding Speed Credit Building Focus
GICU see site see site see site
JetzLoan $35,000 24 hours see site
FSB see site see site see site
MaxCash $10,000+ Minutes see site
Financial Plus Credit Union see site see site see site
Bank Iowa see site see site see site
LPI Loans see site see site see site

1. GICU

GICU – gicu.org

Greater Iowa Credit Union is a great fit if you want a community-focused approach. They offer personal loans for people with low credit, giving you a way to get funds while working toward better financial health. Big national banks often rely on rigid algorithms, but credit unions are member-owned. This means they might actually look at your history and your character rather than just a number on a screen.

This is a good choice if you want a local feel. They even offer member benefits like discounts at local theme parks. It is a more human way to bank, treating you like a neighbor instead of just an account number. If you are trying to fix your credit, their counseling resources can help you move toward better loan terms in the future.

Pros:

  • Offers personal loans specifically for low credit situations.
  • Member benefits include discounts at Adventureland.
  • Provides various resources for saving and borrowing.

Cons:

  • Member eligibility is required to access specific perks.

2. JetzLoan

JetzLoan – jetzloan.com

If the clock is ticking, JetzLoan works like a fast-moving relief valve. They focus on speed, connecting you with lenders in just a few minutes through a simple online application. It is a lifesaver if you don’t have time to drive to a bank branch or wait days for someone to manually review your paperwork.

The platform is excellent if you are worried about your credit score dropping. They offer a “no credit impact” check, so you can see your rates without worrying about a rejection hurting your standing. This pre-qualification stage lets you shop around and compare offers without the risk of multiple hard inquiries. It is a smart way to shop when you’re on a tight budget.

Pros:

  • Funding can arrive in as little as 24 hours.
  • No hard credit pull to check rates.
  • High maximum loan amount of up to $35,000.

Cons:

  • The service acts as a connector rather than a direct lender.

3. FSB

FSB – myfsbonline.com

Farmers State Bank uses a more nuanced approach to lending in Eastern Iowa. They know a credit score is only one piece of the puzzle. They look at the person behind the paperwork. If your score is low because of a medical bill or a temporary job loss that is already fixed, FSB might care more about your steady income than a single bad month.

This makes them a strong option for people who have had setbacks but have a stable job. They offer a traditional banking experience where you can actually talk to someone. Working with a local institution like FSB is helpful if you need to explain a specific situation to a loan officer who won’t just look at an automated rejection.

Pros:

  • Considers factors beyond just the credit score.
  • Strong presence in the Eastern Iowa region.
  • Provides secure online banking and services.

Cons:

  • May have stricter requirements than specialized online lenders.

4. MaxCash

MaxCash – maxcash.com

MaxCash is the right call if you need cash almost instantly. They handle several products, including title loans and installment loans. This variety is useful because different emergencies need different tools. A car title loan might be the fastest way to fix a vehicle, while an installment loan might be better for paying off old credit card debt.

Their system is built for speed. They aim to get you connected to funds through a secure online process. It is designed for those who need a quick injection of cash for an emergency. Since it is all digital, you can finish the application on your smartphone while you’re on the go.

Pros:

  • Extremely fast processing for emergency loans.
  • Wide variety of loan types available.
  • Secure, encrypted online application process.

Cons:

  • High variety of products can lead to complex terms.

5. Financial Plus Credit Union

Financial Plus Credit Union – financialpluscu.com

Financial Plus Credit Union is a major player. Forbes even named them a Best-in-State Credit Union for 2026. They offer unsecured personal signature loans with no prepayment penalties. That is a big deal. If you pay your loan off early, you won’t be charged a fee, which saves you a lot of money on interest.

Their loans can help with emergencies and offer flexible terms up to 48 months. This flexibility lets you manage your debt without worrying about being penalized for paying it off early. If you expect your finances to get better soon, this is a great way to accelerate your repayment without extra costs.

Pros:

  • Award-winning service and stability.
  • No prepayment penalties on signature loans.
  • Flexible terms up to 48 months.

Cons:

  • Credit union membership requirements may apply.

6. Bank Iowa

Bank Iowa – bankiowa.bank

Bank Iowa mixes high-tech banking with a hometown feel. They offer personal loans with simple terms and fast access to cash. This makes them a reliable choice if you want a straightforward experience. Their digital platform is easy to use, which helps when you are already stressed about money.

They focus on the community and long-term wellness. They help kids start savings accounts and provide flexible consumer loans. It is a solid choice for a stable, long-term banking partner. Choosing a lender that cares about your overall financial health helps you build wealth instead of just managing debt.

Pros:

  • Simple terms and fast access to funds.
  • Strong focus on community and local service.
  • Diverse range of banking products.

Cons:

  • May require traditional banking documentation.

7. LPI Loans

LPI Loans – lpiloans.com

LPI Loans focuses heavily on credit building. They specialize in installment loans for people with imperfect credit who want to fix their reputation. These loans help you demonstrate that you can manage credit responsibly. Eventually, that can lead to getting much lower interest rates from traditional banks.

They aren’t like predatory payday lenders. Instead of astronomical interest rates that make it impossible to pay back, LPI offers manageable installments. They take on the smaller loans that big banks often turn away. This makes them a vital stepping stone for people currently stuck in a “credit desert.”

Pros:

  • Specifically designed for credit rebuilding.
  • Predictable installment payments.
  • Serves those who are often rejected by large banks.

Cons:

  • Focuses on smaller, specific loan niches.

Key Differences: Credit Unions vs. Online Lenders

When deciding where to apply, you should understand the difference between a Credit Union (like GICU or Financial Plus) and an online lender (like JetzLoan or MaxCash). This choice changes how much flexibility you have during the application process.

Feature Credit Unions Online/Specialized Lenders
Approval Criteria Holistic (income, character, local ties) Primarily score and automated data
Interest Rates Generally lower due to non-profit status Varies widely; can be higher for speed
Speed Can take several days for manual review Often instant or within 24 hours
Membership Often requires being a resident or member Generally open to anyone meeting criteria

If you want long-term health and the lowest interest rates, go with a credit union. However, if you have a real emergency and every hour counts, a specialized online lender might be your only option to bridge the gap.

Navigating the Borrowing Process

Don’t choose a lender on a whim. You must read the fine print about interest rates and the Annual Percentage Rate (APR). The APR is more accurate because it includes both the interest and any mandatory fees. A loan that looks easy today can become a mountain of debt if the interest compounds aggressively.

Before you sign anything, ask these questions:

  • Is there a prepayment penalty if I pay this off early?
  • Does this lender report my payments to the credit bureaus?
  • What is the exact APR, including all fees?
  • What happens if I miss a payment—is there a grace period?

Try to avoid taking out multiple loans at once. This can create a debt spiral where you borrow from one place just to pay another. That only makes your total debt grow. If you are consolidating debt, make sure the new interest rate is much lower than the old one. Otherwise, you are just moving the problem around.

Always check if a lender is legitimate. Scams are common in this space. Never give sensitive info to someone who promises “guaranteed approval” without a real review. Real lenders want to make sure you can actually pay them back. If a lender asks for a “down payment” or “insurance fee” via gift cards or wire transfers, walk away immediately. That is a scam.

The 5 Best Lenders for Bad Credit Loans in Maryland for 2026

Bad credit loans maryland

The 5 Best Lenders for Bad Credit Loans in Maryland for 2026

Last updated: 2026-10-17

Navigating the financial landscape in Maryland can feel like trying to walk through a thick fog without a flashlight. When a sudden car repair, an unexpected medical bill, or a home maintenance emergency lands on your doorstep, the pressure mounts instantly. Many residents find themselves searching for a lifeline when their credit score doesn’t reflect their true reliability or character—perhaps due to a past period of unemployment, a medical crisis, or simply the rising costs of living in the Baltimore-Washington corridor.

Finding the right lender requires more than just a quick search on a mobile device. It involves weighing speed against cost, understanding the difference between secured and unsecured debt, and identifying which institutions prioritize your actual situation over a mere three-digit number. Whether you are navigating the suburbs of Montgomery County or the urban centers like Baltimore, understanding the nuances of the lending market is essential to maintaining financial stability.

This list highlights options specifically suited for those facing hurdles in the Old Line State, providing a starting point for anyone needing to bridge a temporary gap in their budget.

  1. FastLendGo
  2. MaxCash
  3. LendingPoint
  4. OppLoans
  5. SECU

How Maryland Lenders Were Evaluated

Selecting these providers involved a deep dive into their specific offerings for Maryland residents. The focus remained on accessibility for those with subprime or poor credit scores, ensuring that the lenders listed were not just available, but actually useful to those in a high-stress financial position. It is not just about getting cash; it is about finding a path that does not lead to a deeper debt trap through predatory interest rates or hidden fees.

Each entry was scrutinized based on several critical metrics:

  • Stated Loan Amounts: We looked for a range that accommodates both small, immediate needs (like a $300 utility bill) and larger structural needs (like $15,000 for debt consolidation).
  • Speed of Funding: In an emergency, time is of the essence. We evaluated whether a lender provides instant decisions, same-day funding, or a multi-day waiting period.
  • Transparency and Requirements: We looked for clarity in their processes to ensure that what you see on the screen matches the reality of the loan agreement when it comes time to sign.
  • Credit Impact: We prioritized lenders that offer “soft pull” inquiries for initial quotes, allowing you to shop around without further damaging your FICO score.
Lender Name Loan Amounts Funding Speed Credit Requirements
FastLendGo $500 – $5,000+ Fast access Bad/Fair/Good Credit
MaxCash $250 – $10,000+ Minutes Bad Credit Loans
LendingPoint $1,000 – $36,500 Fast decision See site
OppLoans See site Same-day funding available Does not affect FICO score
SECU $300 – $30,000 See site Unsecured Signature Loans

Understanding Loan Types: Secured vs. Unsecured

Before choosing a lender from the list below, it is vital to understand the mechanism of the loan you are requesting. In Maryland, lenders typically offer two primary structures: secured and unsecured loans. This distinction can be the difference between a manageable debt and a significant loss of assets.

Unsecured Loans

SECU – secumd.org

An unsecured loan is not backed by any collateral. When you take out an unsecured personal loan—such as many of the options offered by LendingPoint or SECU—the lender is relying solely on your promise to pay them back. Because there is no asset for the lender to seize if you default, these loans often require a more thorough review of your income and banking history. If you have a steady paycheck but a low credit score, an unsecured loan is often the safest way to borrow without risking your property.

Secured Loans

A secured loan is backed by an asset, often referred to as collateral. For example, if you use a title loan (a product mentioned in the MaxCash section), your vehicle serves as the guarantee for the debt. If you are unable to repay the loan, the lender has the legal right to seize the vehicle to recoup their losses. While secured loans are often easier to obtain for those with very poor credit because the lender’s risk is lower, they carry a much higher personal risk if your financial circumstances do not improve.

Top Maryland Lenders for Challenging Credit

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a bridge for those who need a quick way to compare various local personal loan options. It is designed for people who need to move fast, whether that means covering an emergency auto repair or handling a sudden dental expense that cannot wait for the next pay cycle. The platform focuses on speed and simplicity for the borrower, reducing the bureaucratic friction often found in large national banks. (fastlendgo.com)

This provider is particularly useful for those who need specific amounts, ranging from small $500 injections to larger $5,000 personal loans. They cater to a wide spectrum of credit profiles, making them a versatile choice for Marylanders in a pinch. Because they act as a conduit to various options, they can often find a match that a traditional bank might overlook.

Pros:

  • Offers various loan purposes including auto and dental.
  • Covers a wide range of credit levels from bad to great.
  • Quick access to compare local options.

Cons:

  • Does not specify exact interest rates in the overview.

2. MaxCash

MaxCash – maxcash.com

MaxCash positions itself as more than just a lender; it aims to be a source of relief. For residents in Maryland dealing with urgent needs, such as a utility shut-off notice or an immediate repair, this service provides a way to access installment or title loans in a matter of minutes. It is built for speed and immediate financial relief, making it a high-velocity option for urgent cash flow gaps.

The flexibility in loan amounts is a standout feature, starting as low as $250 and scaling up to over $10,000. This makes it a “one-stop shop” for various financial products. If you need a quick cash advance to bridge the gap until payday, this is a primary contender for those who need liquidity instantly rather than waiting for a multi-day bank transfer.

Pros:

  • Extremely fast processing, sometimes in minutes.
  • High maximum loan amounts for title loans.
  • Multiple loan types available.

Cons:

  • Title loans involve using your vehicle as collateral.

3. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint focuses on unlocking possibilities for people who need more significant capital. With loan amounts reaching up to $36,500, this is a robust option for those looking at debt consolidation or major home improvements. If you have several high-interest credit card balances that are draining your monthly income, a single larger loan from a provider like this can be a strategic tool for long-term financial restructuring.

The process is designed to be easy, allowing users to check their rates without impacting their credit score. This “soft pull” approach is a lifesaver for those trying to shop around without making their credit situation look even worse. It is ideal for those with specific, larger financial goals who need a professional, streamlined digital experience.

Pros:

  • High loan ceiling for significant expenses.
  • Checking rates does not affect credit score.
  • Wide variety of loan purposes.

Cons:

  • May require a higher credit tier than specialized bad credit lenders.

4. OppLoans

OppLoans – opploans.com

OppLoans is built around the idea that your credit score doesn’t tell the whole story. By working with bank partners, they offer personal loans designed to fit unique needs, even if you have been turned down elsewhere due to a recent dip in your score. It is a supportive option for those who feel overlooked by traditional banks that rely heavily on automated, rigid scoring models.

One of the most significant advantages here is the potential for same-day funding. If you are facing an immediate crisis—such as a broken furnace in the middle of a Maryland winter—the ability to get money in your account the same business day is a game-changer. The application process is streamlined to be quick and easy, requiring minimal documentation to get started.

Pros:

  • Same-day funding available for approved applicants.
  • Does not affect FICO score during application.
  • No hidden fees in the advertised process.

Cons:

  • Approval is based on more than just credit, which can be unpredictable.

5. SECU

SECU stands as Maryland’s largest state-chartered credit union, offering a more traditional, community-focused banking experience. Their unsecured signature loans are a solid choice for those who want to build a long-term relationship with a financial institution. As a member-owned entity, SECU often provides a level of service and community alignment that national banks simply cannot match.

They offer loans ranging from $300 up to $30,000 with no application or prepayment penalties. This flexibility is vital; if you receive a tax refund or a work bonus, you can pay off your SECU loan early without being punished with extra interest—a common tactic used by other lenders. It is a refreshing change for those used to the predatory terms and “early repayment penalties” of some high-interest lenders.

Pros:

  • No application or prepayment penalties.
  • High maximum loan amounts for an unsecured product.
  • Strong community presence in Maryland.

Cons:

  • Credit union membership requirements may apply.

Navigating Your Borrowing Choices

Choosing a lender is not a decision to be made in a vacuum. Before signing any paperwork, you must look closely at the fine print. It is easy to get caught up in the excitement of a quick approval, but the cost of that speed can be steep if you do not perform the necessary due diligence.

Avoid the mistake of only looking at the monthly payment. A low monthly payment often means a much longer term, which results in you paying significantly more interest over the life of the loan. For example, a $2,000 loan with a $100 monthly payment over 36 months is far more expensive than a $2,000 loan with a $200 monthly payment over 12 months. Always calculate the total cost of the loan—the sum of all your payments—before you commit your signature.

Another common pitfall is failing to compare the lender’s reputation with your specific needs. If you need money today to prevent an eviction, a credit union might be too slow, even if they have better rates. Conversely, if you need $20,000 to consolidate your debts and lower your interest burden, a small cash advance lender won’t be able to help you reach that goal and may actually make your situation worse.

Lastly, remember that “guaranteed approval” is a myth in the lending world. Legitimate lenders must assess your ability to repay to comply with consumer protection laws. Anyone claiming they cannot say no is likely a red flag for a scam or a predatory lender. Stick to reputable providers that clearly outline their criteria and respect your financial well-being as you navigate through difficult times.

Top 5 Lenders for RV Loans for Bad Credit in 2026

Rv loans for bad credit

Top 5 Lenders for RV Loans for Bad Credit in 2026

Last updated: 2026-10-17

Getting the keys to a new motorhome shouldn’t feel like climbing a mountain of paperwork. For many travelers, a bruised credit score acts as a heavy anchor, preventing them from chasing the sunset in a comfortable fifth wheel or a cozy camper van. Whether you are looking to upgrade from a small pop-up to a full-sized Class A motorhome or you are simply trying to secure your first teardrop trailer, the financial hurdle can seem insurmountable without a clear roadmap.

The goal is to find a lender that looks past a single number and sees a real person. Choosing the right financing requires balancing interest rates against the speed of approval to ensure your camping season isn’t lost to bureaucracy. A delay in funding doesn’t just mean more time in the bank; it means missing out on that specific, well-maintained used RV that someone else is currently driving away with.

  1. My Financing USA
  2. FastLendGo
  3. Alliant Credit Union
  4. U.S. Bank
  5. Solarity Credit Union

Evaluating the Top Financing Options

The comparison process focused on several critical pillars of lending. Since many travelers need to move quickly, the speed of the approval process was a primary metric. Waiting weeks for a decision can mean losing a used RV to another buyer. In a competitive market, the “first to show proof of funds” often wins the deal, making lenders with rapid decision-making capabilities essential for successful shopping.

Accessibility for non-traditional credit profiles was also essential. This ranking prioritizes lenders that offer pathways for those with scores in the lower ranges, ensuring that the “bad credit” category is addressed with genuine, actionable options. We looked at how these lenders handle documentation, how they treat unconventional income like seasonal work or freelance earnings, and whether they specialize in recreational vehicle titles or general personal loans.

Lender Name Loan Amounts Credit Requirements Key Feature
My Financing USA $10,000+ 550 Minimum Score Nationwide search
FastLendGo See site Bad Credit Options Personal loan focus
Alliant Credit Union See site Credit Union Rates Same-day approval
U.S. Bank See site Pre-approval available Digital pre-approval
Solarity Credit Union See site See site NCUA Insured

1. My Financing USA

My Financing USA – myfinancingusa.com

Navigating the waters of financing can be tricky when your credit history isn’t pristine. My Financing USA searches nationwide to find programs specifically designed for those with less-than-perfect scores. It is a specialized approach for the road ahead, moving away from the “one-size-fits-all” model used by large national banks.

This lender caters to a wide variety of enthusiasts, from those looking for a simple travel trailer to owners seeking a massive yacht or a fifth wheel. They understand that the lifestyle isn’t one-size-fits-all, providing diverse options for different types of adventure. For instance, if you are looking for a vintage Airstream that might have unconventional value to a collector, a specialized lender is much more likely to understand the asset’s worth than a generic car loan provider.

If you are staring at a $10,000 budget or looking at something much larger, they provide a starting point. Their ability to handle everything from camper vans to horse trailers makes them a versatile choice for the nomadic soul. They specialize in finding lenders that view your down payment and your stable income as more important than a recent dip in your FICO score caused by a medical bill or a past credit mishap.

Pros:

  • Nationwide search for best programs
  • Minimum score of 550 for bad credit
  • Covers various vehicle types

Cons:

  • Interest rates can be higher for bad credit

2. FastLendGo

FastLendGo – fastlendgo.com

Sometimes, the need for cash is urgent, like a sudden repair or a last-minute deal on a camper. FastLendGo focuses on the speed of personal financing, offering a way to compare local options without the headache of traditional bank queues. This is particularly useful if you are looking to buy a private-party RV where the seller wants cash on the spot rather than waiting for a title loan to process.

They cater to a spectrum of credit needs, from “great credit” to “bad credit.” This flexibility means that whether you are looking for a small $500 boost for new camping gear or a larger personal loan to cover a significant down payment, there is a potential path forward for your specific situation. By matching you with various lenders, they increase the likelihood that you find a term that fits your monthly cash flow.

The platform is built for those who want to avoid the “where can I find a loan near me” scavenger hunt. By streamlining the digital comparison process, they aim to get you moving toward your next destination much faster. The interface is designed to minimize the time spent entering the same data multiple times, which is a common frustration with traditional lending portals.

Pros:

  • Quick access to cash via comparison
  • Covers various loan sizes
  • Options for diverse credit scores

Cons:

  • Focuses more on personal loans than specialized RV titles

3. Alliant Credit Union

Alliant Credit Union – alliantcreditunion.org

Alliant Credit Union stands out for those who prefer the community feel of a credit union. They offer rates that aim to beat the standard industry averages, making them a formidable opponent for traditional big-box banks. Because credit unions are member-owned non-profits, they often return their “profits” to members in the form of lower interest rates and fewer fees.

Speed is a major player here, as most members can receive a same-day approval. This is a lifesaver when you find that perfect used RV at a dealership and need to prove you are a serious buyer immediately. In the world of RV shopping, where a clean title and a low mileage engine can make a unit sell in hours, having that pre-approval in your pocket is a massive competitive advantage.

Their approach is built on rewarding members, offering a different experience than the cold, distant feeling of a massive national bank. It is about finding a financial partner that grows with your travel ambitions. As you move from a small camper van to a full-sized motorhome, a credit union is more likely to recognize your history as a loyal member and offer preferential terms for your next upgrade.

Pros:

  • Competitive credit union rates
  • Fast same-day approval in most cases
  • Member-focused approach

Cons:

  • Membership requirements may apply

4. U.S. Bank

U.S. Bank – usbank.com

For those who prefer the stability of a massive, established institution, U.S. Bank provides a digital-first approach to vehicle financing. Their system is designed to integrate into a modern, mobile lifestyle. If you are someone who manages your finances entirely through a smartphone and expects 24/7 digital access to your loan documents, this is a strong contender.

One of their strongest tools is the online pre-approval process. Knowing exactly how much you can borrow before you step foot on a dealership lot prevents the awkwardness of being turned away at the finish line. It allows you to walk into a dealership with the confidence of a cash buyer, knowing that your budget is firm and your financing is ready to go.

They offer a comprehensive suite of services, from checking accounts to wealth management. This makes them a one-stop shop for anyone looking to consolidate their entire financial life under one roof. For high-net-worth individuals or those looking to bundle their mortgage, savings, and RV loan, the convenience of a single institution can provide significant administrative relief.

Pros:

  • Convenient online pre-approval
  • Established, large-scale institution
  • Comprehensive banking ecosystem

Cons:

  • Stricter requirements compared to specialized lenders

5. Solarity Credit Union

Solarity Credit Union – solaritycu.org

Solarity Credit Union focuses on “brighter banking,” offering a more personalized touch to the lending process. They understand that a loan is more than just a transaction; it is a step toward a goal. When you speak with their representatives, you aren’t just a number in a database; you are a person with a specific vision for your retirement or your next season of travel.

Their RV and motor sport loans are designed to be simple and convenient. They aim to make the banking experience feel supportive rather than obstructive, which is vital when you are dealing with high-ticket items like motorized homes. They understand the nuances of recreational vehicle depreciation and how that affects your loan-to-value ratio, which can be a sticking point with traditional auto lenders.

As an NCUA-insured institution, they provide a layer of security that offers peace of mind. You can focus on planning your route through the national parks rather than worrying about the safety of your funds. This security is paramount, especially when you are making large transfers or managing significant down payments for a new lifestyle.

Pros:

  • NCUA insured security
  • Expert guidance from knowledgeable employees
  • Modern digital tools

Cons:

  • May have stricter eligibility than niche lenders

The Hidden Costs of RV Financing

Many buyers focus solely on the monthly payment, but a comprehensive view of your budget must include several “hidden” costs that can derail your travel plans if not accounted for upfront. When negotiating your loan, keep these factors in mind to ensure your lifestyle remains sustainable.

First, consider the impact of sales tax and registration fees. Depending on your state of residence, these can add thousands of dollars to the initial cost. Some lenders will roll these into the loan, but this increases your total interest paid over the life of the loan. It is often smarter to pay these upfront if your budget allows. Second, consider the cost of comprehensive and collision insurance. Most lenders require full coverage for any financed RV, and for a large motorhome, these premiums can be significantly higher than standard automobile insurance.

Finally, never forget the “lifestyle overhead.” An RV is more than just the vehicle; it is a home. You must account for campground fees, fuel, propane, and regular maintenance. A common mistake is to commit 100% of your disposable income to the vehicle loan, leaving no room for the actual adventure. A healthy budget should leave a buffer for unexpected repairs, such as a failed water pump or a worn-out tire, which can occur at any time during a long trip.

Essential Checklist for Securing Your Loan

To maximize your chances of approval and secure the best possible terms, follow these step-by-step specifics before you head to the dealership.

  • Verify Your Documentation: Gather your last two years of W-2s, your most recent 30 days of pay stubs, and your most recent bank statements. Lenders love consistency. If you are self-employed, have your last two years of tax returns ready to go.
  • Know Your Credit Score: Don’t wait for a lender to tell you your score. Check it yourself first. If there is a mistake on your report, dispute it now. A 20-point difference in your score can mean hundreds of dollars in interest savings over the life of the loan.
  • Calculate Your “All-In” Budget: Don’t just look at the sticker price. Calculate the total cost: Sticker Price + Sales Tax + Registration + Documentation Fees + Insurance + Initial Maintenance. This is your true starting point.
  • Compare the APR, Not Just the Monthly Payment: A lender might offer a low monthly payment by extending the loan to 15 or 20 years. While this helps your monthly cash flow, the total interest you pay over that time could be astronomical. Always look at the Annual Percentage Rate (APR) to understand the true cost of the money.
  • Get a Pre-Approval First: As mentioned with U.S. Bank, having a pre-approval in hand gives you leverage. When a dealer knows you already have financing, they are less likely to try to “upsell” you on high-interest in-house financing options.

Navigating the Road Ahead

Before signing any paperwork, it is vital to look at the total cost of the loan. A low monthly payment might look enticing, but if it comes with a massive interest rate, you will end up paying for the RV twice. Always ask for the total amount to be repaid over the life of the loan. This number is the most honest representation of the deal’s value.

Avoid the trap of rushing into a deal just because the salesperson is leaning in. It is perfectly acceptable to take a breath, look at your budget, and ensure the monthly payment fits comfortably into your lifestyle. Your freedom on the road depends on your financial freedom at home. A debt-heavy RV is just a very expensive way to feel trapped in a small space; a well-financed RV is the key to true independence.

Top 7 Lenders for Subprime Personal Loans in 2026

Subprime personal loans

Top 7 Lenders for Subprime Personal Loans in 2026

Last updated: 2026-10-16

Trying to fix your credit can feel like wandering through a thick fog. When your score isn’t where it needs to be, finding a way out often feels impossible. Many people find themselves stuck in a loop, searching for a way to bridge the gap between their current bank balance and their long-term goals.

Finding a lender that looks past your credit score to the person underneath is a vital first step. You shouldn’t just grab the first interest rate you see in a headline. You have to weigh how fast you get the cash against what the loan will actually cost you in the end.

Speed matters when a car breaks down or a medical bill arrives unexpectedly. However, long-term affordability is what keeps your head above water when those monthly payments finally start rolling in. Because everyone’s financial life is different, a one-size-fits-all approach rarely works.

  1. JetzLoan
  2. Avant
  3. OneMain Financial
  4. OppLoans
  5. LightStream
  6. Hearth
  7. USPS Federal Credit Union

How These Lenders Were Evaluated

We focused on how easy it is for people with less-than-perfect credit to get a seat at the table. A huge part of this was looking for lenders that allow you to get a quote without a hard credit pull. This keeps your score from taking a hit while you are just window shopping.

We also poked and prodded how transparent these companies are about their fees. We looked at how quickly the money actually lands in your bank account and how much they are willing to lend. Nobody wants to find out about a hidden fee after the money is already spent.

Application simplicity was a major factor in our decision. If you are facing an emergency, waiting a week for funds is not an option. We checked to see if the application was a digital marathon or a quick sprint through a few simple questions to get you moving.

Lender Name Loan Amounts Funding Speed Credit Impact (Check) Starting APR / Terms
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull See site
Avant $2,000 – $35,000 Fast decision See site See site
OneMain Financial $1,500 – $30,000 As soon as 1 hour No credit score impact 11.99% APR / 24-60 months
OppLoans See site Same-day funding available Does not affect FICO score See site
LightStream See site Next day See site Low fixed rates (Excellent credit req.)
Hearth See site See site See site See site
USPS Federal Credit Union See site See site See site As low as 4.75% APR

1. JetzLoan

JetzLoan – jetzloan.com

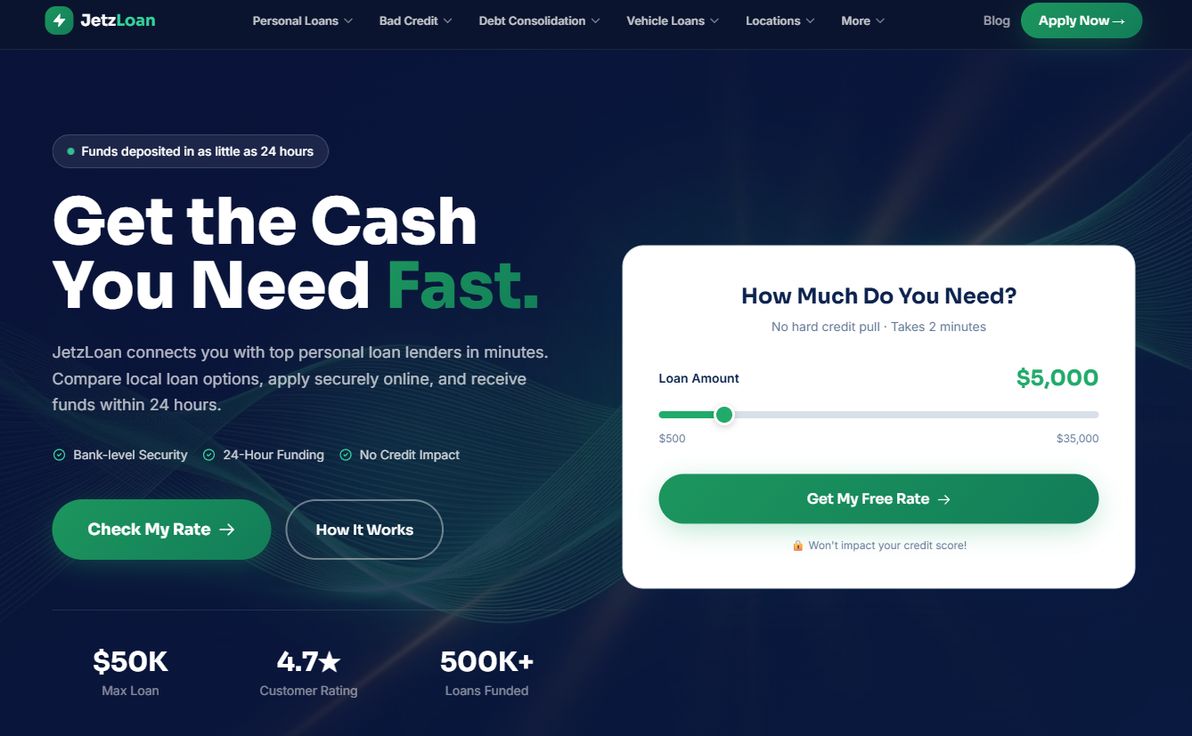
JetzLoan works by connecting borrowers with various top personal loan lenders in just a few minutes. This platform is built for speed. They aim to get funds deposited into accounts in as little as 24 hours, which is a lifesaver when things go wrong suddenly. It is useful for debt consolidation or vehicle loans without a long, drawn-out ordeal. (jetzloan.com)

The process is incredibly lightweight. You only need to fill out a simple form that takes less than two minutes. Since they offer a no-hard-credit-pull check, you can explore your options without worrying about damaging your score. It is a low-risk way to see what is actually possible for you.

Pros:

  • No hard credit pull during the initial check.
  • Fast 24-hour funding capability.
  • High customer rating of 4.7 stars.

Cons:

  • It is a connection service rather than a direct lender.

2. Avant

Avant – avant.com

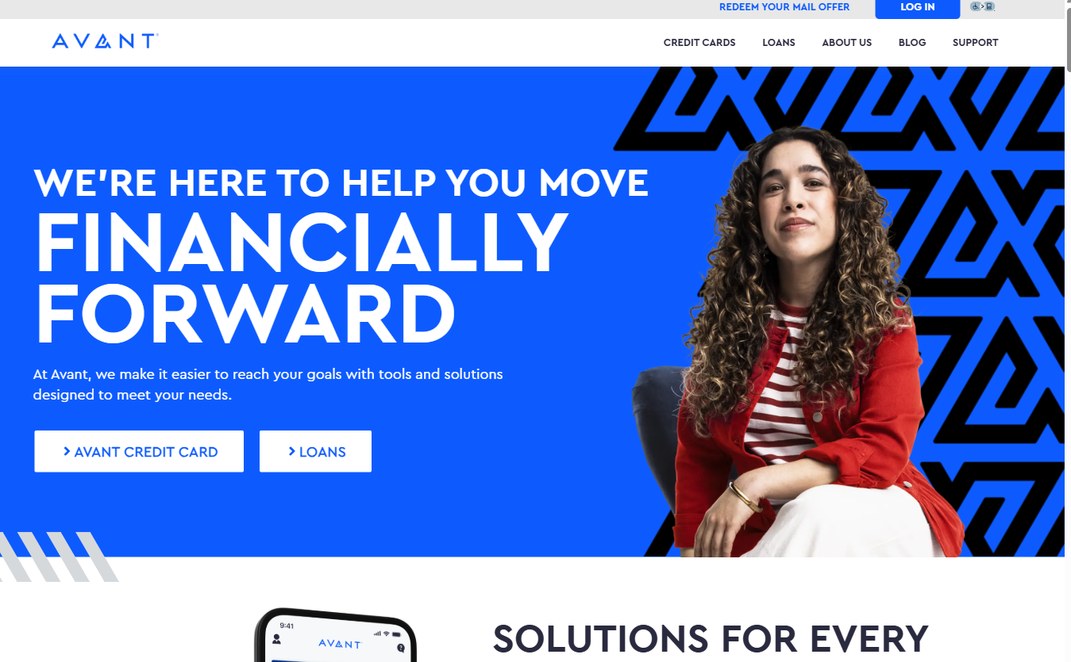
Avant targets people who need a clear path forward. They offer various tools designed to help users move financially, including personal loans and credit cards. This makes them a versatile choice for different milestones. They focus on providing options for people whose financial lives are in a state of transition.

The application for their personal loans is straightforward. You only need to go through three simple steps to reach a decision. Whether you need an emergency loan or cash for home improvements, Avant uses digital-first solutions to make the journey a bit easier.

Pros:

  • Simple 3-step application process.
  • Covers a wide range of needs like debt consolidation.
  • Flexible product options including credit cards.

Cons:

  • Specific loan amounts are restricted to a specific range.

3. OneMain Financial

OneMain Financial – onemainfinancial.com

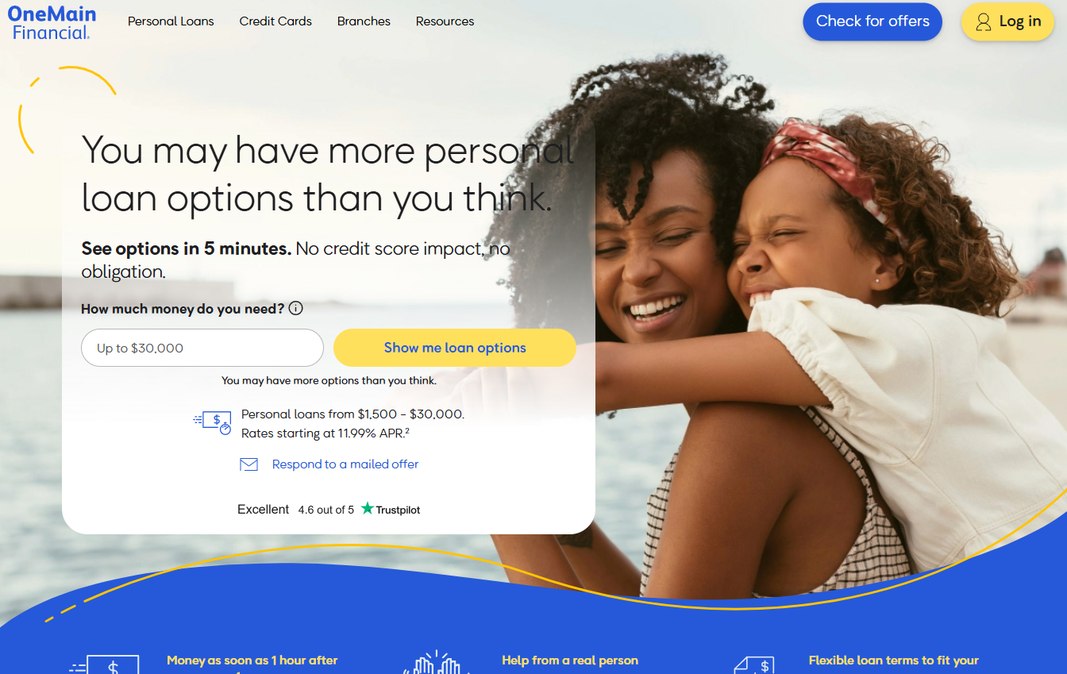
OneMain Financial is a great pick for those who prefer a mix of digital ease and talking to a real person. They have over 1,300 branches, so you can walk in and talk to someone if things get complicated. They offer personal loans from $1,500 up to $30,000, which covers most mid-sized expenses.

Speed is a big part of their appeal. Some users see money in their accounts as soon as one hour after signing. The terms are predictable, with fixed monthly payments and lengths between 24 and 60 months. This predictability helps anyone trying to stick to a strict monthly budget.

Pros:

  • Extensive branch network for in-person support.
  • Very fast funding possible within one hour.
  • Fixed monthly payments for predictable budgeting.

Cons:

  • Requires a formal signing process to unlock funds.

4. OppLoans

OppLoans – opploans.com

OppLoans specializes in helping people who might have been turned down by traditional banks. Their platform works with bank partners to look at more than just a single credit score. This makes them a strong candidate for anyone needing same-day funding to handle an urgent crisis.

The application is built around the user. They aim for decisions that arrive in just a few minutes. They also emphasize transparency by stating there are no hidden fees, which is a breath of fresh air in the subprime lending market. It is a streamlined option for quick, direct assistance.

Pros:

  • Same-day funding is available for approved users.
  • Decisions are often made within minutes.
  • No hidden fees to worry about.

Cons:

  • Approval is subject to bank partner criteria.

5. LightStream

LightStream – lightstream.com

LightStream is a specialized choice. People often favor them when they want to finance high-value items like boats or major home renovations. They run on a “Lending Uncomplicated” philosophy, focusing on a smooth digital experience. Many customers find they have the funds by the very next day.

While they are great for specific purposes, they aren’t a catch-all for everyone. They typically require excellent credit to get those low rates. However, if you have a solid history and need a large-scale loan, the efficiency is hard to beat.

Pros:

  • Very fast funding, often by the next day.
  • Excellent for specific purpose loans like boats.
  • Highly rated customer experience for smooth processes.

Cons:

  • Requires excellent credit for the best rates.

6. Hearth

Hearth – hearth.com

Hearth operates more as a knowledge hub than a standard lender. Since 1995, they have been a staple for information on energy-saving equipment, like wood or pellet stoves. They focus heavily on promoting efficient and responsible uses of various fuels.

They might not be the first place you go for a quick cash loan for an emergency, but their forums are incredibly useful. If your financial needs involve home energy efficiency or specific equipment, the community advice found here is gold.

Pros:

  • Decades of expertise in energy-related financing topics.
  • Extensive community forums for peer advice.
  • Focuses on responsible and safe fuel use.

Cons:

  • Not a direct personal loan provider for general cash.

7. USPS Federal Credit Union

USPS Federal Credit Union – uspsfcu.org

The USPS Federal Credit Union is a dedicated institution for postal employees. They offer a sense of community and specialized service that you just don’t find at big banks. Their loans support life’s milestones, from auto loans to flexible personal options.

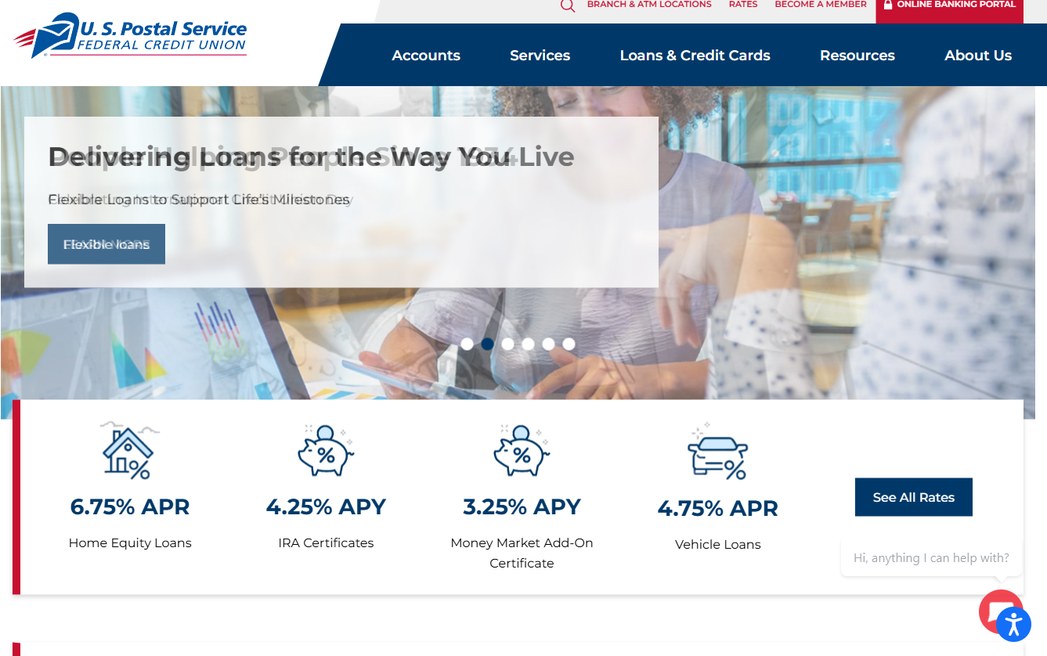
They offer competitive rates, with some starting as low as 4.75% APR for certain products. For members, the value lies in their “People Helping People” philosophy. It creates a sense of security and shared purpose in every transaction you make.

Pros:

  • Very competitive rates for members.
  • Strong community focus on serving employees.
  • Diverse range of products like HELOCs and credit cards.

Cons:

  • Membership is restricted to specific employee groups.

Avoiding Common Pitfalls

Read the fine print on the total cost of your loan before you sign anything. A low monthly payment sounds great, but if it stretches over several years, you could end up paying double what you originally borrowed. Always calculate the total interest you will pay over the life of the loan.

Don’t rush into the first offer that lands in your mailbox. Even if you need the cash quickly, it is vital to compare rates and terms. Use the “no impact” checks offered by many lenders to shop around without fear. Taking a moment to compare can save you thousands of dollars.

Top 5 Lenders for Bad Credit Loans in Ohio: 2026 Rankings

Bad credit loans ohio

Top 5 Lenders for Bad Credit Loans in Ohio: 2026 Rankings

Last updated: 2026-10-17

Trying to manage money in the Buckeye State can feel like driving through a Cleveland snowstorm without winter tires. One minute you are fine, and the next, a sudden transmission failure or an urgent dental bill in Columbus leaves you scrambling. Unexpected property tax adjustments can also throw a wrench in your monthly budget.

Many Ohioans find themselves hunting for quick cash solutions that don’t demand a perfect credit score. It is a stressful spot to be in, especially when the bills arrive all at once. You need a solution that works as well as your bank account does.

Finding a lender involves more than just hunting for the lowest interest rate. You have to look at how fast they move and whether an inquiry will tank your credit score. A lender in Dayton might have much different processing times than one operating out of Akron or Youngstown. Understanding these differences is the difference between solving a crisis and creating a brand new one.

  1. JetzLoan
  2. MaxCash
  3. Buckeye State Credit Union
  4. OppLoans
  5. Bridge Credit Union

Evaluating Ohio’s Short-Term Lending Options

Speed and accessibility drove our selection process for this list. When people look for these loans, they are usually facing an emergency. Being able to receive funds within 24 hours, or even the same day, is a non-negotiable metric. If you are facing an eviction notice or a utility shut-off, waiting three days is effectively the same as a denial.

We prioritized lenders that use modern digital verification to keep things moving fast. We also looked closely at how much a lender affects your credit score. Many borrowers worry that checking their eligibility will cause their FICO score to drop further. This is a legitimate fear since hard inquiries can temporarily dip your score by several points.

Lenders offering a soft credit pull or “no credit impact” checks earned higher priority. We wanted to find options that allow you to “window shop” for rates without risking your ability to get a mortgage or car loan later. Protecting your long-term financial health is just as important as getting cash today.

Lender Name Loan Amounts Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
MaxCash $250 – $10,000+ In minutes See site
Buckeye State Credit Union See site See site See site
OppLoans $500 – $5,000 Same-day funding available Does not affect FICO score
Bridge Credit Union See site Quicker with online signing See site

Understanding Different Loan Types in Ohio

You should know exactly what kind of debt you are signing up for before you commit to a lender. Not all “quick cash” is created equal, and the fine print can get confusing when you are under high stress. We have broken down the most common structures you will likely encounter.

Personal Installment Loans

These are typically the most stable option for short-term needs. You get a lump sum of cash upfront and pay it back in fixed monthly installments over a set period, like 12, 24, or 36 months. Because the payments are predictable, they are easy to fit into a budget.

If you use an installment loan to consolidate high-interest credit card debt, a lower fixed APR can save you a significant amount of money. It turns a chaotic pile of debts into a single, manageable monthly payment. This is a smart way to clean up your finances over time.

Title Loans

You will see these often in urban areas like Cleveland or Cincinnati. Title loans use your vehicle as collateral, which makes it much easier to get funds even with poor credit. However, the risk is extreme. If you cannot meet the repayment terms, the lender has the legal right to repossess your car.

This should be a last resort. Only consider a title loan if you have absolutely no other options and a rock-solid plan for repayment. Losing your transportation can often cost you more in the long run than the loan was worth.

Payday or Short-Term Advance Loans

These are meant for very small amounts that you plan to pay back by your next payday. While they offer immediate relief for a small grocery bill or a utility payment, they often carry much higher APRs. They work best for minor cash flow gaps rather than deep financial problems.

Using a payday loan to pay off a larger debt is a recipe for a debt cycle that is incredibly difficult to escape. It is a temporary fix that can lead to a much larger, permanent problem if you aren’t careful.

The Best Lenders for Ohio Residents

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works as a high-speed connector between borrowers and top personal loan lenders. It is built for people who need a quick answer without the dread of a hard credit inquiry. The platform focuses on efficiency, letting you compare various local loan options in just a few minutes.

Instead of filling out ten different applications, you fill out one. The technology then matches you with the most suitable providers. This is a great choice if you need a significant amount, such as for debt consolidation or a vehicle loan, with limits up to $35,000.

This service caters to substantial financial needs rather than just small emergency cash advances. It is a powerful tool for anyone looking to consolidate several high-interest debts into a single, manageable monthly payment. (jetzloan.com)

Pros:

  • Fast funding within 24 hours.
  • No hard credit pull during the initial rate check.
  • High loan ceiling up to $35,000.

Cons:

  • The platform acts as a connector rather than a direct lender.

2. MaxCash

MaxCash – maxcash.com

MaxCash acts as a versatile one-stop shop for different financial products. Whether you need a small installment loan or a larger personal loan, the platform offers handpicked services to match your specific situation. It is designed to provide relief during stressful moments like unexpected medical bills.

The flexibility here is notable, with loan tiers ranging from a modest $250 to over $10,000. This makes it a strong contender if you need a specific, predetermined amount to cover a single bill or a series of small expenses. The interface guides you through the selection process to reduce stress.

Pros:

  • Wide range of loan amounts from $250 to $10,000+.
  • Covers various needs like title loans and installment loans.
  • Quick inquiry process.

Cons:

  • The wide variety of products can be overwhelming for some users.

3. Buckeye State Credit Union

Buckeye State Credit Union – buckeyecu.org

Buckeye State Credit Union offers a more traditional banking experience. It is ideal for those who prefer a “member-first” approach where banking feels personal. Unlike large national banks that treat you like an account number, a credit union is a member-owned cooperative. This often leads to better service.

While they offer low-rate personal loans, they are a great fit for long-term financial health. They provide various tools, including HELOCs and specialized savings accounts, to help members grow their wealth. It is a stable choice for those looking to build a relationship with a financial institution.

Pros:

  • Personalized banking services and member-focused approach.
  • Offers diverse financial products like HELOCs and investment services.
  • Focus on responsible borrowing with better rates.

Cons:

  • Requires membership and may have more stringent requirements than quick-cash lenders.

4. OppLoans

OppLoans – opploans.com

OppLoans is specifically designed for people who might have been turned down by traditional banks. Because they look beyond just a single FICO score, they can evaluate a broader range of financial data. This makes them a vital resource for Ohioans who have faced previous rejections.

The speed of this service is impressive, with same-day funding available in many cases. The application is straightforward and requires minimal documentation. Decisions often arrive within minutes of submitting the online form, which is critical when you are facing an immediate deadline.

Pros:

  • Same-day funding available for many applicants.
  • Decision-making considers more than just the credit score.
  • Applying does not affect your FICO score.

Cons:

  • Loan amounts are capped at a lower $5,000 limit.

5. Bridge Credit Union

Bridge Credit Union – bridgecu.org

Bridge Credit Union serves Central Ohio with a focus on community connection. They offer unique products like “Back-to-High” holiday loans and “Skip-A-Pay” options. These can be lifesavers during the expensive holiday seasons or when a paycheck is delayed.

They also provide share-secured loans, which can help you access funds even if your credit isn’t perfect. By using your own savings as collateral, you reduce the lender’s risk, which can lower your interest rate. Their ability to sign loans online makes things very convenient for busy people.

Pros:

  • Specialized products like Skip-A-Pay and holiday loans.
  • Share-secured loan options for those with imperfect credit.
  • Convenient online signing process.

Cons:

  • Geographically focused on Central Ohio.

Navigating the Loan Process Safely

Before you sign anything, read the fine print. Even when you are in a rush, taking five minutes to understand the total cost of borrowing can save you hundreds of dollars. A lender might advertise a “low monthly payment,” but if that payment is spread over a long period, you could end up paying double or triple what you borrowed.

Avoid the trap of taking out multiple high-interest loans to pay off previous ones. This “debt spiral” is a common mistake that leads to a permanent struggle. For example, taking a high-interest payday loan to pay a credit card bill often results in interest that is even higher than the old debt. Use these tools as a bridge, not a permanent lifestyle.

Lastly, verify the legitimacy of any lender that contacts you out of the blue. Scammers often prey on people in urgent need of cash. They might use high-pressure tactics or claim you have been “pre-approved” for a loan you never asked for. Stick to well-known platforms and never pay an upfront fee to “secure” a loan. If a lender asks for payment via gift cards or wire transfers upfront, walk away immediately.