(562) 400-4959 vsfoundation@outlook.com

The 5 Best Pool Financing Options for 2026: An Honest Ranking
Pool financing

The 5 Best Pool Financing Options for 2026: An Honest Ranking

Last updated: 2026-10-17

Turning a backyard into a private oasis is a massive undertaking. It often requires much more cash than most people have sitting in a savings account. Whether you are eyeing an inground pool, a luxury saltwater system, or a high-end swim spa, securing the right capital is the first step toward that summer splash.

The financial commitment extends far beyond the initial purchase price of the unit. You have to account for excavation, plumbing, electrical work, and the surrounding hardscaping required to make the area functional and beautiful. It is a long list of expenses that can add up quickly.

Selecting a lender is not a one-size-fits-all endeavor. What works for a homeowner with a pristine credit score might be a non-starter for someone recovering from a recent financial hiccup. A borrower with a 780 FICO score might find success with a traditional bank.

A borrower with a 620 score might need to look toward specialized lenders who prioritize stability and income over a perfect credit history. This ranking focuses on finding the most reliable paths to funding your aquatic dreams. We want to ensure you don’t settle for high-interest debt that hampers your long-term financial health.

  1. Avant
  2. FastLendGo
  3. HFS Financial
  4. Acorn Finance
  5. LightStream by Truist

How These Lenders Were Evaluated for Your Backyard Project

The selection process focused on accessibility and the specific needs of pool owners. A lender that specializes in general debt consolidation might not understand the nuances of a construction-heavy project. For instance, a pool installation is often a staged process.

You might pay a deposit to the contractor, a midpoint payment after excavation, and a final payment upon completion. Lenders that provide lump-sum loans are excellent, but those that can accommodate the workflow of a contractor are even better.

We looked at credit flexibility, the ease of the application process, and the specific loan products available. A lender that offers a quick decision is worth their weight in gold when a contractor is waiting to break ground. You don’t want to lose your spot on their schedule because of a slow bank.

We also analyzed the “soft pull” capability. This is the ability for you to check your potential rate without a hard inquiry that would lower your credit score. Every option was weighed against real-world usability, looking at how these companies handle everything from the initial inquiry to the final disbursement of funds.

Comparison of Leading Pool Financing Providers

Lender Name Loan Amounts Interest Rates Credit Requirements Funding Speed
Avant See site See site See site See site
FastLendGo $500 – $5,000+ See site Bad to Great Credit See site
HFS Financial $1,000 – $450,000 From 7.80% Bad Credit Options See site
Acorn Finance Up to $100,000 From 6.99% Good & Bad Credit See site
LightStream by Truist See site See site See site See site

Ranking the Top 5 Lenders for Pool Financing

1. Avant
Avant – avant.com

Avant positions itself as a versatile player in the personal loan market. They aim to help people move forward financially by offering flexible choices that fit into a variety of life stages. Their interface is designed for those who want to keep things simple and straightforward.

This makes it ideal for the tech-savvy homeowner who wants to manage their loan from a smartphone while standing in their newly renovated backyard. It is a modern approach for a modern renovation.

This lender is particularly useful for those needing to bridge the gap between a standard credit card and a massive mortgage. If you have a small pool project, such as a high-end hot tub or a sophisticated filtration system upgrade, Avant offers a way to get the funds without the lengthy paperwork required for a home equity line of credit (HELOC).

They offer solutions that can assist with home improvement or unexpected expenses. This makes them a solid choice for various backyard upgrades ranging from small fire pits to large stone walkways.

Pros:
  • Flexible loan solutions for different financial journeys.
  • User-friendly online application process.
  • Options for debt consolidation alongside home improvement.
Cons:
  • May not offer the specialized construction-focused terms found in niche lenders.

2. FastLendGo
FastLendGo – fastlendgo.com

FastLendGo acts as a bridge for those who might feel sidelined by traditional banks. They specialize in a wide spectrum of credit profiles, ranging from those with bad credit to those with great credit. It is an excellent option for quick access to cash when you need to secure a seasonal discount from a pool professional or a supplier. (fastlendgo.com)

Whether you need a small $500 emergency loan for a broken pump part or a larger sum for a motorcycle or auto repair that you’d rather not pay for with a high-interest credit card, they cover the bases. They understand that life happens.

Their ability to compare local options makes them a highly efficient partner for those in a hurry to start a project. By looking at a wide array of lenders, they can often find a match for borrowers who might have been rejected by a local credit union.

Pros:
  • Extremely wide range of loan amounts.
  • Caters specifically to bad and fair credit.
  • Fast way to compare local financing options.
Cons:
  • Interest rates for bad credit may be significantly higher.

3. HFS Financial
HFS Financial – hfsfinancial.net

HFS Financial is a heavy hitter when it comes to specialized home improvement. They focus heavily on the actual assets being installed, such as swimming pools, hot tubs, or even solar panels. Unlike general personal loan lenders, HFS understands that a $50,000 pool is an investment in your property value.

Their limits are impressive, reaching up to $450,000 for major renovations. This could include a pool, a detached pool house, and extensive landscaping. It is a serious option for a serious project.

This is the go-to option for the homeowner who isn’t just buying a pool, but is undergoing a total backyard transformation. They understand the complexity of inground pools and luxury swim spas, offering rates that start at a competitive 7.80%.

They are well-versed in the “contractor-direct” model. In this setup, the lender often works closely with the professional performing the installation to ensure funds are released upon completion of specific project milestones.

Pros:
  • Massive loan amounts for large-scale projects.
  • Specialized focus on pool and hardscape financing.
  • Inquiring about rates does not impact credit scores.
Cons:
  • The high upper limits may require stringent documentation.

4. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance operates with a unique model that connects borrowers with contractors. This is a 100% free service for both parties, which is a breath of fresh air in the lending world. They aim to provide clarity without the typical dealer fees that often get tacked onto the end of a contractor’s quote.

By using their marketplace, you aren’t just looking for money; you are looking for the right financial fit for your specific project scope. It is about finding the right tool for the job.

They offer a high level of convenience, allowing users to check personalized rates with no credit score impact. This is ideal for someone who is still in the “dreaming and planning” phase and wants to see what is possible before committing to a specific contractor or design.

You can run the numbers for a $20,000 concrete pool shell versus a $60,000 fiberglass shell to see how the monthly payments differ without any risk to your credit profile. It is a great way to test the waters.

Pros:
  • No dealer fees for the borrower.
  • Personalized rates with no credit score impact.
  • High user satisfaction based on extensive reviews.
Cons:
  • The marketplace model means you are dealing with multiple potential lenders.

5. LightStream by Truist
LightStream by Truist – lightstream.com

LightStream by Truist is a premier option for those who want to finance their pool without tapping into their home equity. It is a streamlined, digital-first approach designed to keep the focus on the improvement rather than the debt structure. It is a clean way to handle the math.

Because these are unsecured personal loans, you don’t have to worry about your home being collateral if the project runs over budget or if you face unexpected financial hardship. Your roof stays safe while you build your oasis.

While they are currently not accepting new applications in some contexts, they remain a benchmark for how high-quality, fast-decision lending should look. For those with the right profile—typically high credit scores and steady, documented income—it is a seamless way to upgrade a home.

The speed of their approval process is often measured in hours rather than days. This makes it one of the fastest ways to move from “concept” to “construction.” You could be swimming by next month.

Pros:
  • Avoids the complexities of home equity loans.
  • Fast and easy online application process.
  • Backed by the stability of Truist.
Cons:
  • Availability of applications can be subject to change.

Understanding the True Cost of Pool Financing

Many homeowners make the mistake of focusing solely on the monthly payment. While a $150 monthly payment sounds much more manageable than a $600 payment, you must calculate the total interest paid over the life of the loan. It is a common trap.

For example, a $40,000 loan at 8% interest over 5 years results in significantly less total cost than the same loan over 10 years. If you can afford a higher monthly payment, you will save thousands of dollars in interest and build equity in your backyard much faster.

Consider these three common financial pitfalls in pool financing:

  • The “Scope Creep” Trap: A project estimated at $30,000 often ends up costing $40,000 due to unexpected rock excavation, soil issues, or upgrades to the filtration system. Always borrow slightly more than the base quote to avoid needing a second, smaller, and more expensive loan later.
  • The Interest Rate Trap: Don’t just look at the teaser rate. Check the APR (Annual Percentage Rate), which includes the interest plus any origination fees. A “low” interest rate with a 5% origination fee can actually be more expensive than a slightly higher interest rate with no fees.
  • The Fixed vs. Variable Trap: Ensure you know if your rate is fixed for the life of the loan. Variable rates might start lower but can increase if market conditions shift, potentially making your “oasis” a financial burden during an economic downturn.

Preparing Your Documentation for a Fast Approval

To ensure your pool project moves from the planning stage to the construction stage without delay, you should gather your financial documentation before you even begin the application process. Lenders want to see a clear picture of your ability to repay the debt. Having these documents ready can shave days or even weeks off the approval process.

Prepare a digital folder containing the following:

  • Proof of Income: Your two most recent pay stubs and your last two years of W-2 forms. If you are self-employed, have your most recent two years of tax returns ready, as lenders will look closely at your net income rather than gross revenue.
  • Project Estimates: At least two detailed, written quotes from reputable pool contractors. Lenders like HFS Financial or Acorn Finance may require these to verify the intended use of the funds and the legitimacy of the project.
  • Asset Statements: Recent statements for your checking and savings accounts. This demonstrates that you have the “cushion” necessary to handle the initial deposits and the ongoing maintenance costs of a pool.
  • Identification and Residency: A valid driver’s license and recent utility bills to verify your address.

By approaching pool financing with the same level of organization as you would a mortgage, you position yourself as a low-risk borrower. This not only speeds up the funding process but often results in more favorable interest rates, ultimately saving you money on your backyard transformation.

Navigating Your Path to a Backyard Oasis

Before you sign on the dotted line, it is vital to look beyond just the interest rate. You must consider the total cost of borrowing. A low monthly payment might look enticing on paper, but a longer term can mean you pay thousands more in interest over the life of the loan. This is especially critical with large-scale projects like inground pools where the principal amount is substantial.

One common mistake is failing to account for the “hidden” costs of pool ownership. Installation is just the beginning; maintenance, chemicals, electricity for pumps, and potentially a specialized insurance rider are ongoing expenses. Ensure your loan amount covers the complete project, including the liner, the deck, the landscaping, and even the initial chemical startup kit.

Failing to budget for these can lead to a beautiful pool that remains empty because you cannot afford to run the pump. It is a heartbreaking sight for any homeowner.

Always check the fine print regarding prepayment penalties. If you come into a windfall—perhaps through a work bonus or the sale of an asset—and want to pay off your pool early, you don’t want to be hit with a fee for being responsible. Comparing these details between Avant, HFS Financial, and others will save you a massive headache down the road. A smart borrower looks for flexibility: the ability to pay extra toward the principal whenever possible without being penalized for it.
The 4 Best Lenders for Uber Drivers with Bad Credit in 2026

Loans for uber drivers with bad credit

The 4 Best Lenders for Uber Drivers with Bad Credit in 2026

Last updated: 2026-10-17

Life in the gig economy feels like a constant balancing act. One week, surge pricing is high and the money flows, then the next, a sudden transmission failure wipes out your entire profit margin. For many rideshare drivers, a dip in a credit score shouldn’t mean being locked out of the cash needed to stay on the road.

The reality of this work is unpredictable. Platform algorithms shift without warning, gas prices fluctuate daily, and high-mileage vehicles eventually demand expensive repairs. This makes your financial situation look very different from someone with a standard 9-to-5 job. You aren’t just managing a car; you’re managing a volatile, mobile business.

When you need quick financial support, you aren’t looking for perfection. You need speed. You need a lender that understands your income comes from driving miles rather than a steady bi-weekly paycheck. Traditional banks often get tripped up by this, demanding two years of tax returns and a single, verifiable employer. To a legacy bank, making $2,000 one week and $800 the next looks unstable. To a specialized gig lender, that same driver is just a high-frequency earner with a non-traditional revenue stream. This list focuses on accessibility, speed, and how well these options fit your lifestyle.

  1. JetzLoan
  2. Giggle Finance
  3. Ualett
  4. Credit Ninja

How These Rideshare Lenders Were Evaluated

We focused heavily on how fast you can get your hands on the cash. For a driver, a broken car isn’t just a nuisance; it is a total halt to your income. If your vehicle sits in a mechanic’s bay for five days while you wait for loan approval, you lose the repair cost and the seven days of earnings you would have made. We looked for services that bridge that gap between an emergency and your next platform payout.

We also prioritized lenders that don’t punish you for checking your rates. In the world of bad credit, “window shopping” for loans can actually hurt your score. Every time a lender performs a “hard pull” on your credit report, your score can drop. For someone living on the edge of a credit threshold, that small dip might be the difference between qualifying for a low-interest loan or getting rejected entirely. We sought out companies that offer transparency through soft credit pulls so you can shop around safely.

The application process itself mattered too. Drivers don’t have hours to sit at a desk filling out paperwork. We looked for lenders that offer mobile-friendly interfaces and digital document uploads. You should be able to manage your finances from the driver’s seat while waiting for your next fare.

Lender Name Max Loan Amount Funding Speed Credit Impact of Check
JetzLoan $50,000 Within 24 hours No hard credit pull
Giggle Finance $15,000 In minutes See site
Ualett See site Fast funding See site
Credit Ninja See site Same day decision No impact on score

The Top 4 Lenders for Gig Workers

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works like a high-speed bridge when you need substantial capital fast. It is a lifesaver for drivers facing major engine work, a complete vehicle overhaul, or even a sudden need to upgrade to a newer model to meet platform standards. Because they connect you with various top lenders, they offer more variety than a single boutique lender. Instead of you applying to ten different places, JetzLoan acts as a conduit to find the best match for your specific profile.

This is a great option if you need to consolidate high-interest debt, like a credit card used for a previous repair, or if you need a significant vehicle loan. Seeing rates without a hard credit pull is a massive advantage when you are trying to rebuild your financial health. You can see potential terms upfront and decide if the monthly payment fits your weekly earnings before you ever commit to a formal application.

Pros:

  • High maximum loan amounts up to $50,000.
  • Extremely fast funding, often within 24 hours.
  • No hard credit pull means no damage to your score while checking.

Cons:

  • The matching process depends on the specific lenders in their network, meaning rates can vary significantly between matches.

2. Giggle Finance

Giggle Finance – gigglefinance.com

Giggle Finance was built specifically for the 1099 worker. They don’t just stare at a credit score; they look at the reality of a side hustle. They understand that “income” for a gig worker is a collection of deposits from Uber, Lyft, DoorDash, or Instacart rather than a single W-2 line item. This makes them a top choice for Uber drivers in a tight spot who need money almost instantly to keep working.

The speed here is hard to beat, with funding potentially arriving in just a few minutes. It is a specialized tool designed to handle the irregular income patterns that traditional banks often find too risky. If you need a new set of tires or a battery replacement right now, Giggle Finance is built to provide that liquidity before your next shift begins.

Pros:

  • Very fast funding, sometimes within minutes.
  • Tailored specifically for 1099 and self-employed workers.
  • Repeat customers can access higher limits up to $20,000.

Cons:

  • Loan amounts are lower than some major personal loan providers, making it less suitable for massive capital expenditures.

3. Ualett

Ualett – ualett.com

Ualett functions more like a cash advance than a traditional long-term loan. This is a game-changer for drivers dealing with the “ups and downs” of variable weekly earnings. It provides a cushion that aligns with how gig workers actually earn money. If you have a high-earning week but need that cash immediately to cover an insurance premium or a utility bill, Ualett helps bridge that gap.

Instead of dealing with rigid repayment schedules that are hard to meet if you take a week off for illness, Ualett offers flexibility. It is a digital-first solution for managing cash flow, making it a great companion app for those who live week-to-week. It essentially turns your future earnings into present-day liquidity.

Pros:

  • Designed specifically for the variable income of the gig economy.
  • Focuses on cash advances rather than heavy debt structures.
  • Integrated app-based experience for ease of use.

Cons:

  • May not provide the large lump sums needed for major capital investments like buying a second vehicle.

4. Credit Ninja

Credit Ninja – creditninja.com

Credit Ninja is a solid choice if you want a straightforward, online personal loan experience. If traditional banks have turned you away because of your credit history or your employment status, this service focuses on finding solutions that actually work. They act as a smart filter, running your data through various lender criteria to find the most likely “yes.”

The application is quick, often providing a decision as early as the same day. This is a practical option for covering unexpected life expenses, like a medical bill or a household repair, without a complex, multi-day approval process. It is less about the “gig” specifics and more about providing an alternative path to credit when the mainstream system fails you.

Pros:

  • Quick decision-making process, sometimes on the same day.
  • Simple and easy online application.
  • Helps drivers who cannot get approved by traditional lenders.

Cons:

  • Approval is not guaranteed and depends on specific qualifying criteria.

Strategic Financial Management for Drivers

Securing a loan is only the first step; managing that debt determines your long-term health. For gig workers, the key is to treat your vehicle and your personal finances as a single, integrated business. Here is a way to manage your liquidity:

  1. The Emergency Buffer: Try to set aside a small percentage of every “surge” payout into a separate high-yield savings account. This isn’t for daily coffee; it’s specifically for your “transmission fund.”
  2. Document Your Income: Even if you use apps, keep a secondary log of your weekly net earnings. If you ever apply for a large loan for a new vehicle, having an organized spreadsheet showing consistent monthly income can significantly improve your odds.
  3. Understand the “Total Cost of Credit”: When using cash advances, calculate the fee relative to the amount borrowed. If a $50 advance costs $5 in fees, that is a 10% cost for a very short period. Ensure the speed is worth that specific cost.
  4. Debt Snowball vs. Avalanche: If you use a loan to consolidate debt, decide if you will pay off the smallest balance first (Snowball) for momentum, or the one with the highest interest rate first (Avalanche) to save the most money.

Avoiding Common Financial Pitfalls

When you are staring at an empty bank account and a car that won’t start, it is easy to make a desperate move. Many drivers fall into the trap of predatory lending, where the speed of the money is matched by an astronomical interest rate. These lenders often target people in high-stress situations. Always check the total repayment amount before signing anything. If the total is significantly higher than what you are receiving, proceed with extreme caution.

Another mistake is failing to read the fine print on repayment. A fixed monthly payment might be easy during a busy month, but it can become a crushing weight during a slow month or if you get sick. Always look for lenders that offer some level of flexibility, such as the ability to skip a payment or adjust your schedule if your income changes.

Finally, remember that your income is your greatest asset. Even with bad credit, your ability to earn is what matters most to many modern lenders. They see the potential in your ability to drive another 20,000 miles. Keep your earnings records organized, as having proof of consistent gig work can often be the key to unlocking better rates and higher limits that traditional banks simply cannot see.

The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026

Bad credit loans new jersey

The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026

Last updated: 2026-10-16

When a sudden car repair or a medical bill hits, hitting a financial brick wall feels all too real. Many New Jersey residents find themselves in this exact spot, staring at a mounting debt they didn’t see coming. You need a lender that looks past a single credit score to see if you actually have the means to pay them back.

Whether you are stuck with a broken transmission in Newark or facing a surprise dental bill in Jersey City, the stress of a crisis often makes it hard to do your homework. You might feel rushed to sign anything just to solve the immediate problem, but that impulse can lead to much bigger headaches down the road.

Sorting through the sea of lenders requires a sharp eye and a realistic mindset. Some companies offer cash in a heartbeat but charge a premium for the speed, while traditional banks offer more stability but move much slower. This list focuses on finding a middle ground for those with poor credit who want to stay financially healthy.

There is a massive difference between a high-interest installment loan and a structured medical payment plan. Choosing the wrong one can turn a temporary setback into a lifelong cycle of debt. Use this guide to weigh your options carefully before you sign any paperwork.

  1. Max Cash
  2. FastLendGo
  3. XCEL Federal Credit Union
  4. Fulton Bank
  5. Loanz
  6. Cherry
  7. CareCredit

Evaluating Financial Options Across New Jersey

Deciding which lender actually works for your specific situation requires looking at several different metrics. Most people in an emergency care about speed above all else. If your car is your only way to get to work in a commuter state like New Jersey, waiting three days for a loan might be impossible.

However, the total cost of the money you borrow is what keeps you afloat in the long run. You have to account for interest rates and those sneaky hidden fees. A quick loan is useless if the interest rates swallow your entire paycheck every month.

We also looked at how much flexibility these lenders offer when your credit history isn’t perfect. Some provide title loans if you have no collateral, while others specialize in medical financing. This covers everything from a tiny $250 cash advance to a massive $60,000 signature loan.

We focused on whether a lender cares more about your income or your credit score. Generally, your ability to pay—your actual income and employment—is a much better predictor of whether you will stay on track than a single number on a credit report.

Lender Name Loan Amounts Funding Speed Credit Requirements
Max Cash $250 – $10,000+ Minutes Bad Credit Options
FastLendGo Small Loans Available Quick Access Bad Credit/No Credit
XCEL Federal Credit Union $500 – $60,000 See Site Secured/Unsecured
Fulton Bank See Site See Site See Site
Loanz $100 – $10,000 Quick/Convenient See Site
Cherry See Site Instant Approval High Approval Rate
CareCredit See Site Instant Decisions Subject to Credit

1. Max Cash

Max Cash – maxcash.com

Max Cash acts like a one-stop shop for various financial needs. Their products range from small $250 advances to larger loans that go over $10,000. This makes them a solid choice if you need immediate relief from an unexpected expense. A $500 loan might fix a broken appliance, while the larger options help with car or home repairs.

The platform is built for speed. They target people who need installment or title loans in just a few minutes. Because they work with people who have bad credit, they offer a lifeline that big-box banks often won’t. Just keep in mind that being fast often means you will pay a higher interest rate.

Pros:

  • Extremely fast processing for urgent needs.
  • Wide variety of loan types including title loans.
  • Accessible for those with bad credit.

Cons:

  • Title loans require collateral, risking your vehicle.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a flexible option for personal financing. They work with all kinds of credit tiers, whether you have good, fair, or bad credit. It is a simple way to compare local options without driving from branch to branch. (fastlendgo.com)

This lender is great for specific life events like dental work or fixing your car. If you are searching for personal loans nearby, their online model simplifies that hunt. They aggregate different profiles to help match your credit score with a provider that actually wants your application.

Pros:

  • Covers various life expenses like roof and dental repairs.
  • Options for those with no credit history.
  • Easy online comparison tool.

Cons:

  • Focus is primarily on online comparisons rather than direct banking.

3. XCEL Federal Credit Union

XCEL Federal Credit Union – xcelfcu.org

If you want more traditional stability, XCEL Federal Credit Union offers secured and signature loans. Their loan amounts can reach up to $60,000, which provides a significant cushion for big life changes. You could use these funds for debt consolidation, home upgrades, or unexpected medical bills.

As a credit union, they feel a bit more community-focused than predatory lenders. Credit unions are owned by members rather than shareholders, which often leads to more personalized service. You can choose between secured and unsecured loans to find what fits your situation. Using a savings account as collateral can often unlock much lower rates.

Pros:

  • High maximum loan amounts up to $60,000.
  • Offers secured loan options for better rates.
  • Member-focused service model.

Cons:

  • Likely requires membership or specific eligibility.

4. Fulton Bank

Fulton Bank – fultonbank.com

Fulton Bank is a major name for New Jersey residents. They have the strength of a large institution but still maintain a local feel. This makes them a solid choice for long-term banking and managing more complex financial needs over several years.

They offer everything from personal to commercial banking. They might not be the fastest choice for a $200 emergency, but they are excellent for managing significant wealth or business investments. Their stability is a big plus if you want a lender that will still be around decades from now.

Pros:

  • Highly secure and FDIC-insured.
  • Wide range of banking services from personal to commercial.
  • Strong presence in the New Jersey market.

Cons:

  • May have stricter requirements than specialized bad credit lenders.

5. Loanz

Loanz – loanz.com

Loanz focuses on helping you manage your future through specific loan solutions. With amounts between $100 and $10,000, they are great for smaller debt consolidation or upcoming costs like moving or weddings. This allows you to handle small problems before they turn into massive debts.

The main goal here is getting your life back under control. Their debt consolidation products help you manage multiple bills at once. Instead of tracking five different due dates, you can combine them into one monthly payment to simplify your budget and lower your interest stress.

Pros:

  • Low entry point for small loans starting at $100.
  • Specific products for debt consolidation.
  • Convenient digital transactions.

Cons:

  • Loan amounts are capped at a relatively modest $10,000.

6. Cherry

Cherry – withcherry.com

Cherry is a specialist in the healthcare and retail finance world. They have an impressive 90% approval rate and are used by thousands of providers. Their main goal is to let you get necessary services now and pay for them later, removing the immediate cost barrier.

The application process is incredibly fast, often taking only 35 seconds. This is a top choice for people who need dental work or home repairs immediately but want to spread out the costs. Cherry works directly through your service provider to make the process easy.

Pros:

  • Extremely fast application process.
  • High approval rate for consumers.
  • Direct integration with many healthcare providers.

Cons:

  • Limited to specific merchants and providers.

7. CareCredit

CareCredit – carecredit.com

CareCredit is a credit card built specifically for health and wellness. It is accepted at over 285,000 locations, which makes it one of the most versatile tools for medical costs. You can use it for vision, dental, or even veterinary expenses.

You can check if you prequalify without hurting your credit score. This is vital if you are worried about your standing while you shop for medical options. Many plans offer “no interest if paid in full” deals, but be careful—missing a deadline can result in retroactive interest charges.

Pros:

  • No impact on credit score during prequalification.
  • Massive network of accepted locations.
  • Flexible financing for health and wellness.

Cons:

  • Subject to credit approval and specific terms.

Understanding the Differences Between Secured and Unsecured Loans

Before you apply for anything, you need to know if a loan is secured or unsecured. This choice changes your risk level completely. A secured loan is backed by an asset, like your car, your home, or a savings account. Because the lender can take that asset if you stop paying, they are usually more willing to work with lower credit scores.

Secured loans often come with lower interest rates, but the risk to you is much higher. If you miss payments on a title loan, you could lose your vehicle. It is a trade-off between a lower rate and the risk of losing your property.

An unsecured loan isn’t backed by any physical asset. Most personal loans and credit cards fall into this category. Since the lender can’t immediately take your car if you default, they charge higher interest rates and demand better credit scores. If you fail to pay, they can’t take your house instantly, but they can sue you or garnish your wages.

How to Prepare for a Loan Application

You can increase your chances of getting approved and getting a better rate by having a plan. Following these steps helps you avoid unnecessary hits to your credit score:

  • Verify Your Documentation: Gather your recent pay stubs, bank statements, and ID before you start. If you are using an asset as collateral, have proof that you actually own it.
  • Audit Your Debt-to-Income (DTI) Ratio: Lenders look at how much of your income goes to existing debt. If that number is too high, you might get denied. Try paying down small balances before you apply.
  • Check for Errors in Your Credit Report: One wrong late payment can ruin your score. Use a free service to find and dispute mistakes before you go looking for money.
  • Compare APRs, Not Just Interest Rates: The Annual Percentage Rate (APR) includes interest and mandatory fees. This is the real cost. A 10% rate with a $500 fee might be more expensive than a 12% rate with no fees.
  • Use Prequalification Tools: Look for lenders that offer “soft pulls.” This lets you see your estimated rates without leaving a permanent mark on your credit report.

Avoiding Common Financial Pitfalls

Choosing a lender isn’t just about finding the first person to give you cash. You have to read the fine print. Many people take a high-interest loan just because they are in a rush. This can trap you in a cycle where the total interest you pay is actually higher than the money you originally borrowed.

Always look at the total cost of the loan, not just the monthly payment. A small monthly payment might hide a very long term that costs you thousands more in interest. A $5,000 loan with a $100 payment sounds great until you realize you’ll be paying it for seven years.

One mistake to avoid is applying for too many loans at once. Every application can trigger a “hard inquiry,” which lowers your score. If you apply for five loans in one week, banks will think you are desperate for cash. Use prequalification tools first to narrow your list before you make any official moves.

Five Best Lenders for No Credit Check Home Improvement Loans in 2026

No credit check home improvement loans

Five Best Lenders for No Credit Check Home Improvement Loans in 2026

Last updated: 2026-10-17

Trying to fix a leaking roof or remodel a kitchen when your credit score is in the gutter feels like chasing a ghost. You want to renovate your sanctuary, but traditional banks often slam the door shut before you even finish the application. It is a frustrating cycle of rejection that leaves many homeowners stuck.

This list helps people who need capital for home improvements but cannot rely on a pristine credit report. Choosing a lender requires looking past flashy advertisements. You should focus on actual funding speed, total loan amounts, and whether a soft inquiry will protect your score while you shop around.

  1. Solar Energy Loan Fund
  2. JetzLoan
  3. SoFi
  4. Upgrade
  5. Best Egg

How This Ranking of Home Improvement Lenders Was Evaluated

The selection process focused on accessibility and transparency. Many people searching for these loans are in a tight spot financially. Because of this, the ability to check rates without a hard credit pull is a non-negotiable requirement. We looked for lenders that prioritize your ability to repay over a single number on a credit report.

We also analyzed how quickly cash hits your account and the total amount available to the borrower. A lender that takes three weeks to send money is useless when a contractor needs a deposit by Friday. Each entry was weighed against its stated mission, speed of funding, and whether the terms were competitive for the current 2026 market.

Lender Name Max Loan Amount Funding Speed Credit Impact of Inquiry Key Feature
Solar Energy Loan Fund See site See site No impact Mission-driven
JetzLoan $50,000 As little as 24 hours No impact Fast connection
SoFi See site Same-day funding See site No collateral required
Upgrade $50,000 Fast funding No impact Cash back options
Best Egg $50,000 See site See site Homeowner discount

Top Rated Lenders for Home Renovations and Repairs

1. Solar Energy Loan Fund

Solar Energy Loan Fund – solarenergyloanfund.org

This lender operates with a heart, focusing on building thriving, sustainable communities. They provide fair capital to help households and nonprofits improve their financial strength and resilience. It is a refreshing change from the cold, clinical nature of many big-box banks that only care about your credit score.

They specifically target home improvements that contribute to community stability and sustainability. If your goal is to invest in better housing or stronger local infrastructure, this mission-driven approach might be your best bet. It is about more than just cash; it is about long-term community impact.

The application process is designed to be fair, and prequalifying will not affect your credit score at all. This allows you to explore your options without the fear of a sudden dip in your rating. It is a low-risk way to see if you qualify for their low-cost financing options.

Pros:

  • Mission-driven approach focusing on community resilience.
  • Prequalifying does not affect your credit score.
  • Fair capital for households and nonprofits.

Cons:

  • Focuses heavily on specific community and sustainability goals.

2. JetzLoan

JetzLoan – jetzloan.com

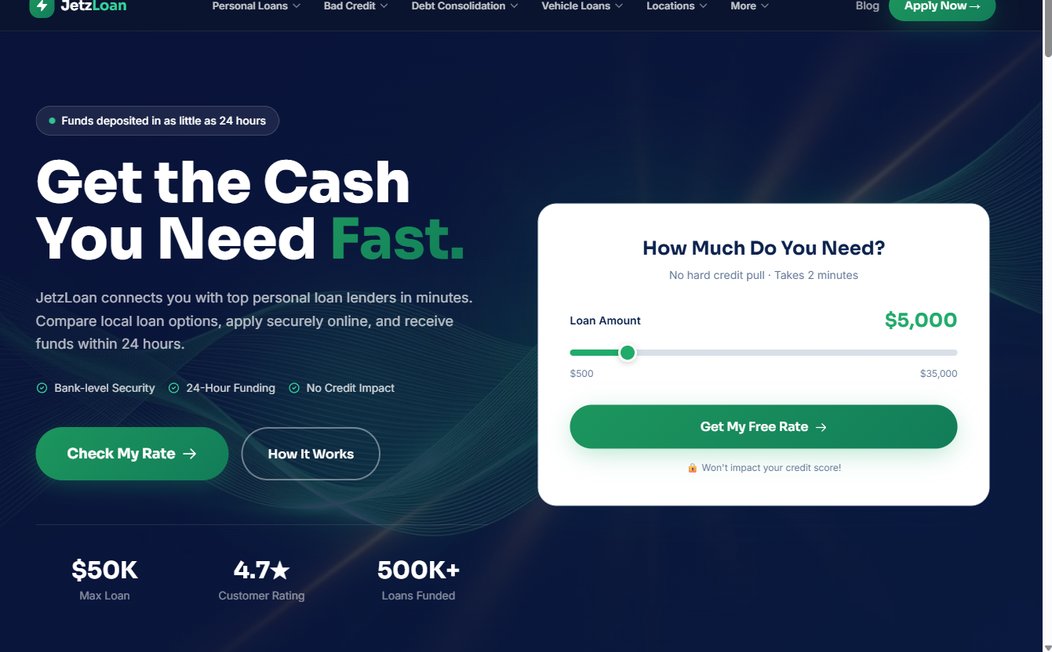
When the clock is ticking and a repair cannot wait, JetzLoan steps into the ring. They connect you with top personal loan lenders in just a few minutes. It is a streamlined process designed for people who need cash quickly to handle unexpected home maintenance emergencies.

The speed here is hard to beat, with funds potentially deposited into your account in as little as 24 hours. This makes them an excellent choice for those who need to pay a contractor immediately to keep a project on schedule. They handle amounts from $500 up to $50,000.

The platform is built for transparency, offering a simple two-minute application process. You can get a free rate without any hard credit pull, which is a massive relief for those worried about their standing. It is a high-speed option for the modern, busy homeowner.

Pros:

  • Extremely fast funding, potentially within 24 hours.
  • No hard credit pull to check your rate.
  • Simple, two-minute application process.

Cons:

  • Max loan amount is capped at $50,000.

3. SoFi

SoFi – sofi.com

SoFi is a massive player in the financial space, offering a wide array of services from banking to mortgages. For home improvements, they stand out because they offer same-day funding in many cases. This level of speed is rare and incredibly helpful during urgent renovation projects.

They do not require collateral for their personal loans, which removes the stress of putting your home at risk to fix it. This makes the process much cleaner and less intimidating for first-time borrowers. It is a sophisticated option for those who want a streamlined digital experience.

Beyond loans, they offer a variety of banking features, including high-yield savings options. If you want to consolidate your financial life in one place, SoFi provides a very polished, all-in-one ecosystem. It is a premium choice for a tech-savvy borrower.

Pros:

  • Same-day funding options available.
  • No collateral required for loans.
  • Comprehensive suite of financial services.

Cons:

  • May have stricter requirements than specialized bad credit lenders.

4. Upgrade

Upgrade – upgrade.com

Upgrade positions itself as a versatile tool for various financial needs, including home improvement. They offer personal loans up to $50,000 with fixed rates that provide stability for your monthly budget. This is ideal if you want to know exactly what your payment will be every single month.

One of the most interesting aspects of Upgrade is the ability to check your rate without impacting your credit score. They also offer various ways to get value back, such as cash back on certain purchases or high-yield savings. It feels like a more modern take on traditional lending.

They have a massive customer base, with over 8 million customers and $50 billion borrowed. This scale suggests a very refined process that can handle everything from large purchases to debt consolidation. It is a solid, middle-ground option for many users.

Pros:

  • Fixed rates provide long-term budget certainty.
  • Check rates without impacting your credit score.
  • Offers cash back and savings incentives.

Cons:

  • Personal loan terms can vary significantly.

5. Best Egg

Best Egg – bestegg.com

Best Egg focuses on making people feel money-confident through a hassle-free application process. They offer personal loans up to $50,000 with fixed interest rates and flexible terms. This flexibility allows you to tailor the loan to fit your specific monthly budget constraints.

For homeowners specifically, they offer a discount that can lead to their lowest available rates. They also allow you to use fixtures like cabinets or vanities as collateral to potentially secure better terms. This is a clever way to leverage your home’s value without a full mortgage.

The company carries an A+ rating from the Better Business Bureau and has thousands of excellent reviews. This reputation for reliability makes them a strong contender for those who want peace of mind. They are all about making the process quick and easy.

Pros:

  • Homeowner discounts on interest rates.
  • Option to use fixtures as collateral.
  • Highly rated customer satisfaction.

Cons:

  • Requires more information to find available options.

Avoiding Pitfalls When Seeking Fast Financing

When you are desperate to fix a crumbling staircase, it is easy to sign anything that comes your way. Do not let the urgency of a repair lead you into a high-interest trap. Always verify if the lender is a legitimate entity and check for hidden fees that might appear in the fine print of your contract.

Avoid lenders that demand significant upfront fees before they even issue the loan. This is a major red flag in the lending industry. Also, remember that “no credit check” does not mean “no consequences.” While a soft pull won’t hurt you, the actual debt you take on will still show up on your credit report.

Finally, always compare the total cost of the loan, not just the monthly payment. A lower monthly payment often means a much longer term, which can end up costing you thousands more in interest over the life of the loan. Do the math before you sign your name on the dotted line.

The 7 Best Lenders for Loans for Independent Contractors in 2026

Loans for independent contractors

The 7 Best Lenders for Loans for Independent Contractors in 2026

Last updated: 2026-10-16

Trying to secure financing as a 1099 worker often feels like walking a tightrope during a thunderstorm. Traditional banks usually demand decades of steady paychecks. However, the modern economy thrives on the hustle of freelancers and solo entrepreneurs. Finding a lender that actually speaks your language is the first step toward scaling your business or covering an unexpected gap.

Choosing a partner requires looking beyond just the interest rate. You have to consider how fast the cash hits your account. You should also ask whether the lender cares more about your personal credit score or your actual business revenue. This breakdown looks at the top contenders to help you find a match for your specific financial temperament and immediate needs.

  1. Swoop US
  2. Acorn Finance
  3. FastLendGo
  4. Giggle Finance
  5. Lendesca
  6. Greenbox Capital
  7. Discover

How These Lenders Were Evaluated

The selection process focused on the unique hurdles faced by non-traditional workers. We looked for lenders offering specialized products like invoice factoring, cash advances, and SBA-backed options. It is not just about the total amount of money available. Accessibility matters most for someone without a standard W-2 salary.

Speed of funding and credit flexibility were the primary metrics used for this comparison. Many contractors deal with seasonal fluctuations. A lender that can move in minutes is often worth more than a lower rate that takes months to process. Each entry was vetted for its ability to serve various credit profiles, from excellent to bad credit.

Lender Name Loan Amounts Funding Speed Credit Requirements Special Features
Swoop US See site Minutes Varies Savings opportunities
Acorn Finance See site See site Good & Bad Credit No credit score impact to check rates
FastLendGo $500 – See site Quick access Bad to Great Credit Personal and specialized loans
Giggle Finance Up to $15,000 Minutes Side hustles/1099s Repeat customers up to $20k
Lendesca Up to $1,250,000 Weeks SBA/Freelance focus SBA expertise
Greenbox Capital $3,000 – $500,000 As little as 1 day Low/Bad Credit Merchant Cash Advances
Discover See site See site See site Credit card benefits

Top Rated Funding Options for Freelancers

1. Swoop US

Swoop US – swoopfunding.com

Swoop US connects your business needs with a wide variety of funding sources. Instead of just offering one type of loan, they provide a platform where you can find everything from equity finance to grants and commercial mortgages. It is a one-stop shop for those who need variety.

This platform is useful if you want to save on business expenses while searching for capital. By comparing multiple matches, you can find the most efficient way to fuel your growth. It is a smart choice for established businesses looking for more than just a simple cash injection.

Pros:

  • Access to diverse funding types like grants and tax credits.
  • Potential to find significant savings on business expenses.
  • Fast matching process to get started quickly.

Cons:

  • Higher interest rates may apply for those with bad credit.
  • Borrowing amounts might be smaller for certain credit profiles.

2. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance specializes in making the financing process easier for home improvement contractors. They understand that your customers often need financing for large projects like pool installations or kitchen remodels. You can offer professional financing options without the usual heavy lifting.

One of the most attractive features is the ability to check personalized rates without any impact on your credit score. This allows contractors to shop around without any fear of damaging their financial standing. It is a transparent way to offer value to your clients while ensuring they can afford your services.

Pros:

  • Zero dealer fees for contractors.
  • No credit score impact when checking rates.
  • Works with both good and bad credit.

Cons:

  • Focused primarily on the home improvement sector.
  • Requires the customer to manage the financing process.

3. FastLendGo

FastLendGo – fastlendgo.com

If you find yourself in a situation where you need quick access to cash, FastLendGo offers a variety of personal financing solutions. They cater to a wide range of needs, from emergency auto repairs to dental financing or even motorcycle loans. It is a versatile option for personal needs.

The platform is designed to help you compare local personal loan options quickly. Whether you have great credit or are navigating the difficulties of bad credit, they have a product designed to meet you where you are. It is a straightforward approach to personal liquidity.

Pros:

  • Wide variety of loan purposes, from auto to dental.
  • Options available for various credit tiers.
  • Simple online comparison process.

Cons:

  • Primarily focused on personal rather than business-specific growth.
  • Terms and rates are not explicitly listed upfront.

4. Giggle Finance

Giggle Finance – gigglefinance.com

Giggle Finance is built specifically for the modern side-hustler and the 1099 worker. They recognize that the traditional banking model often leaves out the very people who drive the gig economy. Their mission is to provide fast, friendly funding for those who might be overlooked by big banks.

You can potentially secure up to $15,000 in just a few minutes. This is a lifesaver when a sudden business opportunity or expense arises. For repeat customers, that limit can even increase to $20,000. It is a streamlined solution for those who need speed above all else.

Pros:

  • Extremely fast funding, sometimes in minutes.
  • Specifically designed for 1099 and self-employed workers.
  • Higher limits available for loyal, repeat customers.

Cons:

  • Lower total loan amounts compared to traditional business loans.
  • Fast speed often comes with higher interest costs.

5. Lendesca

Lendesca – lendesca.com

Lendesca is a modern way to approach SBA loans, a process that is notoriously slow and bureaucratic. They have rebuilt the experience to help business owners move from application to funded in weeks rather than the months typically required. It is a high-level solution for serious growth.

They offer specialized products like freelance cash advances. These focus on your actual cash flow rather than just a corporate credit profile. With expertise in SBA loans, they are a powerhouse for those looking to secure significant capital through government-guaranteed channels.

Pros:

  • Expertise in navigating the complex SBA loan process.
  • Faster turnaround times than traditional SBA lenders.
  • Offers freelance cash advances based on cash flow.

Cons:

  • SBA loans generally require a higher credit score (around 680).
  • The process is more complex than simple cash advances.

6. Greenbox Capital

Greenbox Capital – greenboxcapital.com

Greenbox Capital is a powerhouse for small and mid-sized businesses that need working capital immediately. They offer alternative funding, such as Merchant Cash Advances. These can be repaid through a percentage of your daily or weekly sales. This aligns your repayments with your actual revenue.

They serve a massive range of industries across the United States, Canada, and Puerto Rico. With funding available in as little as one business day, they are the go-to for businesses that need to seize an immediate opportunity or cover a sudden inventory cost.

Pros:

  • Extremely fast funding, sometimes in one business day.
  • Large funding range from $3,000 up to $500,000.
  • Flexible repayment through Merchant Cash Advances.

Cons:

  • Merchant Cash Advances can be more expensive than traditional loans.
  • Terms are tied to your sales volume, which can vary.

7. Discover

Discover – discover.com

Discover is a titan in the consumer banking world. They offer a level of stability and nationwide acceptance that many niche lenders cannot match. Their credit cards are accepted by 99% of merchants. This makes them a reliable tool for day-to-day business expenses and personal needs alike.

They provide a variety of products, including personal loans and credit cards with attractive cashback incentives. It is a solid, dependable option for contractors who want a mainstream financial partner with high-quality customer service and security features.

Pros:

  • Massive nationwide acceptance of their credit products.
  • High level of security and financial insight tools.
  • Strong cashback rewards on certain categories.

Cons:

  • Less specialized for the unique needs of 1099 contractors.
  • Standard credit requirements apply.

Navigating the Lending Landscape

When you are choosing a lender, avoid the trap of looking only at the monthly payment. A low monthly payment often masks a much higher total cost of borrowing over the life of the loan. Always ask for the total amount you will pay back by the end of the term to see the true cost of the capital.

Another common mistake is failing to match the loan type to your specific business cycle. If you have a seasonal business, a Merchant Cash Advance might feel easier because it scales with your sales. However, it could become incredibly expensive during your slow months. Always align your debt structure with the rhythm of your actual income.

Top 5 Fence Financing Options: 2026 Rankings for Homeowners

Fence financing

Top 5 Fence Financing Options: 2026 Rankings for Homeowners

Last updated: 2026-10-17

Planning a backyard renovation often feels like trying to catch lightning in a bottle. You have the vision for a beautiful new perimeter, but the immediate lump sum cost can be a bitter pill to swallow. Many homeowners find themselves staring at old, rotting wood and wondering if they can truly afford a replacement right this second.

The gap between a desire for privacy and a bank balance that says “wait until next year” is where most projects stall. Securing the right funds is about more than just finding the lowest interest rate. It involves looking at how quickly the money hits your account and whether the application process will leave your credit score in the dust.

A delay in funding could mean your contractor moves on to another job, leaving your yard exposed for another season. This guide cuts through the noise to help you find the most reliable way to pay for your next enclosure.

  1. Guerrero Fences
  2. FenceUSA
  3. JetzLoan
  4. Allied Fence
  5. Perimtec

Evaluating the Best Ways to Pay for Your Perimeter

To determine which lenders stand out in 2026, the selection process focused on accessibility and speed. A lender that requires a mountain of paperwork is useless when a storm is threatening your property. We looked for providers that offer clear paths to approval, whether through direct company financing or third-party lending platforms.

We specifically analyzed the friction points in the application process. We looked at how many days it takes from “click” to “cash” and the depth of the credit inquiry required. The comparison also weighed the impact on credit scores. In an era where financial privacy is paramount, the ability to “pre-qualify” without a hard credit pull is a massive advantage.

This “soft pull” allows you to see your potential interest rates and monthly payments without triggering the formal inquiry that can cause a temporary dip in your score. We prioritized options that allow you to shop around for the best terms without risking your standing with the big banks.

When comparing these options, consider the following variables:

  • Liquidity vs. Leverage: Do you want to use your own savings (liquidity) or borrow against your future income (leverage)?
  • Collateral Requirements: Most personal loans for fencing are unsecured, meaning you don’t have to put your home at risk, unlike a Home Equity Line of Credit (HELOC).
  • The “Total Cost” Factor: A 0% interest period is powerful, but only if you can pay the full balance before the interest kicks in. If you miss that window, some lenders apply “back-dated” interest, which can be devastating.

Lender Name Max Loan Amount Funding Speed Credit Impact Terms/Details
Guerrero Fences see site see site Pre-qualify available 0% interest for 6 months
FenceUSA $500+ see site see site Flexible plans available
JetzLoan $50,000 24 hours No hard credit pull Personal loans
Allied Fence see site Varies by project Varies by project Custom financing options
Perimtec see site see site No credit impact check Through Wisetack

Top Rated Fence Financing Providers of 2026

1. GUERRERO FENCES

Guerrero Fences – guerrerofences.com

Guerrero Fences operates with a deep understanding of the Texas landscape, serving areas from the Rio Grande Valley to San Antonio. They specialize in a wide variety of installations, including wood, chain link, and wrought iron. Their approach to financing is designed to make high-quality outdoor solutions accessible to the local community.

Whether you are looking for a rustic cedar privacy fence or a heavy-duty security perimeter, their financial models are built around the specific needs of Texas homeowners. This provider is an excellent fit for homeowners who want to spread out their costs without feeling the immediate sting of a large bill.

By offering specific promotional terms, they bridge the gap between needing a secure property and managing a monthly budget effectively. For instance, their 6-month 0% interest option is perfect for someone who has received a seasonal bonus or tax refund and wants to keep their cash liquid while still getting the job done immediately.

Pros:

  • Offers 0% interest for a 6-month period.
  • Wide range of materials including hurricane-grade chain link.
  • Serves multiple major Texas regions.

Cons:

  • Promotional 0% terms may require specific credit qualifications.

2. FENCEUSA

FenceUSA – fenceusa.com

FenceUSA is a veteran in the industry, boasting over 45 years of experience in the South Jersey, Delaware, and Pennsylvania regions. They are a full-service operation, meaning they handle everything from the initial decking to the final railing installation. Their longevity speaks to a level of reliability that is hard to find in a modern market of “fly-by-night” contractors.

When you finance through a company with four decades of history, you aren’t just paying for a fence; you are paying for the certainty that the company will be around to honor its warranty. For those looking for structured payment plans, FenceUSA offers several affordable options.

They cater to various material choices, ensuring that whether you want vinyl, aluminum, or chain link, the financial path remains relatively smooth and predictable for the homeowner. Their experience allows them to offer nuanced payment schedules that align with the phases of construction. This lets you pay as the work progresses rather than all at once.

Pros:

  • Decades of established industry experience.
  • Flexible plans for multiple fence types.
  • Covers a large tri-state area.

Cons:

  • Financing options are subject to specific project types.

3. JETZLOAN

JetzLoan – jetzloan.com

JetzLoan acts as a powerful bridge between consumers and top personal loan lenders. Unlike traditional banks that might drag their feet for weeks with manual underwriting and endless verification calls, this service focuses on extreme speed. It is an ideal choice for someone who needs to secure funds immediately to start a project before the weather turns sour or a competitor grabs your preferred installation slot. (jetzloan.com)

The platform is built for convenience, allowing users to compare local options in just a few minutes. Because they prioritize a “no hard credit pull” model for the initial phase, you can explore your financial limits without any fear of damaging your score. This is a critical distinction.

You can check five different loan scenarios, and your credit report will remain untouched until you decide to commit to a specific loan offer. This freedom allows for much more aggressive shopping for the best possible rate.

Pros:

  • Extremely fast funding, often within 24 hours.
  • High maximum loan amount of up to $50,000.
  • No impact on credit score during the initial rate check.

Cons:

  • As a middleman, rates depend heavily on your personal profile.

4. ALLIED FENCE

Allied Fence – alliedfence.com

Allied Fence is a heavy hitter in the Georgia market, having served homeowners since 1953. With over 100,000 successful installations under their belt, they are clearly not playing around. They focus heavily on enhancing curb appeal and security through custom-designed solutions that are built to last. Their reputation in the Southeast is built on a foundation of heavy-duty materials and expert craftsmanship.

For the homeowner who wants a premium, custom-designed fence but needs to manage the cash flow, Allied Fence provides professional financing services. Their deep history suggests a level of stability that gives customers peace of mind during long-term payment arrangements.

If you are planning a large-scale perimeter project involving stone pillars or complex wrought ironwork, their ability to integrate financing into the custom design process is a significant advantage. They understand that complex builds require complex financial planning.

Pros:

  • Over 70 years of professional expertise.
  • Massive track record with 100,000+ installations.
  • Expertise in custom design and high-end security.

Cons:

  • Focus on custom work may lead to higher upfront project costs.

5. PERIMTEC

Perimtec – perimtec.com

Perimtec is the go-to choice for those seeking a modern, architectural aesthetic. They specialize in high-end metal systems, including steel frame and aluminum options. Their products are designed for people who view their fence as a design element rather than just a boundary. It is an extension of the home’s architecture.

This is common for modern builds or luxury renovations where a standard wooden picket fence would look out of place. They have streamlined the financing process by partnering with Wisetack. This allows customers to pre-qualify for financing for their modern metal systems without any impact on their credit score.

The path to a premium installation becomes much less daunting. The integration is seamless; you often receive a digital link to select your payment terms right from your smartphone during the consultation phase.

Pros:

  • Specializes in high-quality, modern metal systems.
  • Uses Wisetack for seamless, credit-safe pre-qualification.
  • Ideal for both residential privacy and commercial projects.

Cons:

  • Specialized metal systems may be more expensive than traditional wood.

Step-by-Step: How to Secure Your Fence Financing

Navigating the financial side of a renovation requires a methodical approach to avoid unnecessary debt or delays. Follow these steps to ensure you are prepared before the first post is even dug:

  1. Calculate the Total Project Cost: Do not just look at the material price. Include tax, delivery fees, and labor. If you are adding a gate or a custom entryway, factor those in separately as they often carry higher premiums.
  2. Check Your “Soft” Score: Before applying for anything, check your credit score through a free service. This gives you a baseline. If your score is below 650, you may want to focus on lenders like JetzLoan or specialized contractor financing rather than traditional bank loans.
  3. Request Multiple Quotes: A fence is a physical product, but the price is often negotiable based on the payment method. Ask installers if they offer a discount for cash/check versus financing, or if they have a preferred lender that offers better rates.
  4. Review the “Fine Print” on Interest: Look specifically for “deferred interest” clauses. If you choose a 0% interest plan but fail to pay the balance in full by the deadline, you might be charged interest on the entire original amount from day one.

Common Financing Pitfalls to Avoid

Choosing a lender is not a one-size-fits-all endeavor. If your priority is the lowest possible monthly payment, you might lean toward a company offering 0% interest for a short term. However, if you need a large sum of money to cover a massive commercial project, a personal loan provider might be the better tool.

The “lowest monthly payment” is often the most dangerous metric if the term is 72 months instead of 24. You will end up paying significantly more for a piece of wood and wire than the original quote suggested. One common mistake is neglecting to check the total cost of the loan.

A low monthly payment often masks a much higher total interest cost over the life of the loan. Always look at the “total amount payable” to ensure the convenience of financing doesn’t end up costing you a fortune in the long run. A $5,000 fence with a $50 monthly payment sounds great until you realize you’ll be paying it off for a decade.

Another pitfall is failing to verify if the financing is tied to the installer or a third party. Third-party financing, like Wisetack or JetzLoan, can sometimes offer more flexibility, whereas direct company financing might be more integrated into your specific installation contract. If the contractor goes out of business, the third-party lender still expects payment. Knowing which is which will save you significant headaches during the installation process and during any future warranty claims.